
Avarda Bank (OM:AVARDA) Q3 Earnings Put Its Valuation Back In Focus
Avarda Bank (OM:AVARDA) just released its third quarter 2026 results, highlighting higher net interest income, net income, and earnings per share, which put fresh attention on the stock’s current valuation.
The latest third quarter update arrives after a strong run in the shares, with Avarda Bank’s 1-day share price return of 2.35% and 7-day share price return of 11.65% adding to a 34.41% year-to-date share price gain. The 3-year total shareholder return above 300% signals long-term momentum that recent earnings and the current valuation debate are now helping to reframe.
Compare Avarda Bank's latest move with a curated set of financially strong peers by scanning the 194 high quality undervalued stocks that may still be priced for a different phase of their story.
Bulls point to Avarda Bank’s stronger Q3 metrics and DCF upside, while bears highlight the richer P/E after the surge. Which case does the current valuation actually lean toward?
Price-to-Earnings of 17.4x: Is it justified?
Avarda Bank is trading on a P/E of 17.4x, which puts a clear premium on the SEK217.5 share price compared to many listed banks and raises the question of whether that richer tag is consistent with its fundamentals.
The P/E ratio compares what investors are paying per share with the earnings that each share represents. For a lender like Avarda Bank, it effectively shows how much the market is willing to pay today for each unit of current profit, given its growth profile, asset quality, and capital returns.
Here the premium is striking. The stock changes hands at 17.4x earnings while the European Banks industry sits at 11.7x and the peer group average is 12.2x. In other words, the market is assigning Avarda Bank a much higher earnings multiple than both its broader sector and closer comparables. Our fair P/E estimate of 15.1x is also below the current level, which signals a valuation that could compress towards that lower ratio if sentiment cools or earnings delivery falls short of expectations.
Explore the SWS fair ratio for Avarda Bank.
Result: Price-to-Earnings of 17.4x (OVERVALUED)
Still, the Avarda Bank story can be knocked off course if earnings disappoint against a 17.4x P/E, or if broader European bank valuations reset lower.
Find out about the key risks to this Avarda Bank narrative.
Another view on Avarda Bank's value
The first look at Avarda Bank focused on the 17.4x P/E, which suggests a richer tag than both industry and peers. Yet the SWS DCF model points the other way, with a future cash flow value of SEK326.94 against a SEK217.5 share price, implying the stock screens as undervalued on that lens.
Both approaches rely on different assumptions about how long current profitability and growth can hold up. The practical question for you is which framework you trust more when the signals disagree like this.
Look into how the SWS DCF model arrives at its fair value.
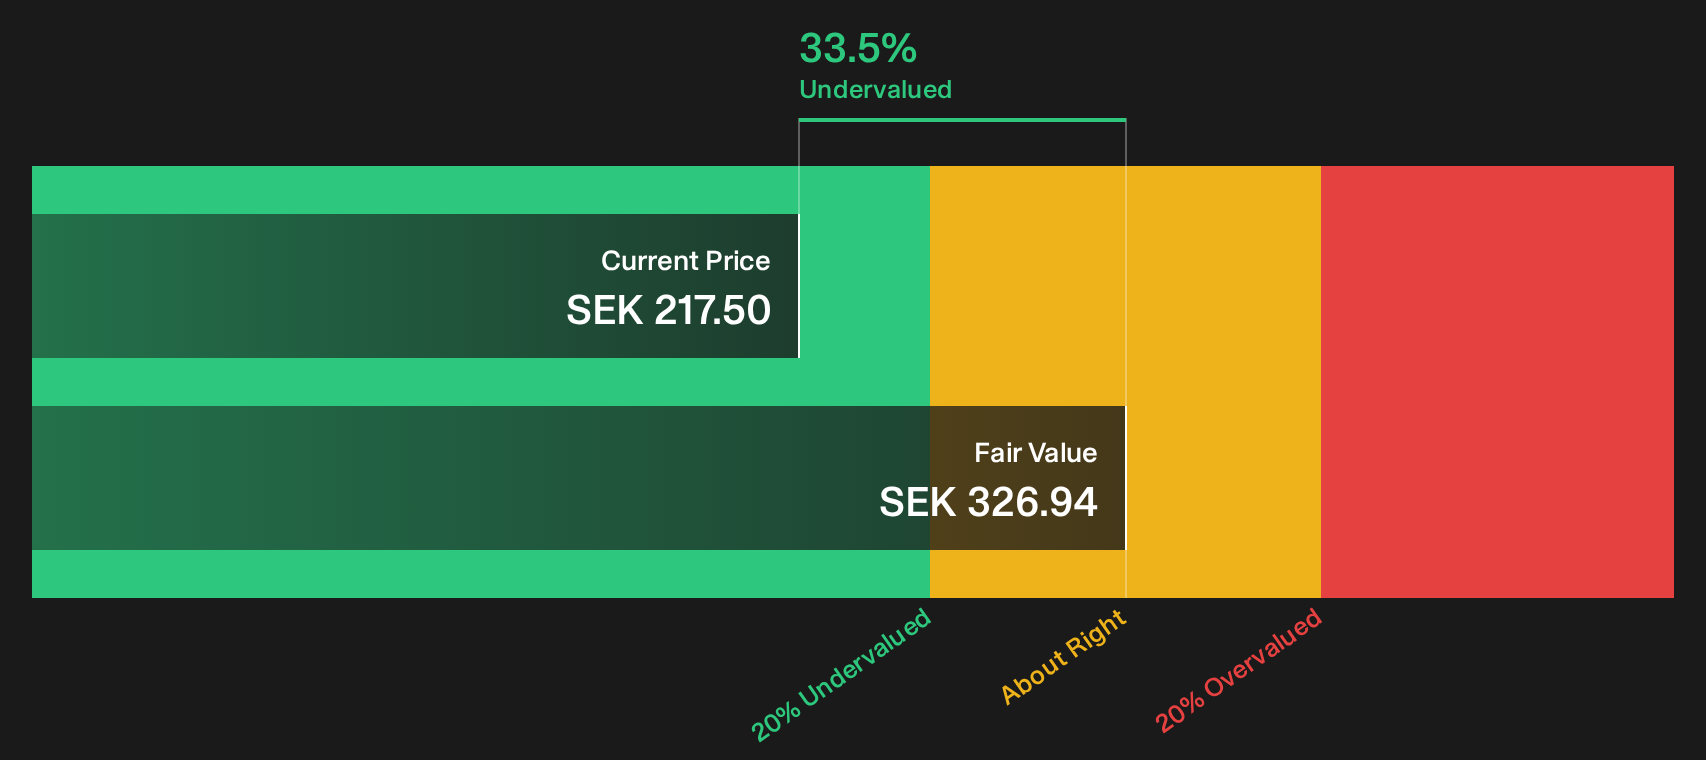
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avarda Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The bullish and bearish angles on Avarda Bank are clear enough, but the real edge comes from doing the work yourself and moving early. Use the full breakdown of 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Avarda Bank?
If you are serious about building a stronger portfolio, do not stop at Avarda Bank. Use these focused screens to spot opportunities others might overlook.
- Target resilient compounding potential by filtering for businesses with consistent fundamentals and sturdy finances through the list of solid balance sheet and fundamentals (202 results).
- Hunt for quality at a discount by zeroing in on companies that appear mispriced on key fundamentals using the 194 high quality undervalued stocks.
- Stack potential cash returns on top of price moves by focusing on reliable income payers with the 218 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com