
Mirion Technologies (MIR) Heads Into October Results With A Nuclear Growth Valuation Debate
Mirion Technologies (MIR) has put a date on its next catalyst, with third quarter 2026 results scheduled after the close on October 27, followed by an investor call the next morning.
Mirion Technologies heads into that October update after a tough stretch for the share price, with the stock down 34.79% year to date and weaker 7 day and 90 day share price returns, even though the 3 year total shareholder return of 122% still points to a very different longer term experience for investors.
Scan beyond Mirion Technologies and see how it stacks up against a hand picked group of radiation, power and safety peers in the 16 nuclear energy infrastructure stocks
Mirion Technologies now trades well below both analyst targets and one intrinsic value estimate, after a sharp share price slide. The real tension is simple: Is the gap mispricing or a fair reset on expectations?
Most Popular Narrative: 37% Undervalued
At a last close of $15.54 against a widely followed fair value estimate of $24.80, Mirion Technologies is being framed as materially undervalued by the prevailing narrative, which leans heavily on long term demand for its nuclear and software offerings and a richer earnings profile several years out.
The accelerating global shift toward expanded nuclear power generation, coupled with rising capital budgets for modernization, life extensions, and increased capacity of the existing reactor fleet, is likely to drive sustained double digit organic revenue growth and expand Mirion's higher margin installed base business in coming years. Strong momentum in advanced nuclear projects, including utility scale new builds and rapid activity in the small modular reactor (SMR) market, has materially broadened Mirion's pipeline of large, multi year opportunities, creating potential for significant step changes in future order intake, backlog, and top line revenue.
See why 8 investors see Mirion Technologies as 37% undervalued.
Result: Fair Value of $24.80 (UNDERVALUED)
Still, the Mirion Technologies story can break if nuclear sector spending slows, or if acquisitions like Certrec drag on integration, margins, or cash generation.
Find out about the key risks to this Mirion Technologies narrative.
Another Take On Mirion Technologies Valuation
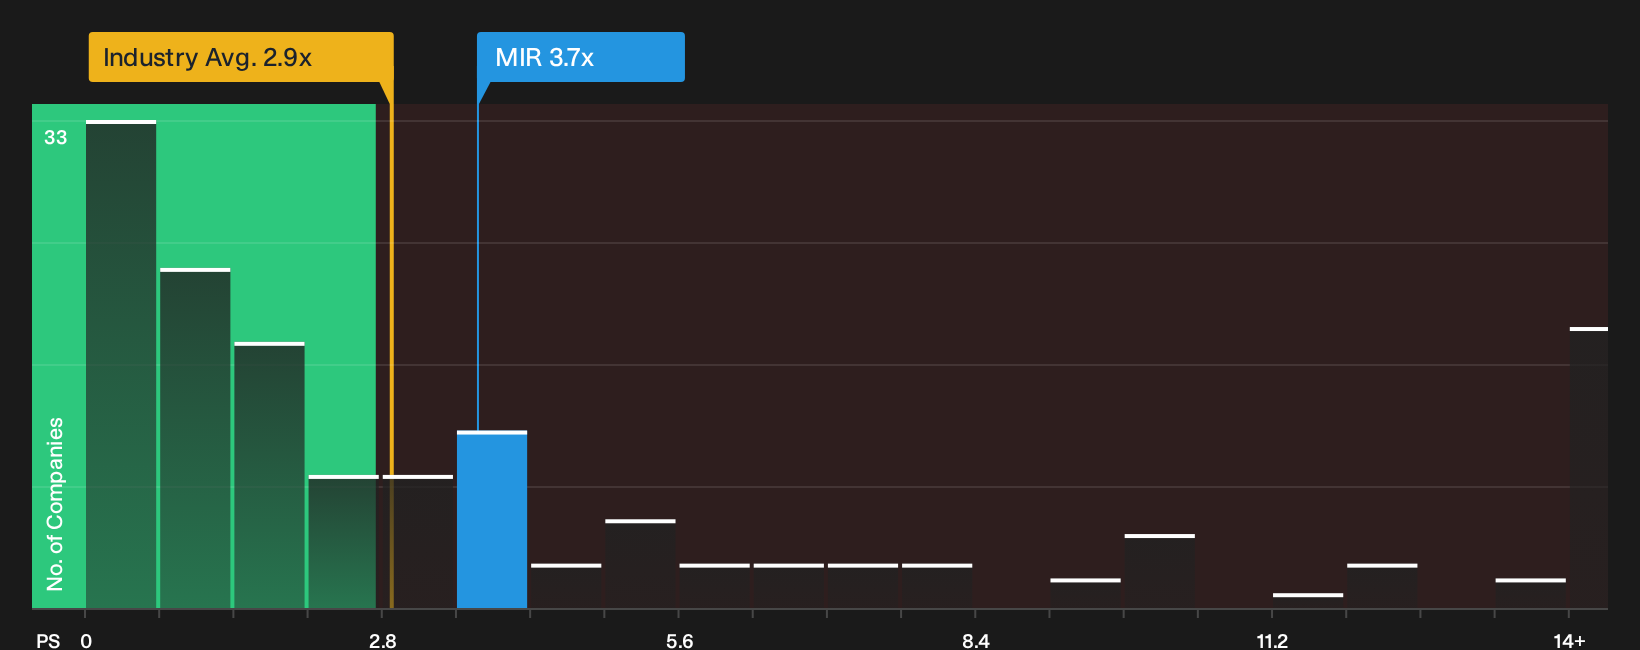
The story shifts when you look at Mirion Technologies through its sales multiple rather than a fair value model. The stock trades on a P/S of 3.7x, which is richer than both the US Electronic industry at 2.9x and an estimated fair ratio of 2.9x. That gap implies investors are already paying up on this metric, so it may be useful to consider how comfortable you are with that premium if sentiment on nuclear or software changes.
For a closer read on how this pricing compares with the underlying numbers, have a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Mirion Technologies can be confusing, so treat this as your cue to move quickly, review the data yourself, and weigh both the upside and the concerns using the 4 key rewards and 2 important warning signs
Looking For More Ideas Beyond Mirion Technologies?
Round out your watchlist with a few fresh angles. Spread your risk, keep your options open, and give yourself more ways to win over time.
- Target resilience first and filter for companies with stronger financial footing using the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a reasonable entry point by running your own search across the 33 high quality undervalued stocks.
- Focus on potential cash flow and stability with the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com