
ZTO Express (Cayman) (ZTO) Stock May Still Be A Bargain On Earnings
ZTO Express (Cayman) has delivered a mixed ride for shareholders, which raises a simple question: Is the current US$20.02 share price properly grounded in what the business is earning today?
- The stock is down 29.3% over 5 years, which puts the spotlight firmly on whether the underlying earnings profile can justify where the valuation now sits.
- The business model leans on parcel volume, operational efficiency and cost control, so any shift in margins or capital intensity can reshape how much value investors ascribe to each dollar of profit.
- Your read on ZTO Express (Cayman) is one view; the desks covering it have another. See what analysts think ZTO Express (Cayman)'s shares could be worth.
The stock's next move may depend on whether ZTO Express (Cayman)'s current earnings are strong enough to support the present market price.
If you are weighing ZTO Express (Cayman) against other ideas where price and fundamentals matter just as much, a focused screener of 33 high quality undervalued stocks can be a useful next stop.
Does ZTO Express (Cayman) Look Undervalued on Earnings?
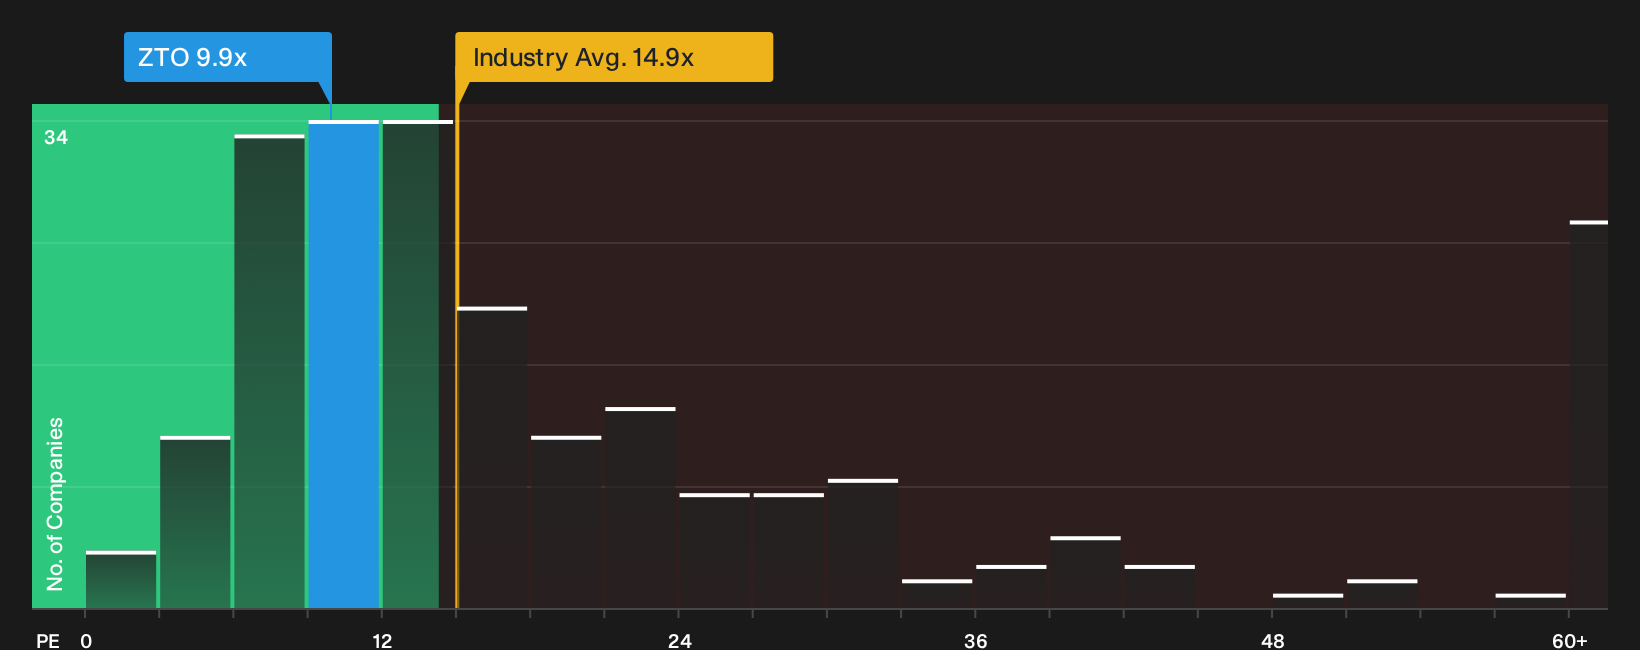
The P/E ratio fits ZTO Express (Cayman) well because earnings remain a central yardstick for a parcel logistics operator. On this measure, the stock trades at about 9.9x earnings, which is well below the logistics industry average of roughly 14.9x and far under the broader peer group around 27.7x. For a business where profit generation is closely tied to parcel throughput and cost control, that is a meaningful gap.
The Fair Ratio model, which looks at ZTO Express (Cayman)'s growth profile, profitability, sector and risk, points to a higher earnings multiple than where the shares trade now. That places the current 9.9x P/E below what this framework suggests could be justified, so the market is putting a relatively low price on each dollar of profit compared with those fundamentals. For a closer sense of how large that gap is and what it might imply for your own return expectations, you can explore the detailed multiple workup here. Explore the numbers behind ZTO Express (Cayman)'s P/E valuation.
The ZTO Express (Cayman) Narrative: What Would Justify Today's Price?
Narratives for ZTO Express (Cayman) pick up where the P/E puzzle leaves off, by spelling out which specific paths for future growth, margins and earnings would need to hold for the current price to look materially higher or lower over time. Instead of one static output from a ratio or model, they lay out the set of expectations that number rests on so you can watch how the real business tracks against those assumptions. These scenarios sit on Simply Wall St's Community page for you to explore alongside other investors.
One of the top community narratives on ZTO Express (Cayman): 28% undervalued
"The current valuation, including references to a forward P/E below logistics peers and a dividend yield of about 3.3%..."
Discover why this Narrative puts ZTO Express (Cayman) at 28% undervalued.
One more angle on ZTO Express (Cayman) that could change how you see today’s price
Everything so far has focused on what ZTO Express (Cayman) earns today, but professional research houses have their own timelines and expectations that you can weigh against this valuation. Explore where analysts expect ZTO Express (Cayman) to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com