
How Investors Are Reacting To Charter Communications (CHTR) Executive Role Change Ahead Of Earnings
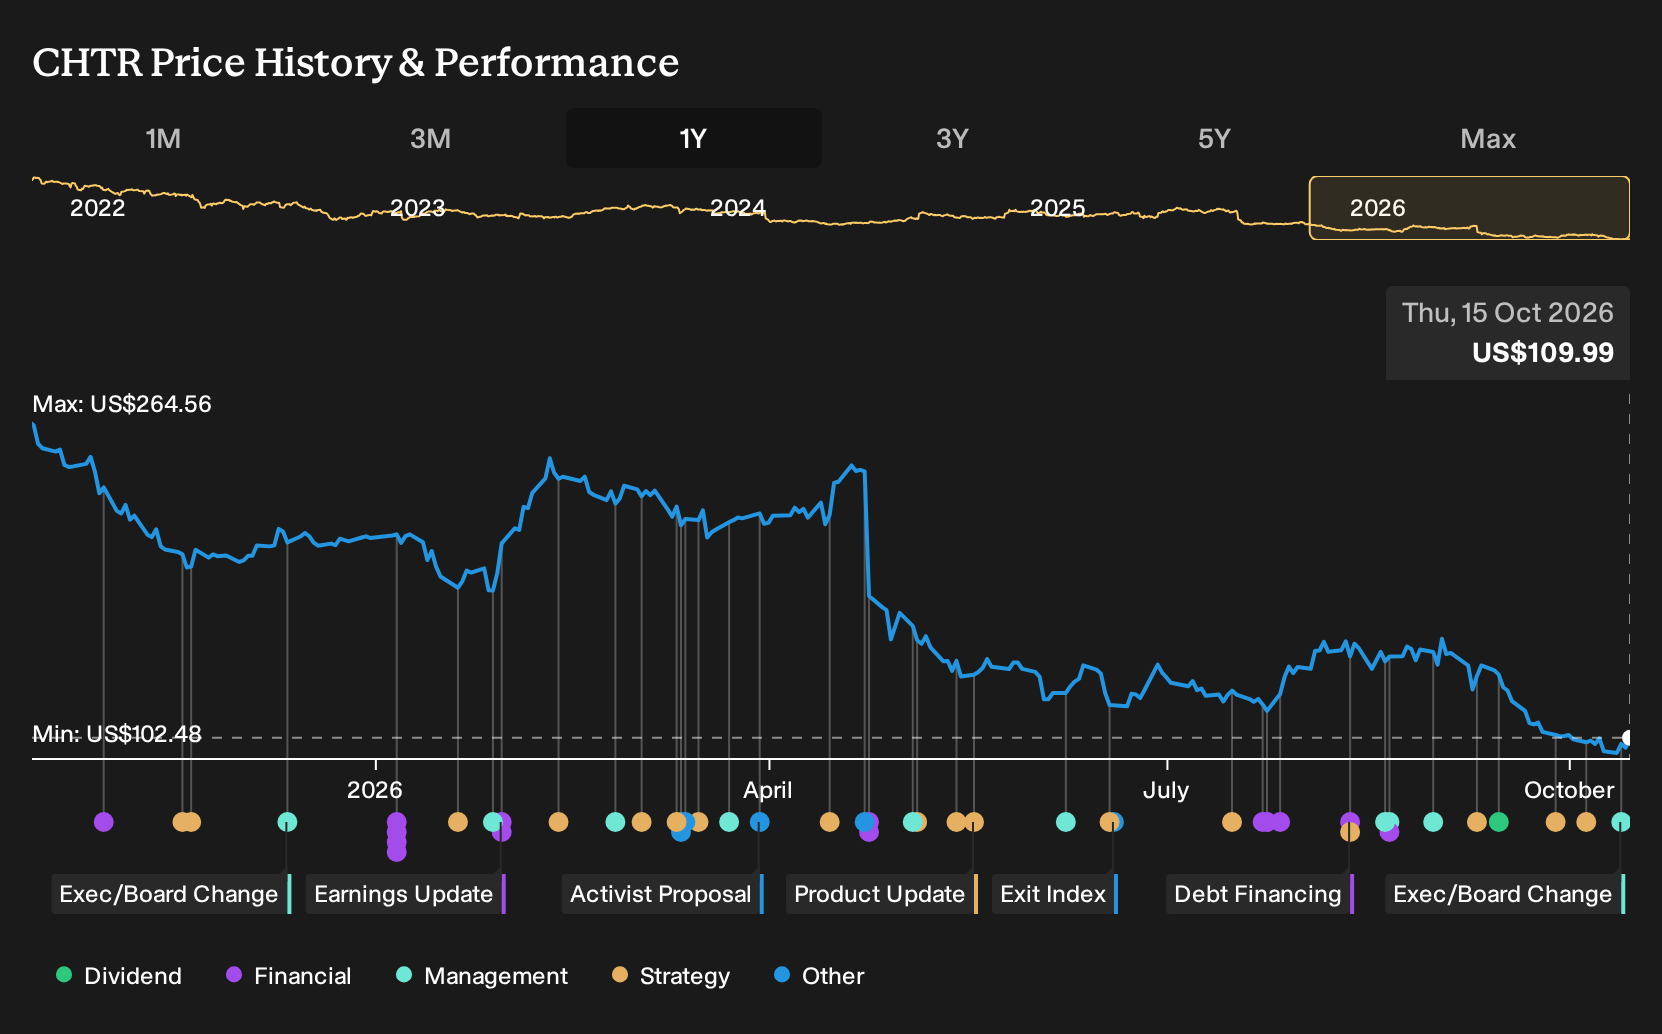
- Charter Communications recently renewed Adeia's multi-year intellectual property license for Spectrum's video, broadband and mobility services and confirmed that former Executive Vice President and Chief Commercial Officer Adam Ray moved into a non-executive advisory role in October 2026.
- The combination of a fresh IP agreement supporting Spectrum's product set and the shift in commercial leadership places greater emphasis on execution in broadband, mobile and video bundling for Charter Communications.
- This article examines how Charter Communications' investment narrative is shaped by the CCO transition as investors monitor the upcoming earnings release.
Scan how leadership and product shifts like Charter Communications' are playing out across other communications providers by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) in this space.
Charter Communications Investment Narrative Recap
To own Charter Communications, you need to believe the broadband, mobile and app based video bundle strategy can offset tougher internet competition and softer video trends. The near term swing factor is whether Q3 2026 results show any stabilisation in broadband losses and mobile additions while keeping revenue and EBITDA pressure in check.
The biggest risk remains continued erosion in internet subscribers as fixed wireless and fiber competitors press on, especially if the Affordable Connectivity Program support weakens. The recent CCO change and Adeia IP renewal do not fundamentally alter that risk. They mainly sharpen the focus on execution quality rather than change the thesis.
The Adeia IP renewal linked to Spectrum’s video, broadband and mobility services looks most relevant for your near term checklist. It gives Charter Communications clear rights to use key media and connectivity patents across its core bundle, which helps reduce operational friction just as it pushes converged offers harder.
For catalysts, having IP coverage across broadband and mobile matters because it supports product consistency as Cox integration, rural builds and the edge compute initiative progress. It does not solve subscriber churn or competition, but it removes one legal and technical variable while management works on pricing, packaging and customer retention.
Charter Communications' current analyst narrative points to revenues of US$63.5b and earnings of US$4.9b by 2029, based on a projected 5.3% annual revenue growth rate and flat earnings compared with the US$4.9b of earnings today. That 2029 estimate effectively implies no change in the earnings level even as the top line climbs.
Uncover why Charter Communications' fair value indicates a 57% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
Some analysts frame the bigger swing factor very differently. Rather than focusing on broadband churn, they worry that execution on Cox integration and edge AI stays uneven. The most bearish group came in expecting about US$66.5b of revenue and US$5.3b of earnings by 2029, yet still set a US$68 price target. Those forecasts and targets were all published before the Charter Communications leadership change and Adeia renewal, so you now have a clear opportunity to test how your own view might shift as the narrative gets refreshed.
Explore 6 other Charter Communications fair value estimates, including one that suggests as much as 38% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Charter Communications research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Charter Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charter Communications' overall financial health at a glance.
Looking for more Charter Communications investment ideas?
Once you have a handle on Charter Communications, it helps to widen the lens and compare it with other listed businesses that share some of the qualities you care about most. The Simply Wall St Screener can point you toward a few focused shortlists that match different risk and return preferences.
- If you want potential upside but still care about balance sheet strength, check out a 33 high quality undervalued stocks that pair financial resilience with attractive prices.
- For investors who put income first, scan a curated set of 8 dividend fortresses that aim to combine sizeable yields with sturdier fundamentals.
- When capital preservation sits higher on your list, start with a 32 resilient stocks with low risk scores that score well on financial health and volatility measures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com