
Southern Copper (SCCO) Stock Looks Above Fair Value Following Its 318% Run
Southern Copper has delivered striking share returns in recent years, which naturally puts a spotlight on whether the current price is still grounded in what the business earns. With the stock now trading around US$201.69, the key issue is how that level lines up with its underlying profitability.
- Over the past 5 years the stock has returned about 317.7%, which raises the question of how much of that performance can be linked back to sustainable earnings power.
- Recent copper market commentary points to shifting expectations for future prices and trade tariffs, which can feed into forecasts for Southern Copper's revenue potential and earnings resilience.
- There is a second opinion on Southern Copper worth weighing. See what analysts think Southern Copper's shares could be worth.
The issue now is whether Southern Copper's current share price is justified by the earnings that investors are effectively paying for today.
If you want more ideas at this end of the market while you think through Southern Copper's earnings picture, consider using a focused stock screen of 16 top copper producer stocks.
Has Southern Copper Run Too Far on Earnings?
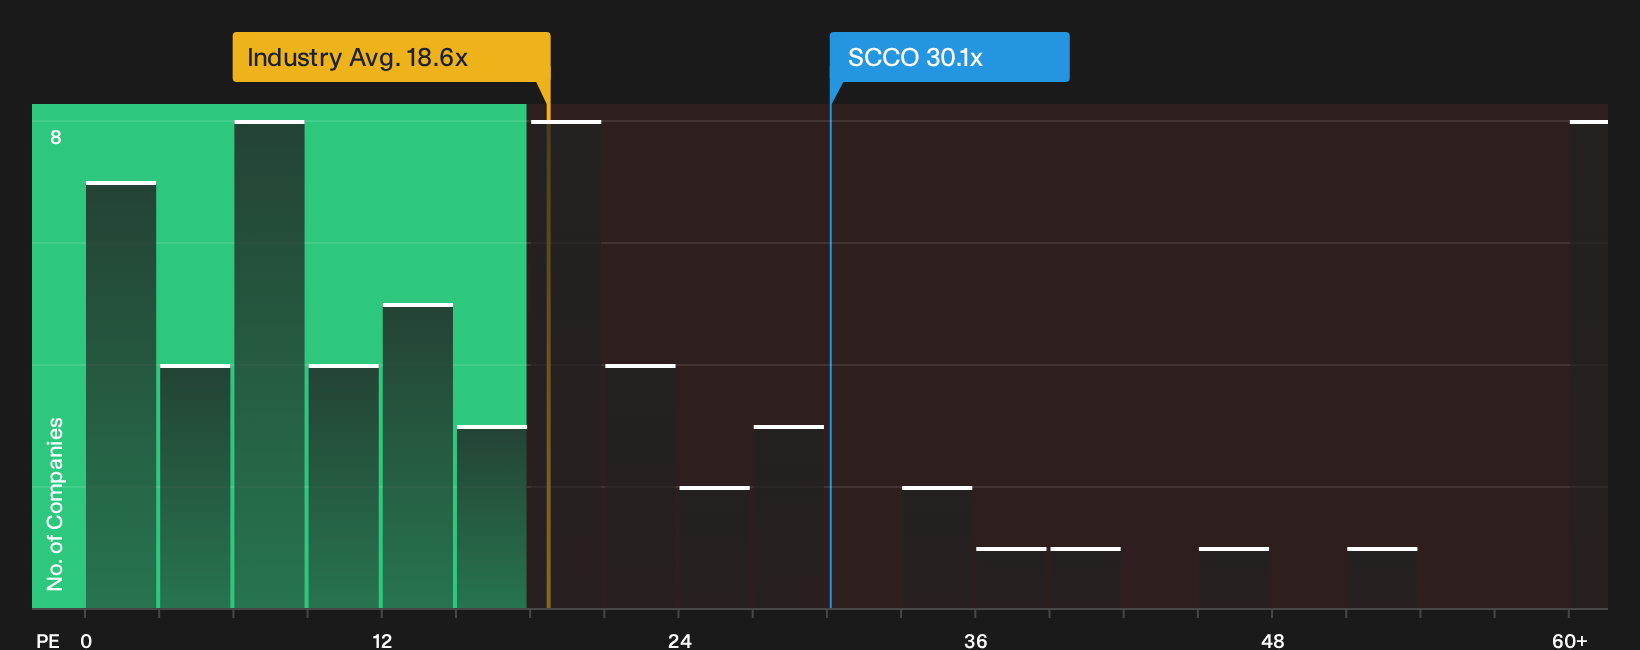
The P/E ratio works well for Southern Copper because earnings are central to how investors frame large, established miners. On this lens, the stock trades on about 30.1x earnings, compared with roughly 18.6x for the wider metals and mining sector and about 24.0x across closer peers. That points to investors paying a visibly richer price for each dollar of profit than is typical for similar businesses.
Because recent copper price forecasts have been lifted for 2026 even as tariff outcomes remain uncertain, the market seems willing to pay a premium multiple that already bakes in a fair amount of optimism. The current P/E sits above the level suggested by a tailored fair multiple that blends Southern Copper's scale, profitability profile and risk, so on this framework the shares screen as overvalued rather than discounted. Anyone considering the stock needs to judge whether the quality and durability of its earnings justify paying that kind of premium. Explore the numbers behind Southern Copper's P/E valuation.
The Southern Copper Narrative: What Would Justify Today's Price?
Narratives for Southern Copper pick up where the P/E puzzle leaves off, by spelling out which paths for future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than it is today. Rather than giving a single figure, they describe the future that figure relies on, so you can watch how Southern Copper's actual progress lines up. These are available within Simply Wall St's Community page for the company.
Community views on Southern Copper are split between cash flow driven upside and a belief that expectations already look full.
Bull case: 15% undervalued
"Record quarterly sales of US$4.3b and adjusted EBITDA of US$2.86b with a 67% margin in Q2 2026 give Southern Copper an internal cash generation base that could support a faster or larger self funded build out of its copper project pipeline than analysts currently assume…"
Discover why this Narrative puts Southern Copper at 15% undervalued.
Bear case: 15% overvalued
"Southern Copper is pursuing a capital investment program of more than US$20.5b across Peru and Mexico, and a bearish view is that current valuation already factors in the full revenue and earnings uplift from this spending even though the assets are still under construction and not yet generating matching cash flows…"
Explore why this Narrative puts Southern Copper at 15% overvalued.
Southern Copper's price is only one piece of the decision
Beyond where Southern Copper trades and how its earnings are valued, internal checks have flagged specific risk markers that investors may want to weigh carefully before committing fresh capital. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com