
Is Honeywell International (HON) Still Cheap After Its 46% Fall?
Honeywell International has seen its share price fall 46.3% year to date, which puts fresh focus on whether the current US$210.50 level lines up with what its earnings can reasonably support. With the stock still positive over the past year overall, you are effectively being asked to judge whether the recent slide or the longer track record should matter more for an earnings based valuation view.
- The year to date decline of 46.3% means any conclusion about Honeywell International now has a much bigger impact on long term return expectations than it did at the start of the year.
- The launch of Honeywell Forge Cognition, which applies AI tools from Nvidia and Dell Technologies to physical operations, can influence how investors think about the durability and timing of future earnings streams from the company's building and industrial businesses.
- The analysts covering Honeywell International have run their own numbers. See what analysts think Honeywell International's shares could be worth.
The issue now is whether Honeywell International's current share price is adequately supported by the earnings the business is generating today.
If you are weighing Honeywell International against other ways to gain exposure to this kind of AI and industrial theme, it can help to compare it with 91 robotics and automation stocks.
Is Honeywell International Still Cheap on Earnings?
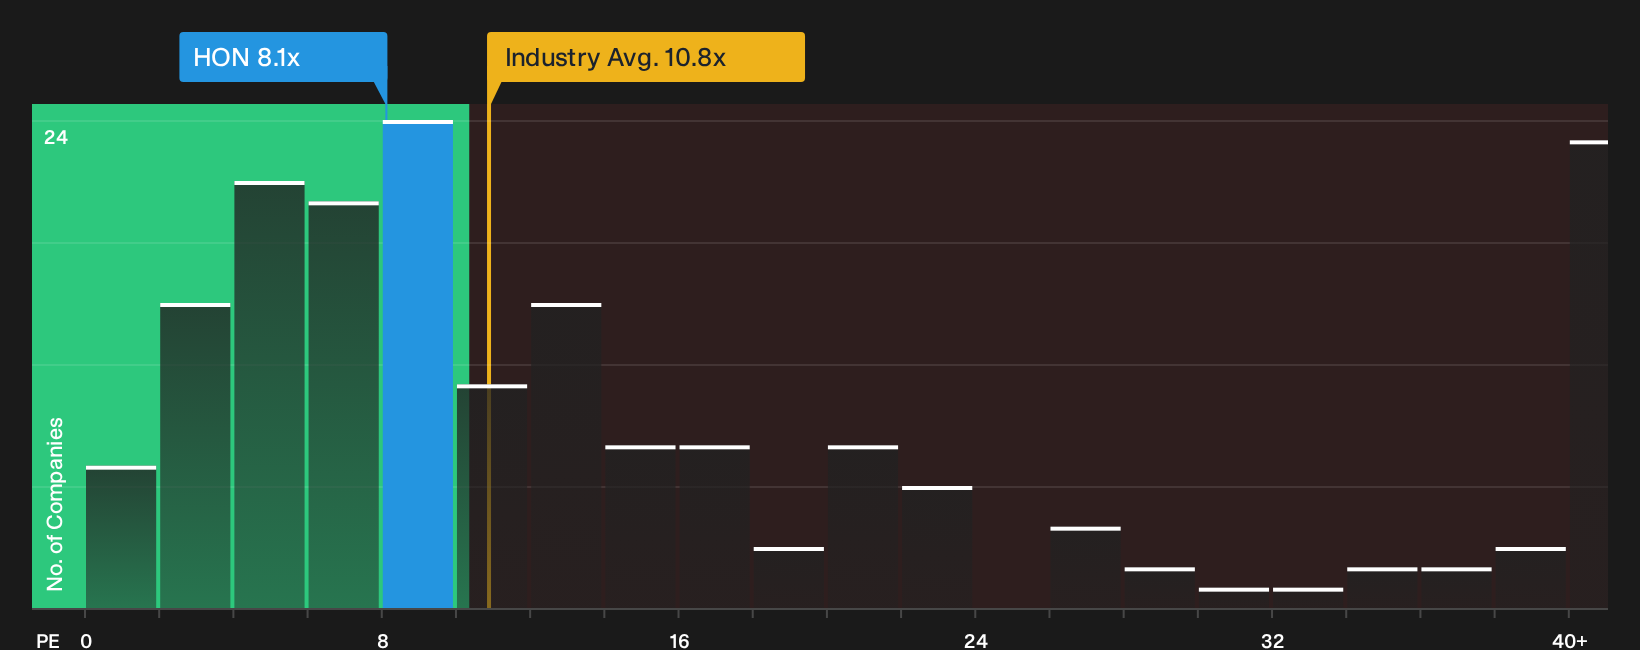
P/E works well for Honeywell International because earnings are a key focus for many investors in established industrial groups that also sell software and services. On this measure, Honeywell trades on a P/E of 8.1x, which is below the wider Industrials sector average of 10.8x and sits at a clear discount to peers around 32.3x. Against that backdrop, the stock currently prices in a lower earnings multiple than both the sector as a whole and a broad peer group.
The fair value model, which maps the P/E you might expect for Honeywell given its size, margins and risk profile, points to a higher ratio than where the shares trade today. Because the recent launch of Honeywell Forge Cognition ties the group more visibly to AI in physical operations, this gap suggests the market is not assigning the same earnings multiple as it does to comparable companies with similar exposure. The difference between the current P/E and this tailored benchmark is where potential upside or downside in the valuation debate sits for Honeywell International. Explore the numbers behind Honeywell International's P/E valuation.
The Honeywell International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Honeywell International leaves off by spelling out which assumptions on future growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each narrative treats Honeywell International's fair value as a thesis about the business that you can track over time, rather than a one off snapshot.
Community views on Honeywell International split between investors who see underappreciated automation and quantum exposure and others who think expectations already bake in a lot of good news.
Bull case: 34% undervalued
"Total RemainCo backlog: ~$19.4 billion in contracted future revenue. That is not a forecast. That is work already on the books…"
Discover why this Narrative puts Honeywell International at 34% undervalued.
Bear case: roughly fairly valued
"The current figures for organic growth, margin expansion, and earnings guidance suggest a share price that already reflects Honeywell International as a fairly valued pure-play automation company…"
Explore why this Narrative puts Honeywell International at roughly fairly valued.
One more Honeywell International check before you move on
Price multiples tell you what the market pays today, but the analyst models behind Honeywell International sketch where earnings and cash generation are projected to go over the next few years. Explore where analysts expect Honeywell International to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com