
How Raised Earnings Estimates At Lamb Weston Holdings (LW) Have Changed Its Investment Story
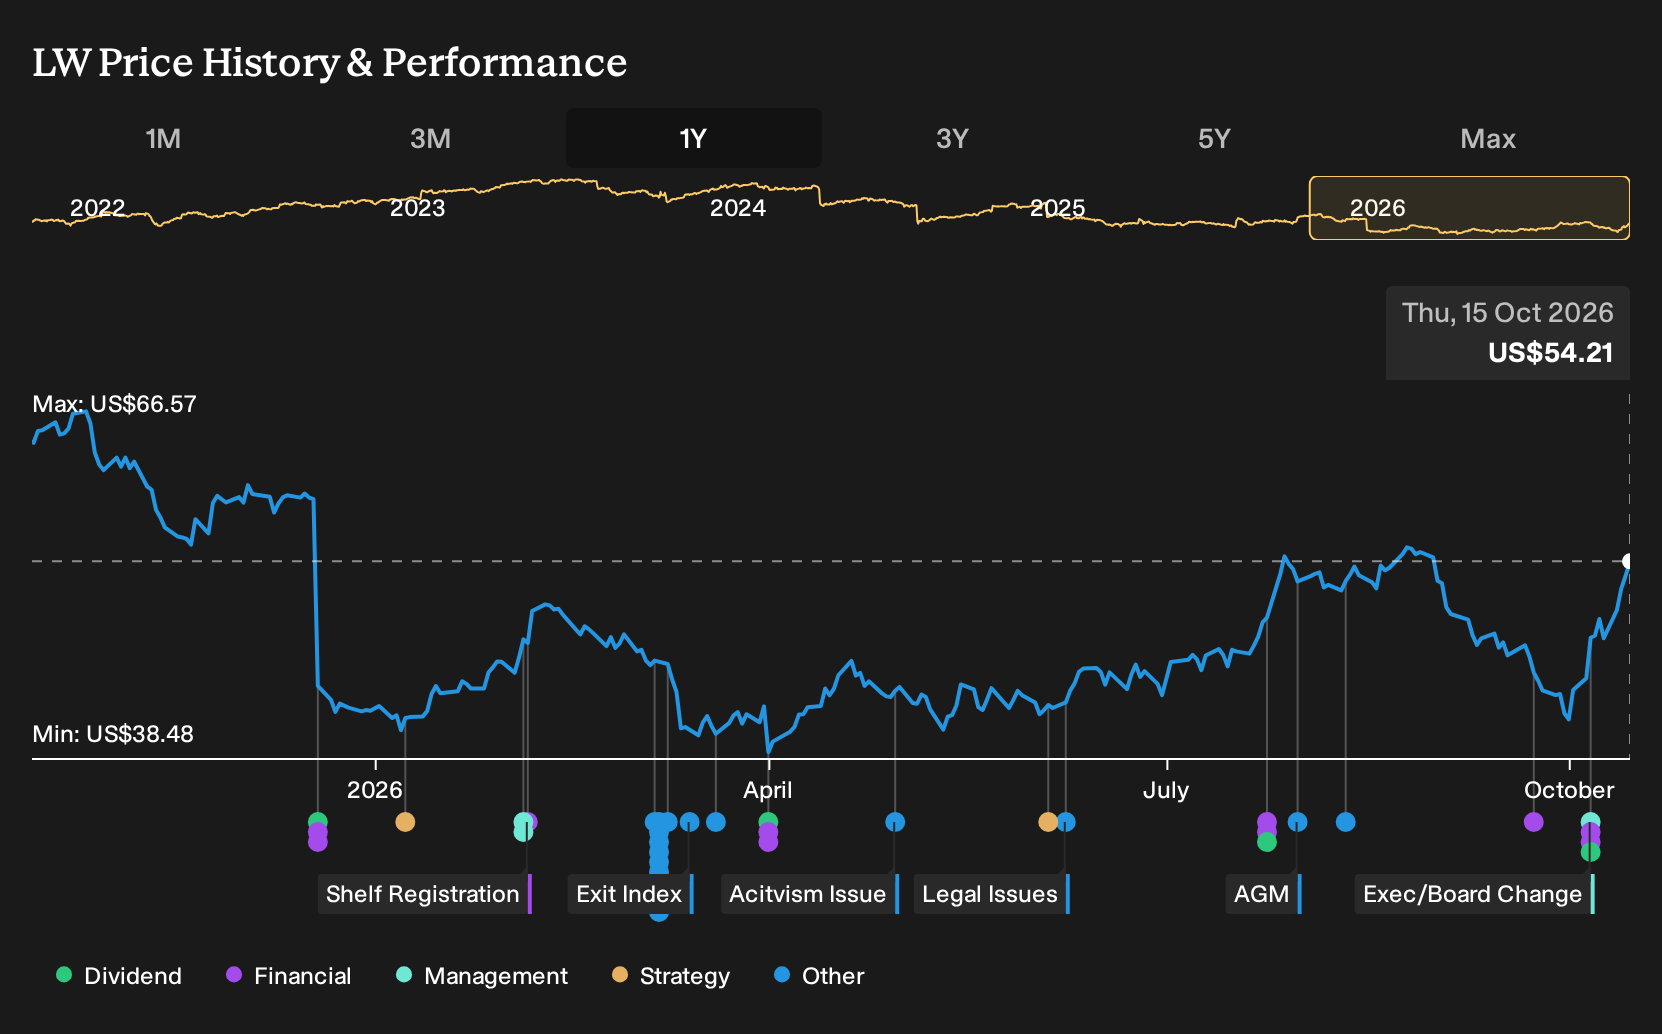
- Lamb Weston Holdings reported first quarter 2026 sales of US$1,670.3 million with net income of US$29.1 million and maintained its dividend at US$0.38 per share. Executive Marc Schroeder entered a phased transition from President, International into an advisory role through early 2027.
- The business completed a long running share repurchase program totaling 13,558,359 shares for US$880.51 million. Alongside updated guidance for low single digit net sales growth in fiscal 2027, this frames how Lamb Weston balances capital returns with a measured top line outlook.
- We will now look at how Lamb Weston’s investment narrative could be influenced by higher earnings estimates and a stronger analyst consensus.
Scan how Lamb Weston Holdings stacks up against other food producers returning cash to shareholders by reviewing our hand picked 8 dividend fortresses in similar income focused segments.
Lamb Weston Holdings Investment Narrative Recap
To own Lamb Weston Holdings, you need to be comfortable with a frozen potato business where North America remains the earnings anchor while international operations recover from a weaker base. The immediate focus is on stabilizing profitability after first quarter 2026 net income of US$29.1 million and compressed earnings per share, with cost inflation and ERP issues still hanging over margins.
The key short term catalyst is execution on cost savings and international restructuring so EBITDA from outside North America can better support group earnings. The biggest risk remains pressure on overseas volumes and input costs, and the latest quarterly figures and guidance tweaks do not radically change that near term equation.
The guidance update for fiscal 2027, pointing to low single digit net sales growth, is the announcement that ties most directly to today’s debate. It sets expectations that Lamb Weston Holdings is aiming for measured top line progress while it leans on operational efficiency programs and a North American base that already carries a large share of profits.
For you as a shareholder, that backdrop puts even more weight on catalysts like the US$250 million run rate cost savings target, ERP stabilization, and better utilization in the reset European network. Execution there may matter more than modest revenue growth, given risks from cost inflation, elevated debt and the recent step down in quarterly earnings.
What The Current Analyst Framework Implies
Analysts looking at Lamb Weston Holdings are effectively underwriting a frozen potato business that leans more on margin repair than on rapid expansion. Revenue is expected to stay roughly flat over the next 3 years, so the heavy lifting in most models comes from profit margins moving from 4.4% today to 7.5% by around 2029.
The earnings bridge is clear enough on paper. Consensus points to earnings rising from US$290.0 million today to US$506.8 million by 2029, with some forecasts going as high as US$575.0 million. That implies earnings would need to increase by about US$216.8 million from the current level for the central estimate to play out, helped by both higher margins and a gradual 1.34% yearly decline in the share count.
On those assumptions, the analyst framework works off a P/E of 17.7x applied to the 2029 earnings estimate. This compares with 22.1x today and a current sector multiple of 17.3x for US food stocks. Put differently, the story many models tell is that Lamb Weston Holdings grows into its valuation through better profitability while accepting only modest help from the top line.
For a holder of the shares, that mix of flat revenue assumptions and higher earnings forecasts raises a simple question. You need to judge whether cost savings, ERP stabilization and the international restructuring plan can reasonably support a shift to mid single digit net margins while non potato inputs are expected to add around 3% to the cost base in fiscal 2027.
Lamb Weston Holdings' narrative projects US$6.8b revenue and US$506.8 million earnings by 2029. This requires fairly flat yearly revenue growth and an earnings increase of about US$216.8 million from US$290.0 million today.
Uncover why Lamb Weston Holdings' fair value indicates a valuation gap that is approximately aligned with its current price.
Exploring Other Perspectives
One alternate story focuses on Lamb Weston Holdings using cost discipline as a springboard rather than a repair tool. Before this latest quarter and the leadership transition news, the most optimistic analysts were penciling in US$7.1b revenue and US$584.2 million earnings by 2029. That is far above consensus, and those forecasts might shift once this new information settles in. Treat them as one of several viewpoints to weigh rather than a script you must follow.
Explore 5 other Lamb Weston Holdings fair value estimates, including one that suggests as much as 155% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lamb Weston Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lamb Weston Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Lamb Weston Holdings' overall financial health at a glance.
Looking for more Lamb Weston Holdings style investment ideas?
If Lamb Weston Holdings has sparked your interest in income, quality and capital allocation, it can be useful to widen the lens and compare it with other businesses that fit different parts of your checklist.
- For investors who want potential value with quality fundamentals, scan our 33 high quality undervalued stocks to find companies that combine strong balance sheets with attractive pricing signals.
- If capital preservation sits high on your list, review a 32 resilient stocks with low risk scores that highlights companies scoring well on financial strength and lower risk metrics.
- When you want to get ahead of the crowd, search through a 20 high quality undiscovered gems focusing on companies that pair solid cash generation with under-the-radar profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com