
Alm. Brand (CPSE:ALMB) Guidance Upgrade Puts Valuation Back In Focus
Alm. Brand guidance upgrade puts 2026 earnings in sharper focus
Alm. Brand (CPSE:ALMB) raised its 2026 earnings guidance after a favourable third quarter, lifting the expected insurance service result by DKK 250 million to DKK 1.5-1.6 billion.
The updated outlook, which excludes potential run offs in the fourth quarter of 2026, gives investors a clearer view of how management currently sees the insurance business performing into the end of the year.
Recent trading suggests the updated guidance has started to shift sentiment around Alm. Brand. The share price is up 5.52% over the past week but still shows an 8.55% year to date decline, while the 3 year total shareholder return of 87.92% points to a much stronger longer term record.
Scan other insurance stocks where upgraded outlooks and resilient earnings profiles have helped define 225 resilient stocks with low risk scores as potential candidates for steadier compounding alongside Alm. Brand.
The recent uptick in Alm. Brand appears tied to upgraded guidance rather than a full reset in market mood. The key question is whether the current valuation already reflects that stronger earnings profile.
Most Popular Narrative: 14% Undervalued
On the most followed narrative, Alm. Brand is viewed as undervalued, with a fair value of DKK19.70 against the last close at DKK17.01. This puts the upgraded 2026 guidance into a wider multi year earnings story shaped by capital returns and margin assumptions.
Successful synergy initiatives have already exceeded targets in 2024, with expectations to reach DKK 600 million in 2025. This operational efficiency is likely to boost earnings and improve cost structures.
See why 10 investors see Alm. Brand as 14% undervalued.
Result: Fair Value of DKK19.70 (UNDERVALUED)
Still, Alm. Brand’s high payout ratio, combined with intense competition in Danish non life insurance, could pressure reinvestment capacity and test the current undervaluation thesis.
Find out about the key risks to this Alm. Brand narrative.
Another View: Alm. Brand on earnings multiples
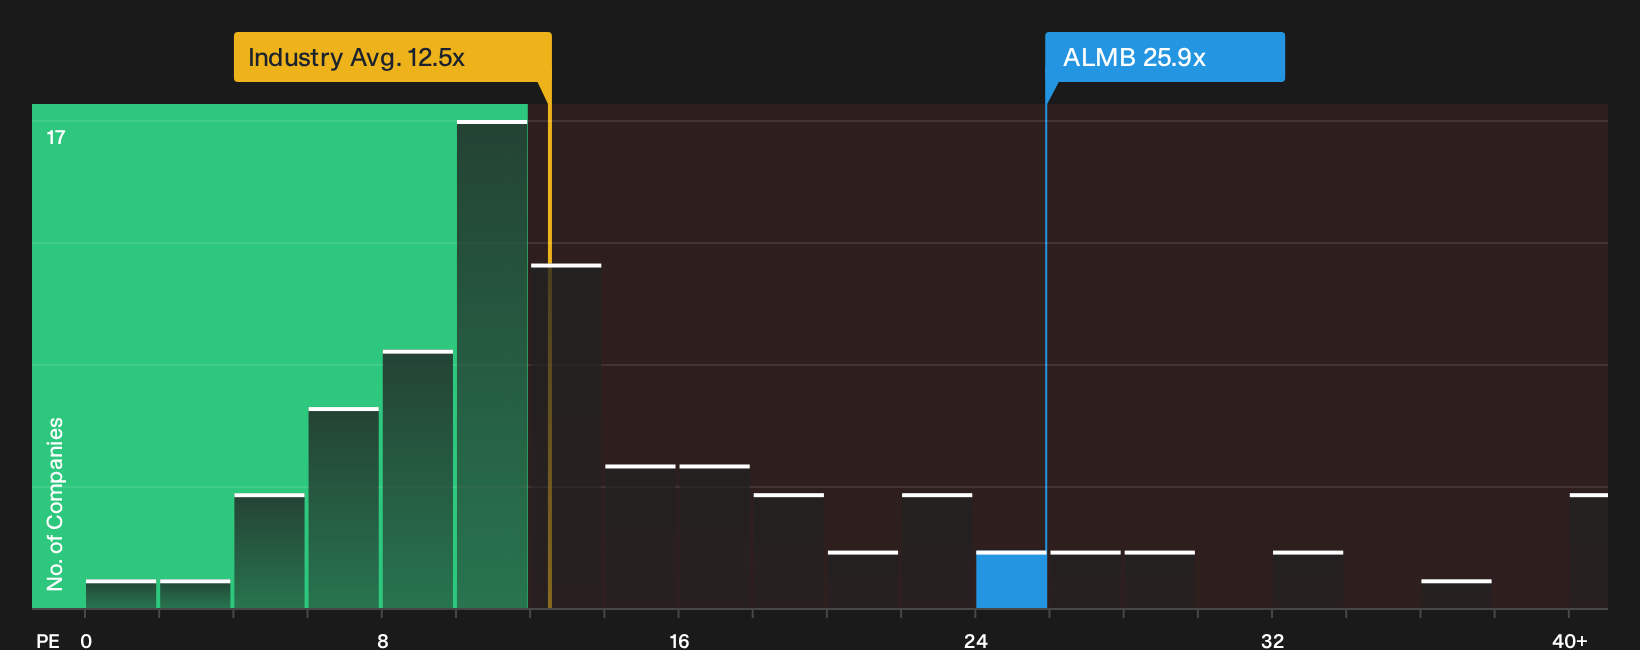
There is a very different picture when Alm. Brand is looked at through its P/E. The shares trade on 25.9x earnings compared with 12.5x for the European insurance sector and a fair ratio estimate of 24.9x, which points to far less room for error than the DKK fair value gap suggests.
For anyone weighing that richer earnings multiple against the wider story around payout, competition and reinvestment, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment clearly split between valuation optimism and competitive pressures, move quickly and pull up the numbers for Alm. Brand to pressure test the story yourself using 2 key rewards and 2 important warning signs.
Looking for more Alm. Brand sized investment ideas?
If Alm. Brand has sharpened your thinking, now is the moment to widen your watchlist before the next set of opportunities runs ahead of you.
- Target resilience by scanning companies that combine lower risk profiles with sturdier fundamentals through the 225 resilient stocks with low risk scores.
- Prioritise quality at a reasonable price by using the 198 high quality undervalued stocks to focus on businesses that pair solid cash generation with attractive valuations.
- Harness the power of compounding income by reviewing the 219 dividend fortresses to spot higher yielding payers with more robust balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com