
3 UK Stocks That Could Benefit If Brexit Trade Frictions Ease
Brexit is back on the table, but this time the story is about what happens if the UK and EU move closer together rather than further apart. Shifts in trade rules, taxes and labour access could change the fortunes of domestically focused UK stocks, creating opportunities and risks that many portfolios still ignore. This article walks through three UK listed shares exposed to this news backdrop and explains how each might be affected.
The three shares below are only a starter set, and the full screen surfaced 23 more UK focused companies with similarly detailed backstories that this article does not cover.
To go straight to the wider opportunity set, use the UK Domestic-Focused Equities Benefiting from Improved EU Trade Relations screener to identify, analyze and prioritise the ideas that best match your own conviction and risk appetite.
Breedon Group (LSE:BREE)
Breedon Group is one of the purest UK construction materials plays in this screen, with a heavy tilt toward Great Britain and Ireland and a business tied directly to roads, housing and infrastructure that could respond quickly if closer EU ties lift domestic confidence.
Breedon Group runs quarries and plants supplying cement, aggregates, asphalt and ready mixed concrete across Great Britain, Ireland and the U.S., with about £1.1b from Great Britain, £308 million from Ireland and £341 million from the U.S., and a market value around £1.1b.
"Although the U.S. platform now accounts for almost 20% of group revenue and benefits from resilient infrastructure spend, earnings are exposed to weather disruption and seasonal second half weighting in the Midwest."
What really matters for investors is how one quiet shift in UK policy and cost support could ripple through Breedon Group’s pricing power.
That pricing question sits at the heart of the story, and the full narrative for Breedon Group shows how Breedon Group could see that power accelerate or stall as policies shift.

Marshalls (LSE:MSLH)
Marshalls plugs straight into the screener theme because it sells the paving, building and roofing products that UK projects actually use. Any lift in domestic construction sentiment from smoother UK EU trade flows through to its order book far more directly than most.
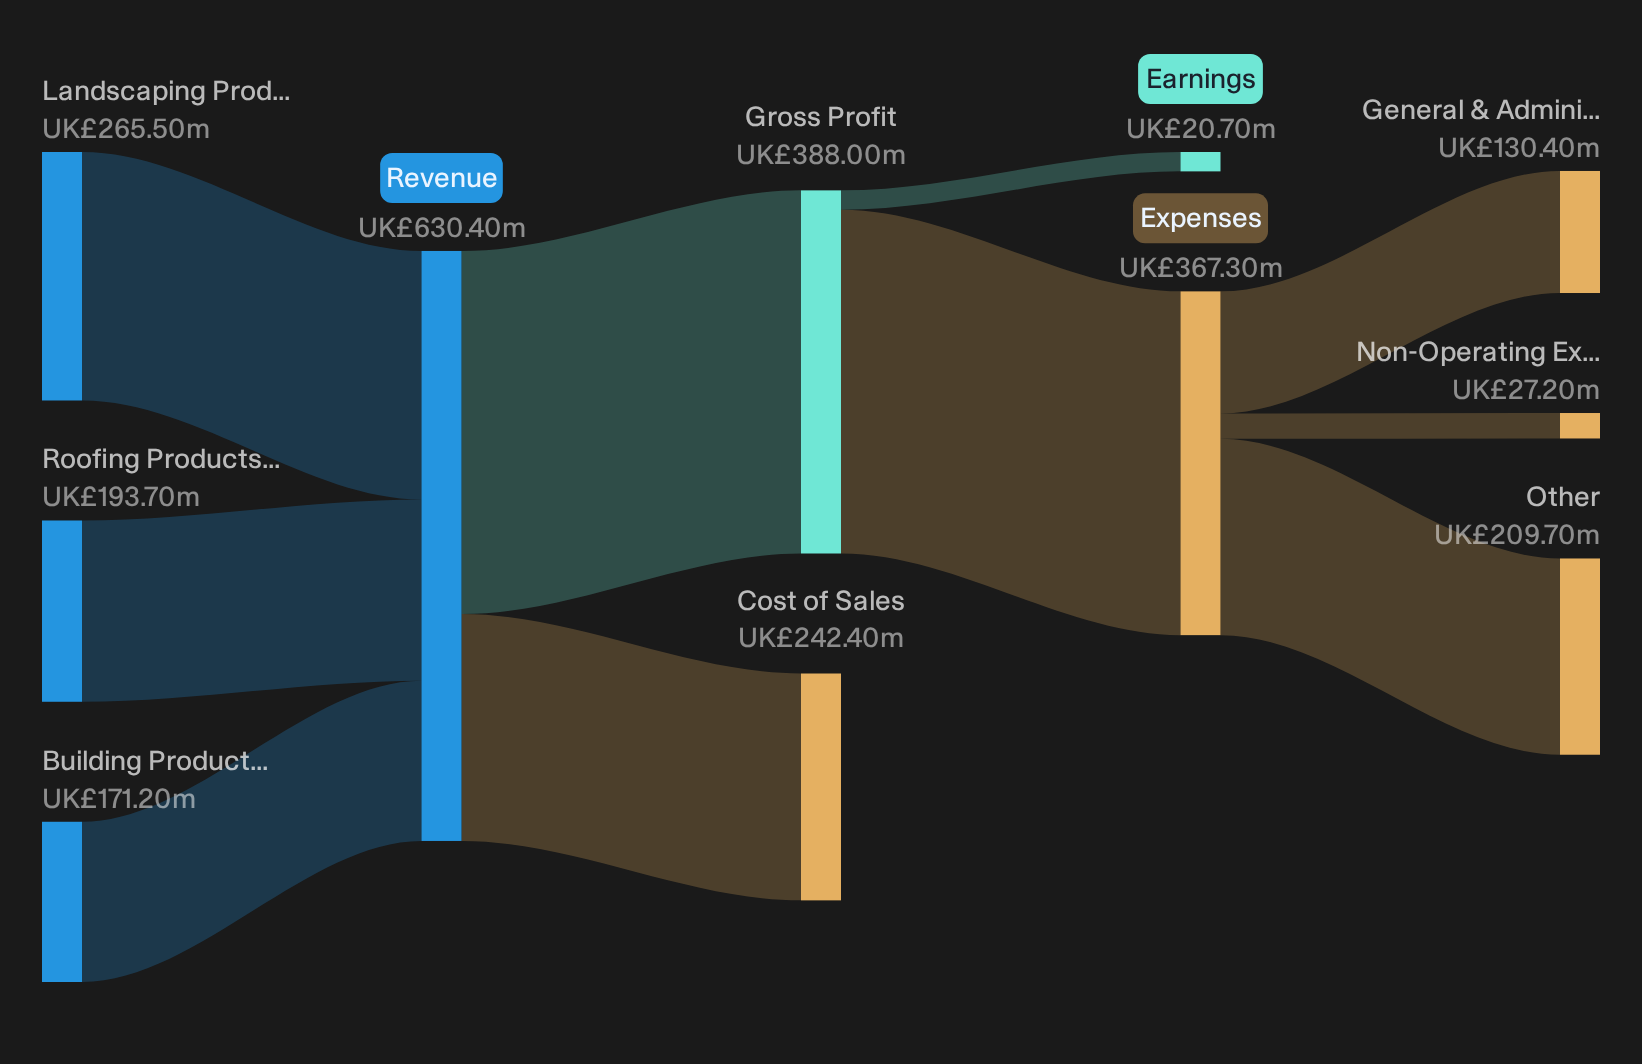
Marshalls manufactures a wide range of paving, building and roofing materials for homes, commercial sites and infrastructure, with £265.5 million from Landscaping Products, £193.7 million from Roofing Products and £171.2 million from Building Products, and a market value of about £434 million.
"AMP8 related sales in Water Management more than doubled year-on-year in H1 2026, and framework agreements are now in place with three UK water utilities. These indicate that early project conversions may scale into a longer pipeline that supports higher infrastructure revenue and steadier operating profit."
What really shapes the Marshalls story now is how one quiet shift in where future demand comes from could feed through to margins and cash generation.
That shift in demand mix is exactly what the full narrative for Marshalls unpacks, showing where Marshalls’ earnings power could be quietly accelerating or at risk of stalling next.
AO World (LSE:AO.)
AO World is a pure UK online appliance retailer in this screener, with EU trade frictions directly influencing its import costs, delivery reliability and the confidence of the households it sells to.
AO World runs online retailing of domestic appliances and related services that produced about £1.27b of revenue, and the stock carries a market value close to £512 million.
"While AO World is growing B2C revenue and has strengthened its balance sheet with net funds and over £200m of available liquidity, the company remains highly exposed to U.K. specific wage and regulatory changes."
What happens if one key cost pressure eases just as those efficiency and membership engines start to bite could matter a lot for future margins.
That kind of cost swing is exactly what the full narrative for AO World breaks down, revealing where AO World’s earnings power could be quietly accelerating or still masking risk.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first, and latecomers get caught chasing breakout moves after the best entry points are dropping out of reach. Scan under the radar for now and act early.
- Spot reliable income engines early and track 4 dividend fortresses before yields and prices move out of your comfort zone.
- Hunt for sturdy balance sheets while they are still ignored by the crowd with the list of solid balance sheet and fundamentals (9 results).
- Target future-facing AI infrastructure leaders and sift through 94 AI infrastructure stocks before momentum sends valuations higher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com