
Cerebras Systems (CBRS) Stock Looks Priced For Perfection Even After The Slide
Cerebras Systems has dropped sharply since its May listing, and the slide has turned attention away from the IPO headlines and toward a simpler question: at today’s price, is the stock still asking too much of its sales, or not enough?
- The share price is down 54.3% year to date, which puts intense focus on whether the current market value is still stretching its sales base or now reflects more muted expectations.
- Fresh commitments from partners like OpenAI and Jane Street underline that big customers are prepared to pay for Cerebras Systems’ AI compute capacity, which can shape how quickly reported revenue catches up with the story investors are paying for.
- Your read on Cerebras Systems is one view; the desks covering it have another. See what analysts think Cerebras Systems's shares could be worth.
The issue now is whether Cerebras Systems’ current share price is adequately supported by its sales when lined up against the industry average.
If this drop in Cerebras Systems has you questioning what you pay for each dollar of AI-focused sales, it can help to compare that same question across 94 AI infrastructure stocks.
Has Cerebras Systems Run Too Far on Sales?
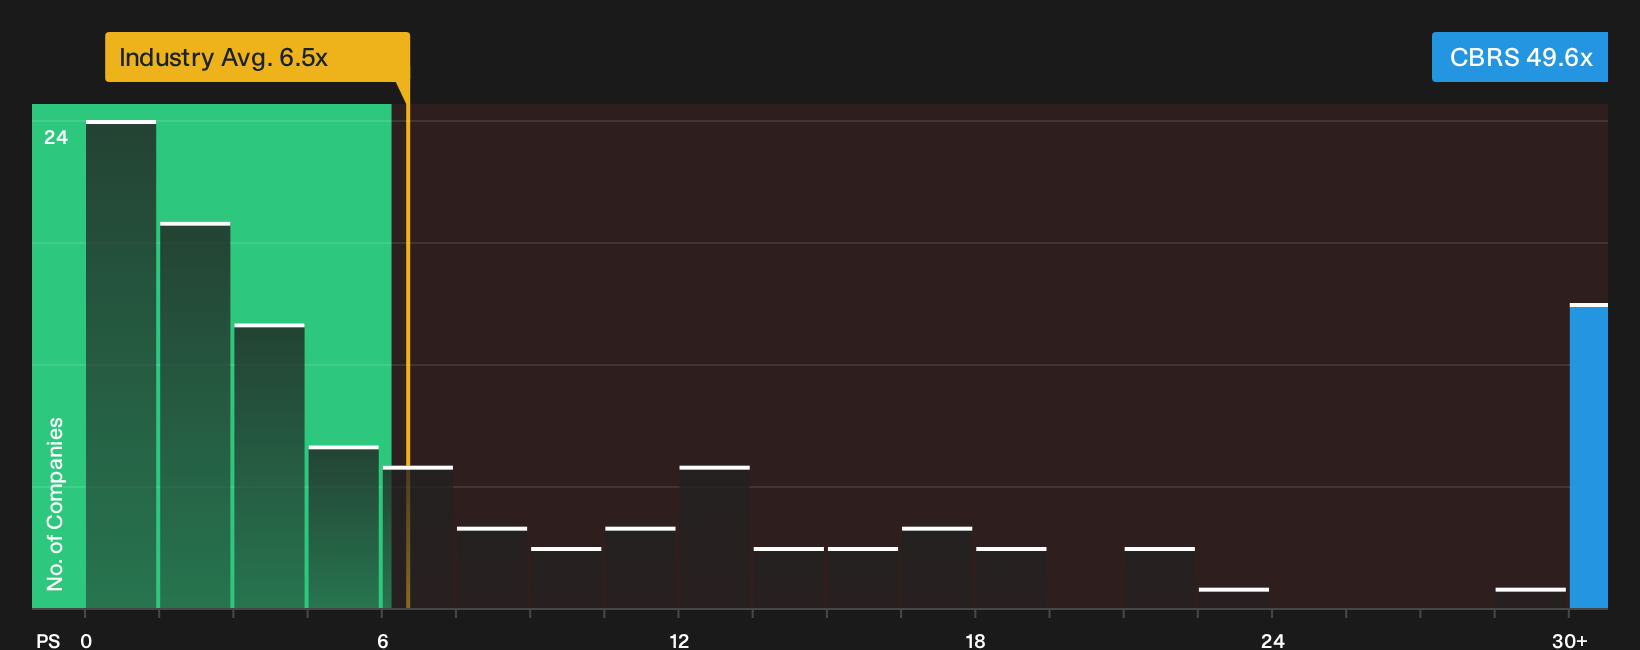
P/S fits Cerebras Systems because investors are focused on what they pay for each dollar of AI infrastructure revenue rather than current profits. On that yardstick, the stock changes hands at about 49.6x trailing sales, which is far above the semiconductor industry average of 6.5x and well above a peer group closer to 9.4x.
That gap means Cerebras Systems screens as heavily overvalued on simple P/S math, and the extreme premium suggests markets are placing a rich price on its contracts and AI compute narrative. Despite the OpenAI and Jane Street deals giving more substance to that story, the current multiple still asks you to pay many times the industry rate for each dollar of turnover, so you need a high level of confidence in how that sales base develops for the valuation to feel comfortable. Explore the numbers behind Cerebras Systems's P/S valuation.
The Cerebras Systems Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where the Cerebras Systems valuation puzzle leaves off by spelling out which revenue, margin and earnings paths would need to play out for the stock to look materially more expensive or cheaper than today's price. Each narrative ties a fair value range to a particular mix of potential catalysts and downside risks, so you can see over time which version of Cerebras Systems' story appears to be taking shape on the Community page.
One of the top community narratives on Cerebras Systems: 66% undervalued
"Cerebras entered the public markets with a staggering $24.6 billion in Remaining Performance Obligations (RPO)..."
Discover why this Narrative puts Cerebras Systems at 66% undervalued.
One more Cerebras Systems check that belongs beside the price tag
After lining up Cerebras Systems against its current sales, the missing angle is how professional analysts sketch this business a few years from now and how that picture compares with today's valuation. Explore where analysts expect Cerebras Systems to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com