
FDA Approval Might Change The Case For Investing In Novartis (SWX:NOVN)
- Novartis reported that the FDA approved Rhapsido (remibrutinib) as the first oral BTKi for adults with chronic spontaneous urticaria and symptomatic dermographism that are not controlled by H1 antihistamines, based on Phase III RemIND data showing higher complete hive response versus placebo and a consistent safety profile through Week 24.
- The same molecule is now supported by late stage REMODEL-1 and REMODEL-2 results in relapsing multiple sclerosis, giving Novartis a single asset with regulatory validation in chronic hives and late stage evidence in neurology, where the group already has an established Kesimpta franchise.
- We will now look at how Novartis' investment narrative could be reshaped by remibrutinib's dual chronic hives approval and MS data.
Novartis Investment Narrative Recap
For Novartis, the core belief as a shareholder is that a focused prescription medicines portfolio, a broad late stage pipeline and tight cost control can offset patent expiries and pricing pressure over time. The Rhapsido approval in chronic hives fits this story, adding a differentiated immunology product while the group continues to lean on Kisqali, Kesimpta, Pluvicto and others for momentum.
In the near term, the key swing factor is how efficiently Novartis converts late stage assets into real world prescriptions before major loss of exclusivity becomes a factor. Pricing pressure in the United States, China and Europe remains the biggest operational risk. The latest Rhapsido news looks supportive but not transformational for that immediate risk balance.
The most relevant recent announcement is the FDA approval of Rhapsido for both chronic spontaneous urticaria and symptomatic dermographism when antihistamines are not enough. Investors now see remibrutinib as a commercial product in immunology, not only a development story, which can matter when pipeline execution is a significant part of the Novartis thesis.
The same molecule now has positive Phase III REMODEL data in relapsing multiple sclerosis, presented at MSToronto2026, which sits alongside the existing Kesimpta franchise in neurology. This dual track program highlights how execution on one asset can touch several of Novartis’ stated catalysts, while still carrying the usual late stage regulatory and reimbursement risks.
Novartis' current analyst narrative points to revenues of $66.9b and earnings of $18.4b by 2029, based on an annual revenue growth assumption of 5.7% and an earnings step up of about $5.6b from $12.8b today.
Uncover why Novartis' fair value is viewed as broadly in line with its current price.
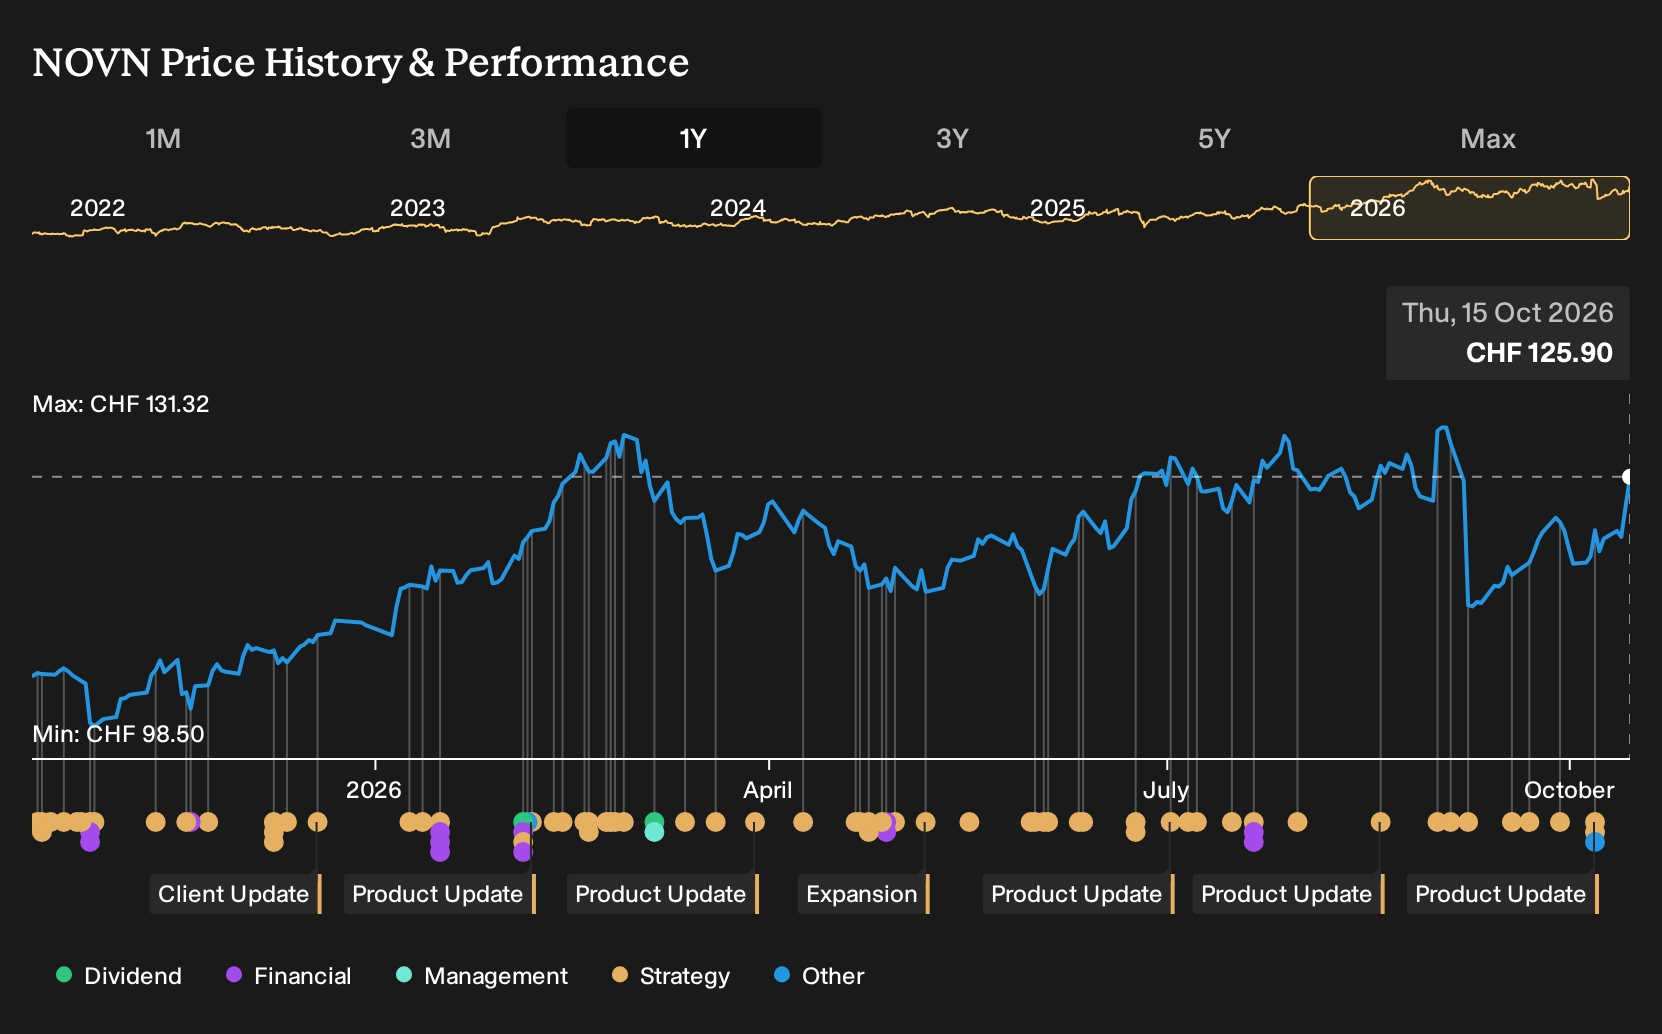
Exploring Other Perspectives
One alternate view puts far more weight on remibrutinib as a long term growth engine for Novartis. The most optimistic analysts were already pencilling in revenue of about $74.3b and earnings of $21.7b by 2029 before this news. You can see how opinions differ widely and why fresh data may shift those forecasts.
Explore 3 other Novartis fair value estimates, including one that suggests as much as 159% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Novartis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Novartis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novartis' overall financial health at a glance.
Looking for more investment ideas beyond Novartis?
If the Novartis story has sharpened your thinking, you can use that momentum to scan a wider universe of opportunities with the Simply Wall St Screener and build a watchlist that reflects your own risk and income preferences.
- If capital preservation is front of mind, you could start with a group of companies that score well on resilience and risk, then review the 225 resilient stocks with low risk scores for candidates that may suit a steadier approach.
- If you care most about financial strength, you might focus on businesses with cleaner balance sheets and healthier fundamentals by working through the list of solid balance sheet and fundamentals (202 results) to identify which ones merit a closer look.
- If you prefer looking for potentially mispriced quality, you can use the screener to search for companies that combine solid fundamentals with possible valuation gaps, beginning with the 350 high quality undiscovered gems as a source of ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com