
Does Rapid Rewards Overhaul Change The Bull Case For Southwest Airlines (LUV)?
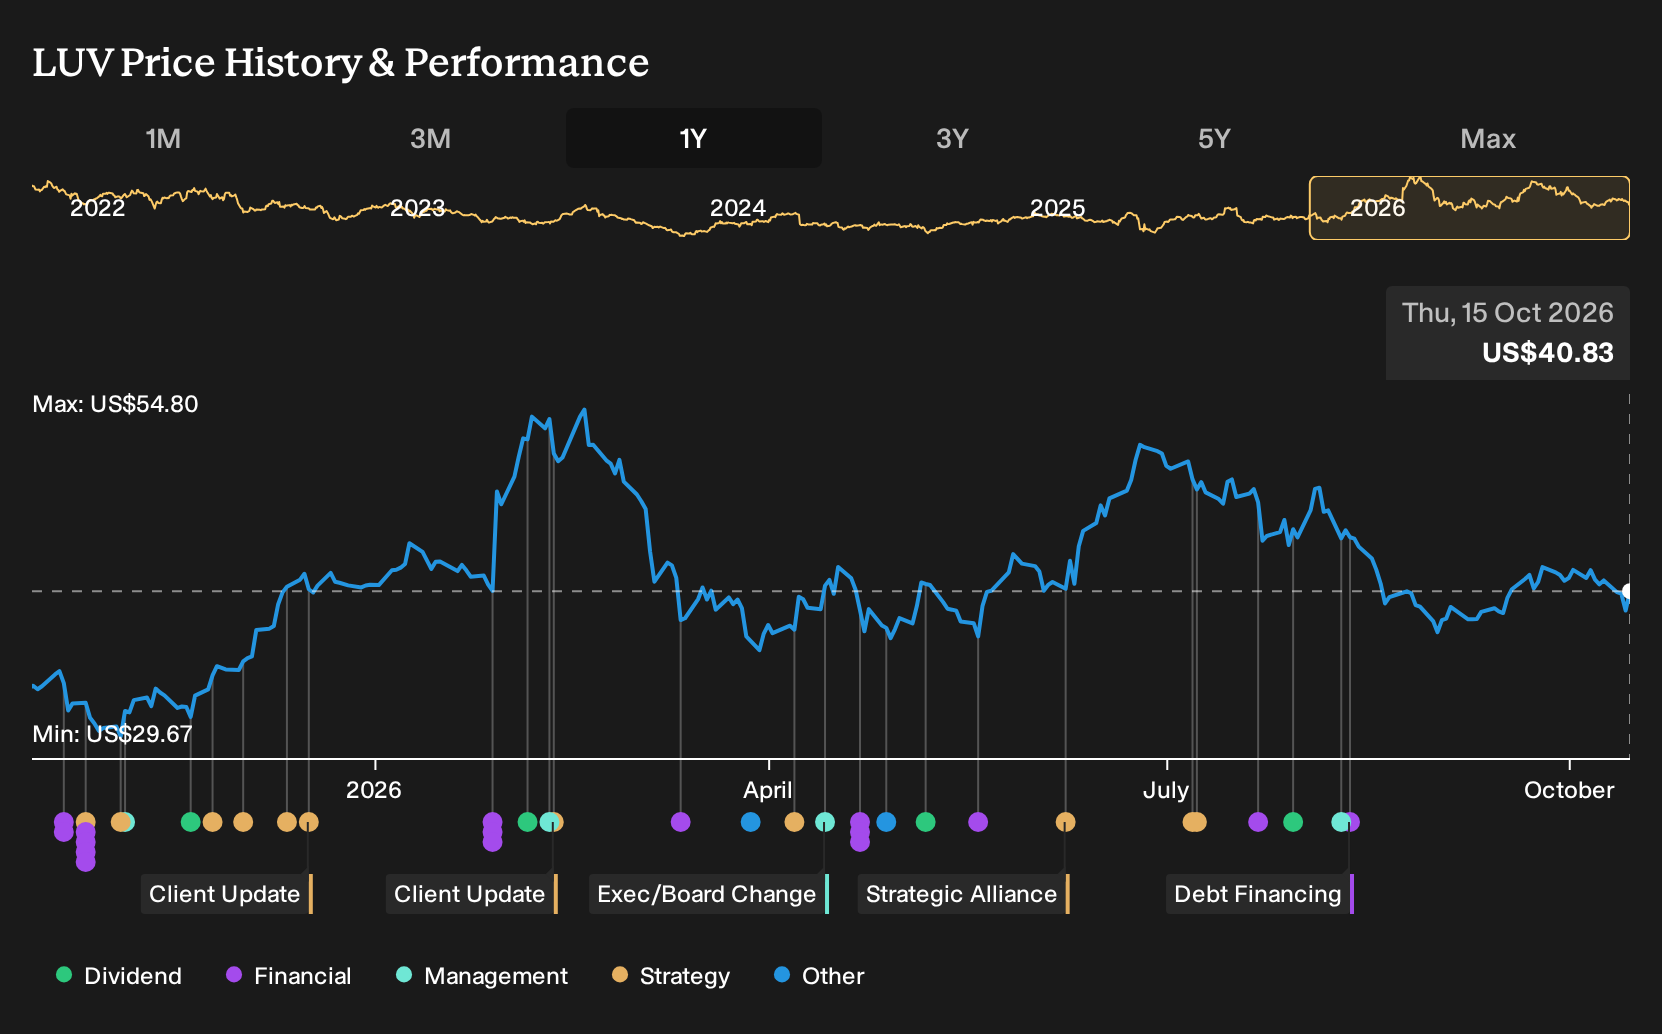
- Southwest Airlines recently outlined major changes to its Rapid Rewards program, including new Silver, Gold and Platinum tiers, expanded redemption options, a planned Nashville premium lounge tied to Chase credit cards, and a larger presence at Hollywood Burbank after opening a new terminal serving Honolulu traffic.
- The push into premium lounges, higher loyalty tiers and expanded Hawaii connectivity points to Southwest Airlines focusing more on higher value travelers and non ticket revenue streams, while still building around its core US network.
- We will look at how Southwest Airlines' investment narrative is affected by the richer Rapid Rewards tiers and premium lounge rollout.
Spot opportunities that follow the same premium travel and loyalty trend as Southwest Airlines by scanning our curated list of 20 high quality undiscovered gems in the wider airline and travel ecosystem.
Southwest Airlines Investment Narrative Recap
For a shareholder in Southwest Airlines, the core belief is that a higher margin commercial model can offset an industry that is still heavily exposed to fuel swings and operational shocks. The short term swing factor remains whether higher jet fuel, which already led to trimmed 2026 capacity growth and lower EPS guidance, stabilizes enough for cost savings and product changes to show through.
The biggest operational risk is that fuel stays elevated while reputational issues resurface, which could pressure revenue and confidence at the same time. Recent Rapid Rewards upgrades and lounge plans do not materially change that near term equation, although they point to more diversified loyalty and card income over time if execution holds.
The most relevant fresh announcement for this story is the Rapid Rewards overhaul with new Silver, Gold and Platinum tiers, plus expanded redemption choices. For you as an investor, the key question is whether Southwest Airlines can turn those richer tiers into higher engagement at acceptable customer acquisition costs, especially through its co branded Chase cards.
If loyalty and lounge access, including the planned Nashville Icon Lounge tied to new cards, drive more durable premium behavior, that could support the existing catalysts around yield management and ancillary revenue. Execution risk sits in the background. Management has to roll out these changes cleanly while containing costs and keeping operations reliable during peak travel periods.
Southwest Airlines' current analyst storyline points to revenues of US$35.8b and earnings of US$2.6b by 2029, based on 6.0% yearly revenue growth and an earnings increase of about US$1.8b from US$837.0m today.
Discover why Southwest Airlines' fair value indicates a 21% potential upside to its current price before the discount closes.
Exploring Other Perspectives
One alternate view focuses on fuel rather than lounges. The most bearish Southwest Airlines analysts already worked with a 5.7% yearly revenue path and about US$2.4b of 2029 earnings before this Rapid Rewards and lounge news. That group sees limited upside at a 7.4x P/E and encourages readers to compare multiple narratives.
Explore 3 other Southwest Airlines fair value estimates, including one that suggests it could be worth just $49.22!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Southwest Airlines research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Southwest Airlines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southwest Airlines' overall financial health at a glance.
Looking For More Investment Ideas Beyond Southwest Airlines?
If the Rapid Rewards overhaul has you rethinking where loyalty and pricing power might matter most, it can help to line Southwest Airlines up against a wider field of opportunities. The Simply Wall St Screener lets you filter for very different styles of companies in a few clicks so your watchlist reflects how you actually like to invest.
- If you want potential mispricings with room for a re rate, start with a focused group of 33 high quality undervalued stocks that combine fundamentals with discounted market expectations.
- If capital preservation matters more to you than chasing every move, narrow your search to a 32 resilient stocks with low risk scores to see which businesses screen well on resilience metrics.
- If balance sheet strength is non negotiable in your process, build a shortlist from a list of solid balance sheet and fundamentals (25 results) that puts debt, liquidity and basic financial robustness front and center.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com