
UK Growth Companies With High Insider Ownership In October 2026
In the wake of recent challenges faced by the FTSE 100, particularly influenced by sluggish trade data from China, the UK market has experienced some turbulence. Amidst these uncertainties, growth companies with high insider ownership can offer a unique advantage as they often signal strong internal confidence and alignment with shareholder interests.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Saga (LSE:SAGA) | 36.5% | 40% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.4% | 22.4% |
| Metals Exploration (AIM:MTL) | 14.8% | 118.9% |
| Hardide (AIM:HDD) | 20.8% | 76.2% |
| Energean (LSE:ENOG) | 19.3% | 32.8% |
| EARNZ (AIM:EARN) | 10.1% | 90.6% |
| Crimson Tide (AIM:TIDE) | 33.5% | 119.1% |
| Beauty Tech Group (LSE:TBTG) | 19.9% | 23.8% |
Here we highlight a subset of our preferred stocks from the screener.
everplay group (AIM:EVPL)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Everplay Group PLC, along with its subsidiaries, develops and publishes independent video games for both digital and physical markets in the United Kingdom, with a market cap of £613.84 million.
Operations: The company generates revenue of £160.55 million from its activities in developing and publishing independent video games for digital and physical markets in the UK.
Insider Ownership: 15.9%
Return On Equity Forecast: N/A (2029 estimate)
Everplay Group shows potential with forecasted earnings growth of 21.1% annually, outpacing the UK market's 11.2%. Despite trading below fair value and analyst targets suggesting a 23.3% price rise, recent results reveal challenges: sales fell to £66.92 million from £72.36 million, and a net loss of £0.583 million contrasts with last year's profit of £10.63 million. No substantial insider trading was reported recently, indicating stable internal sentiment amidst volatility concerns.
- Click here and access our complete growth analysis report to understand the dynamics of everplay group.
- The analysis detailed in our everplay group valuation report hints at an inflated share price compared to its estimated value.

Fevertree Drinks (AIM:FEVR)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Fevertree Drinks PLC, with a market cap of £1.02 billion, develops and sells mixer drinks across the United Kingdom, the United States, Europe, and other international markets.
Operations: Fevertree Drinks PLC generates revenue through the development and sale of mixer drinks in various regions, including the UK, US, Europe, and other international markets.
Insider Ownership: 10.1%
Return On Equity Forecast: 24% (2029 estimate)
Fevertree Drinks demonstrates strong growth prospects with earnings forecasted to grow 20.34% annually, surpassing the UK market's 11.2%. The company is trading at 48% below its estimated fair value, suggesting potential upside. Recent insider activity shows substantial buying over the past three months, indicating confidence in its future performance. Recent results highlight robust sales growth to £165.1 million and net income improvement to £11 million, supporting its progressive dividend policy with a recent increase in dividends declared.
- Dive into the specifics of Fevertree Drinks here with our thorough growth forecast report.
- The analysis detailed in our Fevertree Drinks valuation report hints at an deflated share price compared to its estimated value.

Softcat (LSE:SCT)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Softcat plc is a UK-based value-added IT reseller and IT infrastructure solutions provider with a market cap of £3.65 billion.
Operations: Softcat generates revenue through its role as an IT reseller and provider of IT infrastructure solutions in the UK.
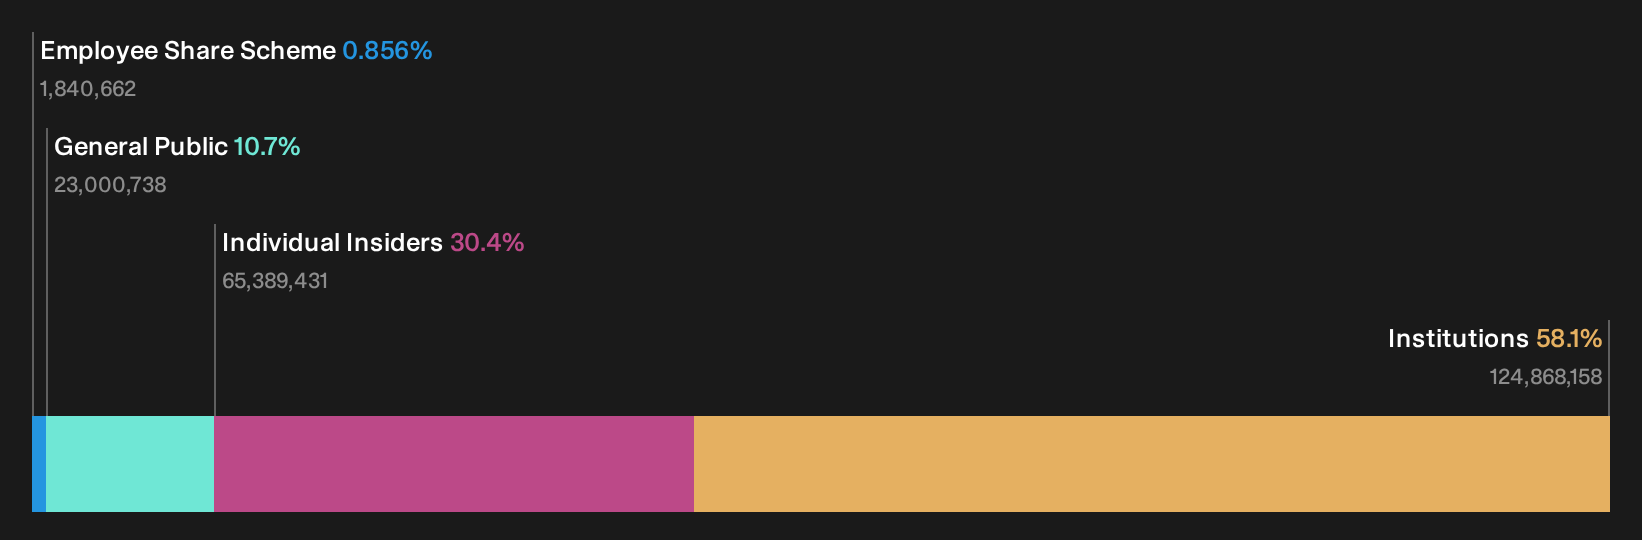
Insider Ownership: 30.4%
Return On Equity Forecast: 30% (2029 estimate)
Softcat's recent earnings report showed substantial growth, with sales reaching £1.98 billion and net income at £150.3 million, reflecting its robust financial health. The company's revenue is forecast to grow 15.8% annually, outpacing the UK market average of 3.8%. Despite no recent insider trading activity, Softcat's strategic focus on acquisitions is supported by a successful equity raise of approximately £354 million, indicating strong future growth potential and insider confidence in its strategic direction.
- Delve into the full analysis future growth report here for a deeper understanding of Softcat.
- Our comprehensive valuation report raises the possibility that Softcat is priced lower than what may be justified by its financials.
Where To Now?
- Click here to access our complete index of 62 Fast Growing UK Companies With High Insider Ownership.
- Ready For A Different Approach? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com