
Industrial And Commercial Bank Of China (SEHK:1398) Raises RMB 60b In Tier 2 Notes, Is It Still Undervalued?
Industrial and Commercial Bank of China (SEHK:1398) has just raised RMB 60b through Tier 2 capital notes, a sizeable funding move that feeds directly into its regulatory capital position.
Investors have treated the Tier 2 issuance as one piece of a much stronger run in Industrial and Commercial Bank of China, with the HK$7.695 share price sitting on top of a 90 day share price return of 11.36% and a 1 year total shareholder return of 41.29%. This builds on a very large 3 year and 5 year total shareholder return profile.
Scan how Industrial and Commercial Bank of China compares with other large institutions that are strengthening their balance sheets through debt issuance by reviewing our hand picked list of solid balance sheet and fundamentals (202 results).
Industrial and Commercial Bank of China now has fresh Tier 2 capital in place and a strong recent return profile. The real question is whether the current HK$7.695 price still leaves meaningful value on the table.
Most Popular Narrative: 8% Undervalued
Against the last close at HK$7.695, the most followed narrative points to a fair value of about HK$8.39 for Industrial and Commercial Bank of China, which implies some remaining upside if those assumptions hold.
Wealth, pension and related agency businesses at Industrial and Commercial Bank of China are scaling, with income from corporate and personal wealth management, precious metals and fund sales, and pensions all rising in the first half of 2026, which supports a larger contribution from fee based revenue and reduces reliance on interest income for earnings.
See why 49 investors see Industrial and Commercial Bank of China as 8% undervalued.
Result: Fair Value of HK$8.39 (UNDERVALUED)
Still, the narrative around Industrial and Commercial Bank of China only holds if credit quality and policy linked lending do not lead to materially higher credit costs or weaker fee income.
Find out about the key risks to this Industrial and Commercial Bank of China narrative.
Another View On Industrial and Commercial Bank of China
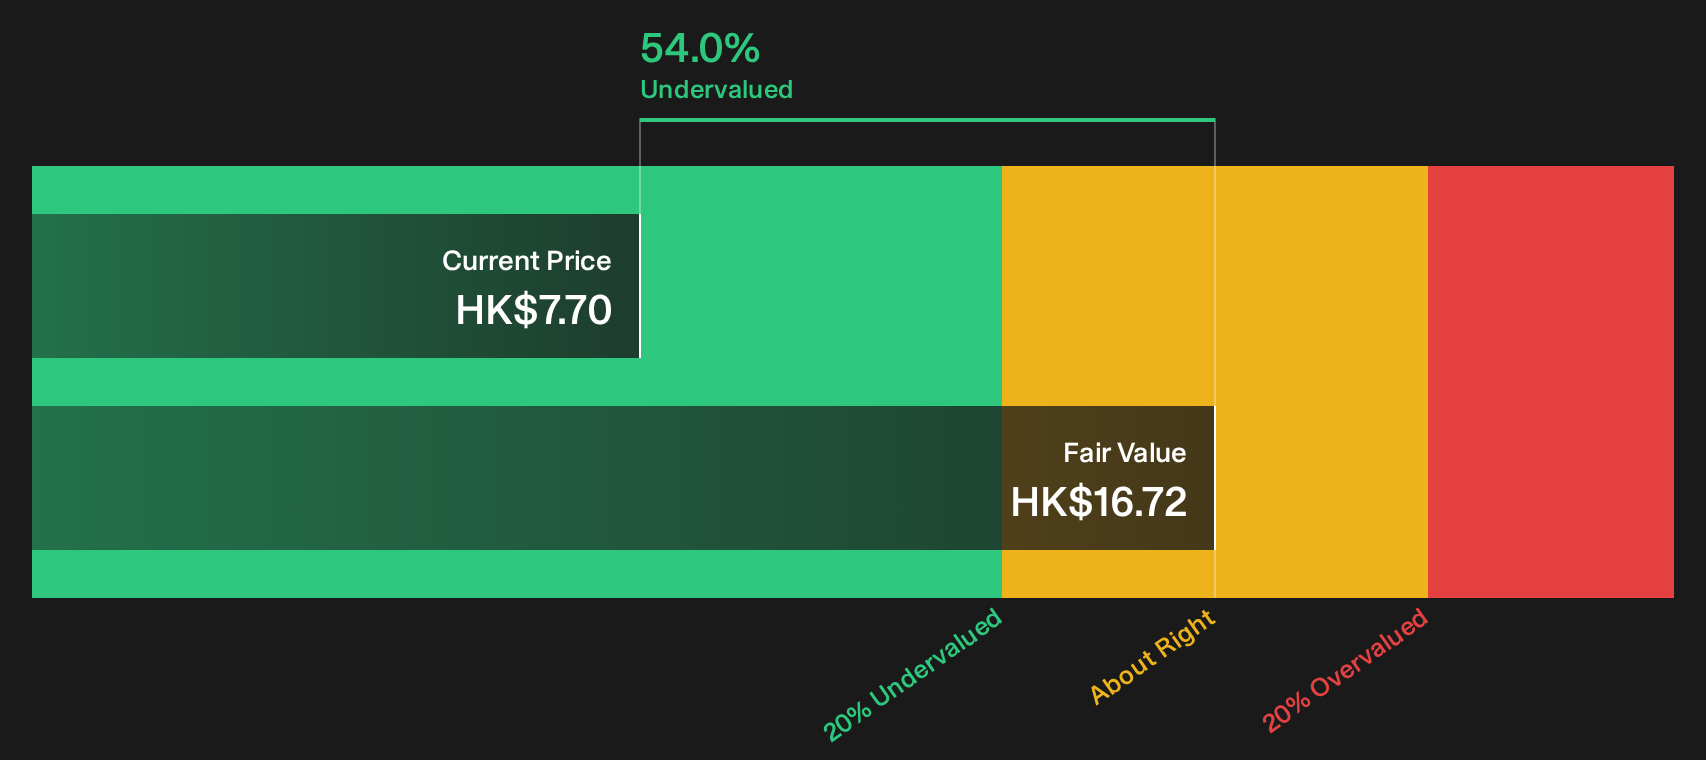
The most popular narrative leans on a fair value of HK$8.39, which points to upside from HK$7.695. A different lens tells a very different story. Simply Wall St's DCF model estimates future cash flow value at HK$16.72, which frames Industrial and Commercial Bank of China as deeply undervalued.
That gap between an HK$8.39 fair value, a HK$7.695 market price, and an HK$16.72 DCF outcome leaves you with a simple question: Which set of assumptions feels more realistic for the next decade of ICBC earnings and cash flows, and where do you see the margin for error?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
With sentiment leaning positive around Industrial and Commercial Bank of China, now is the time to stress test the data and form your own thesis. To see why some investors are optimistic, review the 4 key rewards.
Looking for more investment ideas beyond Industrial and Commercial Bank of China?
If you want a fuller watchlist, use the Simply Wall St screener to spot fresh opportunities before they hit everyone else’s radar.
- Target value first and filter for companies with strong fundamentals using our curated 198 high quality undervalued stocks.
- Prioritise resilience and focus on businesses with steadier risk profiles by reviewing the 225 resilient stocks with low risk scores.
- Spot future leaders early and scan a focused 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com