
What IMAX Holders Bought Into
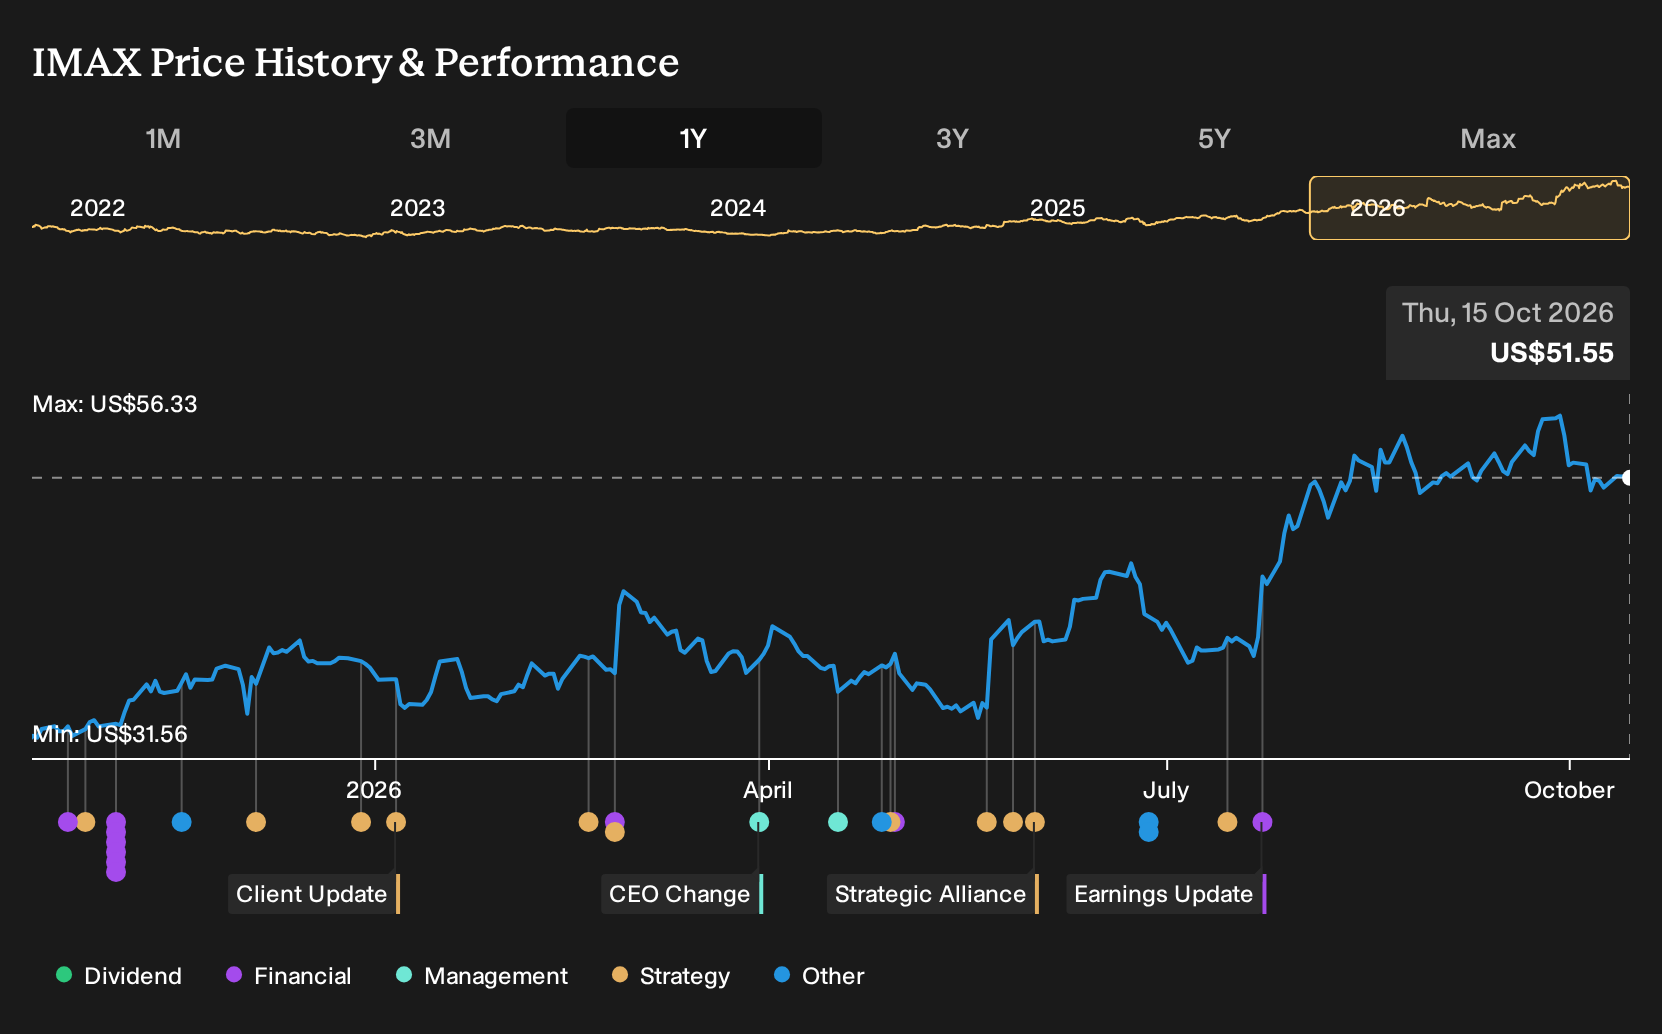
If IMAX was on your watchlist a year ago and you hesitated, this result may sting a little. Investors who held IMAX over the past year are up 63.3%, including dividends. That gain arrived alongside record-breaking IMAX releases and fresh doubts about at-home viewing eating into big-screen habits. If you were weighing a buy decision back in October 2025, which mattered more: the streaming risk or the pull of premium global box office?
The easy part of this move is behind IMAX. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Two IMAX Stories Investors Had To Choose Between
The shares cost US$31.71 at the start of the period, and anyone weighing IMAX then had to choose between two very different stories about the future of premium cinema.
On the bullish side, one camp saw a Fair Value of US$38, effectively a price implied by strong assumptions about the business. That view leaned on immersive technology and Asia-Pacific demand, expecting rapid network expansion and recurring installation-related income to keep growing.
The bearish camp anchored around a Fair Value of US$18, again an implied price grounded in its own forecasts. This group focused on at-home entertainment, arguing that better home cinema setups and weaker cinema habits for younger audiences could limit IMAX attendance and future box office revenue.
What The Evidence Did To The IMAX Argument
IMAX’s later Q2 2026 report showed total revenue of US$102.842 million and net income of US$15.402 million, with net margin at 15.0% versus 12.3% a year earlier. That outcome leaned toward the bullish profitability story about higher margins on premium experiences, yet it did not erase the bear case that at-home viewing could still pressure attendance in future years.
The useful takeaway is simple. When a thesis hinges on premium pricing power, keep testing it against reported net margin and absolute profit, not just headline box office or eye catching event releases at companies you follow.
What Today's IMAX Price Already Assumes
IMAX now trades at US$51.55, and the selected Narrative’s Fair Value sits below that level. The focus of that view is not demand, but whether the current footprint and backlog can be run smoothly enough to justify the valuation.
A buyer at today’s price effectively banks on premium screens and newer formats delivering high margins despite hardware strain and support complexity flagged in the Narrative.
"Although IMAX still has significant headroom to add to its roughly 1,800 locations toward a stated addressable market of about 4,500, each incremental screen also raises exposure to technical weak points, as seen with the 70mm air compressor failures in Las Vegas. This could translate into more frequent show cancellations, refunds and unplanned service costs that pressure revenue and net margins over time."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 31% below our estimate - sells infrastructure enabling AI pilots to scale into full data centres.
- Company 2 - 33% below our estimate - runs higher cost mines exchanging geopolitical complexity for extended reserve life.
- Company 3 - 42% below our estimate - converts specialist PhD knowledge into tailored scientific and engineering project solutions.
That is three of the list. See all 25 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com