
Discovering Undiscovered Gems in Asia October 2026
In the dynamic landscape of Asian markets, investors are navigating a complex environment shaped by geopolitical tensions, fluctuating oil prices, and evolving monetary policies. As small-cap stocks in the region respond to these global shifts, uncovering hidden opportunities requires a keen understanding of market trends and economic indicators. Identifying potential gems involves looking for companies with strong fundamentals and growth potential that can withstand current market volatility.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Jangho Group (SHSE:601886)
Simply Wall St Value Rating: ★★★★★★
Overview: Jangho Group Co., Ltd. operates in the building decoration and medical health sectors both within China and internationally, with a market capitalization of approximately CN¥14.14 billion.
Operations: Jangho Group generates revenue primarily from its building decoration and medical health businesses. The company's financial performance is highlighted by a focus on these sectors, contributing to its market presence both domestically and internationally.
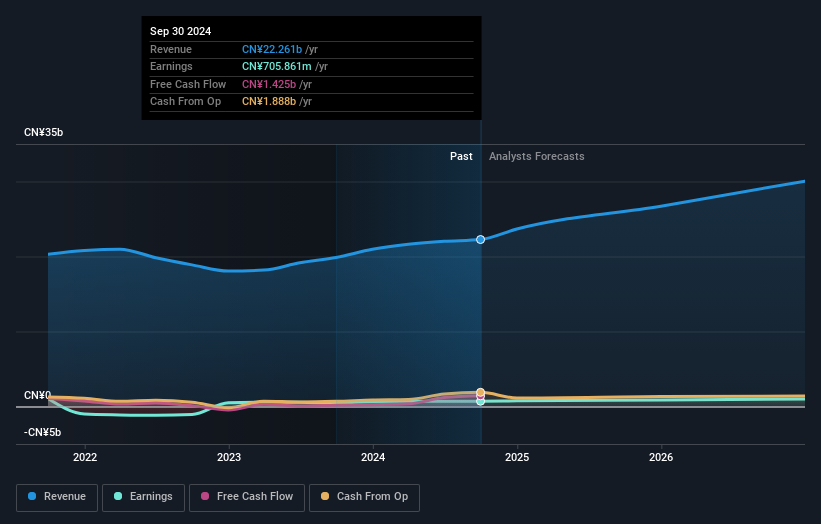
Jangho Group, a notable player in the construction sector, has demonstrated robust financial health with earnings growing by 12.4% over the past year, outpacing its industry peers. The company is trading at an attractive valuation, 44.2% below its estimated fair value, and boasts a debt-to-equity ratio reduction from 30.1% to 24.9% over five years. Despite a one-off loss of CN¥273 million impacting recent results, Jangho's net income rose to CN¥440 million for H1 2026 compared to CN¥328 million the previous year, reflecting strong operational resilience and growth potential in the coming years.
- Click here and access our complete health analysis report to understand the dynamics of Jangho Group.
Review our historical performance report to gain insights into Jangho Group's's past performance.
Shandong Bailong Chuangyuan Bio-Tech (SHSE:605016)
Simply Wall St Value Rating: ★★★★★☆
Overview: Shandong Bailong Chuangyuan Bio-Tech Co., Ltd. operates in the biotechnology sector, focusing on the production of prebiotics, dietary fibers, and healthy sweeteners, with a market capitalization of CN¥8.06 billion.
Operations: Bailong Chuangyuan generates revenue primarily from its Dietary Fiber Series, contributing CN¥853.46 million, followed by the Prebiotics Series at CN¥388.97 million and Healthy Sweetener Series at CN¥208.95 million.
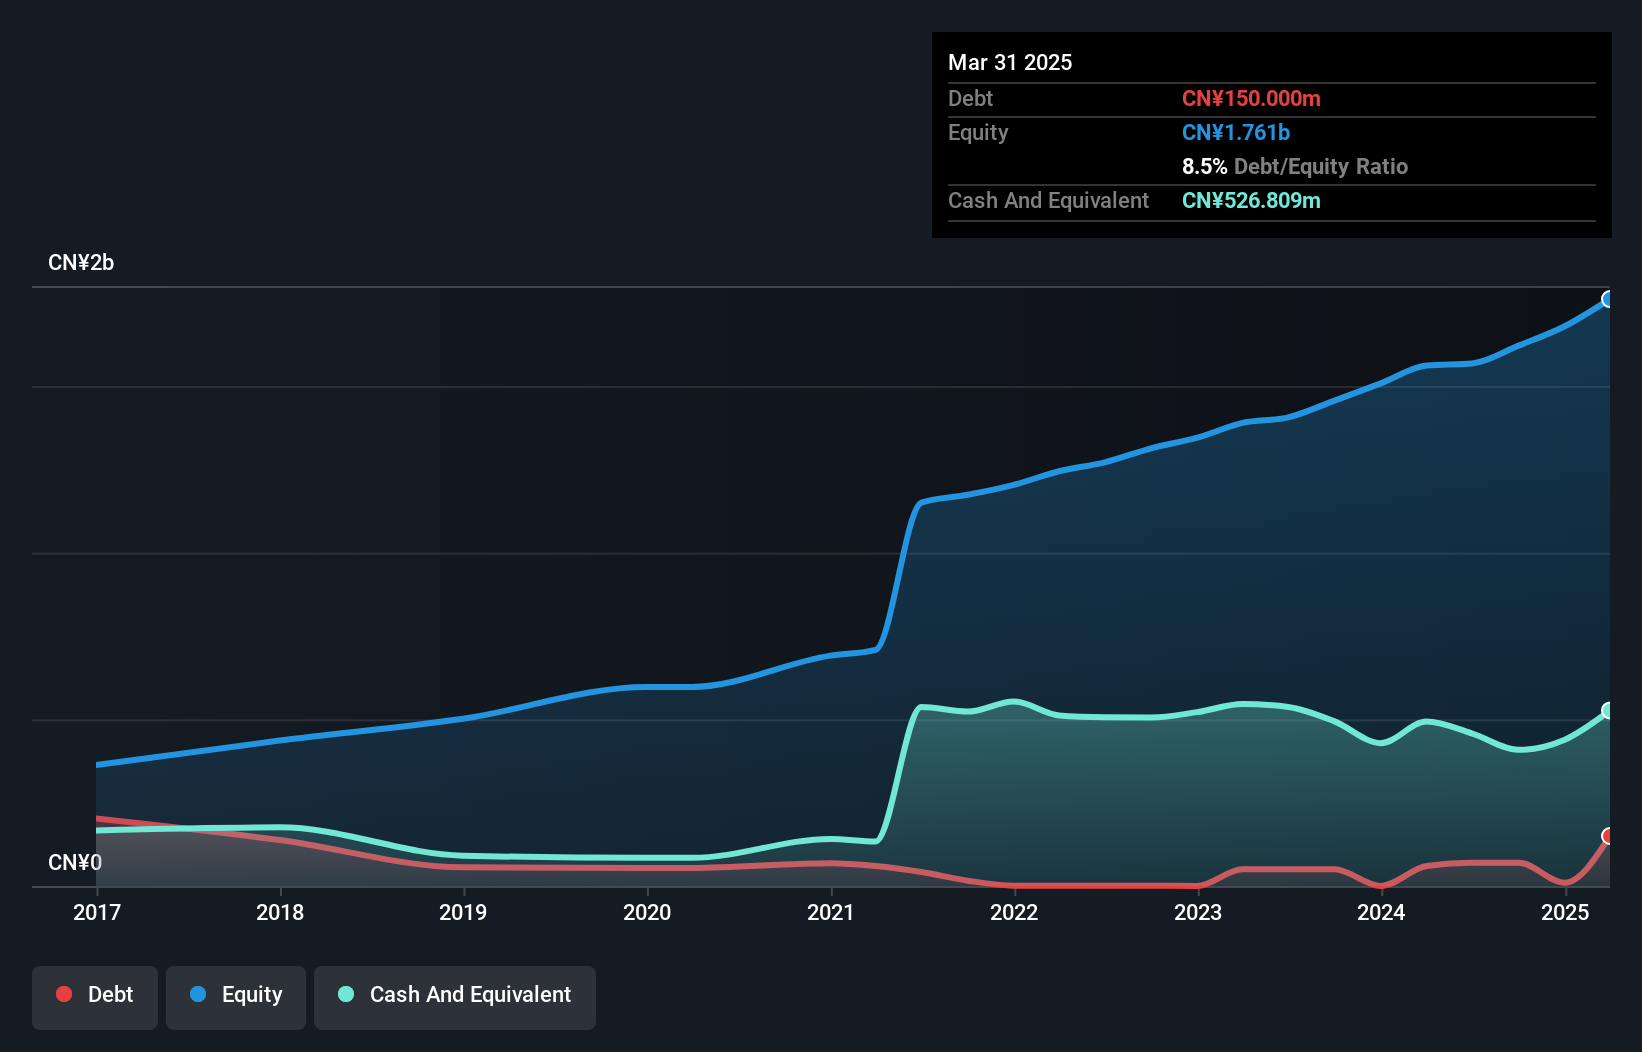
Shandong Bailong Chuangyuan Bio-Tech, a notable player in the bio-tech industry, has seen impressive earnings growth of 38.4% over the past year, outpacing the broader food industry which faced a 7% challenge. Trading at 37% below its estimated fair value suggests potential for investors seeking undervalued opportunities. The company reported net income of CNY 210.64 million for H1 2026, up from CNY 169.78 million in the previous year, alongside revenue growth to CNY 759.46 million from CNY 649.19 million last year. With a debt to equity ratio rising from 3.7% to 21.3% over five years, financial leverage is increasing but remains manageable given their cash position exceeding total debt levels.
- Dive into the specifics of Shandong Bailong Chuangyuan Bio-Tech here with our thorough health report.
Learn about Shandong Bailong Chuangyuan Bio-Tech's historical performance.
Sodick (TSE:6143)
Simply Wall St Value Rating: ★★★★★★
Overview: Sodick Co., Ltd. is a company that, along with its subsidiaries, focuses on developing, manufacturing, and selling numerical control electric discharge machines (EDMs) both in Japan and internationally, with a market cap of ¥77.11 billion.
Operations: Sodick generates revenue primarily from its Machine Tool Business, which accounts for ¥67.34 billion. The Industrial Machinery segment contributes ¥10.39 billion, while the Food Machinery segment adds ¥6.94 billion to the total revenue.
Sodick, a nimble player in the machinery sector, has been making waves with its impressive earnings growth of 68.2% over the past year, outpacing the industry's 25.5%. The company is trading at a significant discount of 64.8% below its estimated fair value, suggesting potential for investors seeking undervalued opportunities. Recently, Sodick announced a share repurchase program worth ¥3 billion to enhance shareholder returns and capital efficiency. Despite volatility in its share price recently, Sodick's financial health appears robust with more cash than total debt and high-quality earnings contributing to its solid footing in the market.
- Click here to discover the nuances of Sodick with our detailed analytical health report.
Examine Sodick's past performance report to understand how it has performed in the past.

Make It Happen
- Investigate our full lineup of 123 Asian Undiscovered Gems With Strong Fundamentals right here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com