
Novanta (NOVT) Could Be 31% Below Fair Value On Its Medical Growth Story
Recent price moves put Novanta (NOVT) back under the microscope for investors. The stock closed at US$134.80 on 16 October 2026, with returns mixed across recent time frames.
Short term momentum for Novanta has cooled, with the share price return down 3.76% over one day and 9.35% over 90 days. However, the year-to-date share price return of 21.29% and 1 year total shareholder return of 26.44% still point to stronger recent performance than the longer term 3 and 5 year total shareholder returns.
Scan beyond Novanta and line up its recent swings against a curated set of 91 robotics and automation stocks that share similar exposure to automation and precision technologies.
After a sharp run this year followed by a cooler patch, the real question on Novanta now is whether the recent pullback leaves enough reward to justify the remaining risk as valuation comes under the spotlight.
Most Popular Narrative: 31% Undervalued
On the most followed view, Novanta’s fair value sits at $194.50, well above the recent $134.80 close. This puts execution risk and future growth firmly in focus for readers weighing the pullback.
Expansion of minimally invasive and robotic surgery, together with the Riverpoint Medical acquisition that roughly doubles recurring medical consumables revenue to about US$300 million and lifts medical exposure to around 60% of sales, increases Novanta's mix of repeat consumables that can support more resilient revenue and gross margin over time.
See why 6 investors see Novanta as 31% undervalued.
Result: Fair Value of $194.50 (UNDERVALUED)
Still, higher leverage after the US$1.45b Riverpoint Medical deal and pressure on Medical Solutions margins could quickly weaken confidence in the Novanta thesis.
Find out about the key risks to this Novanta narrative.
Another View: Rich Multiples Keep Novanta In Check
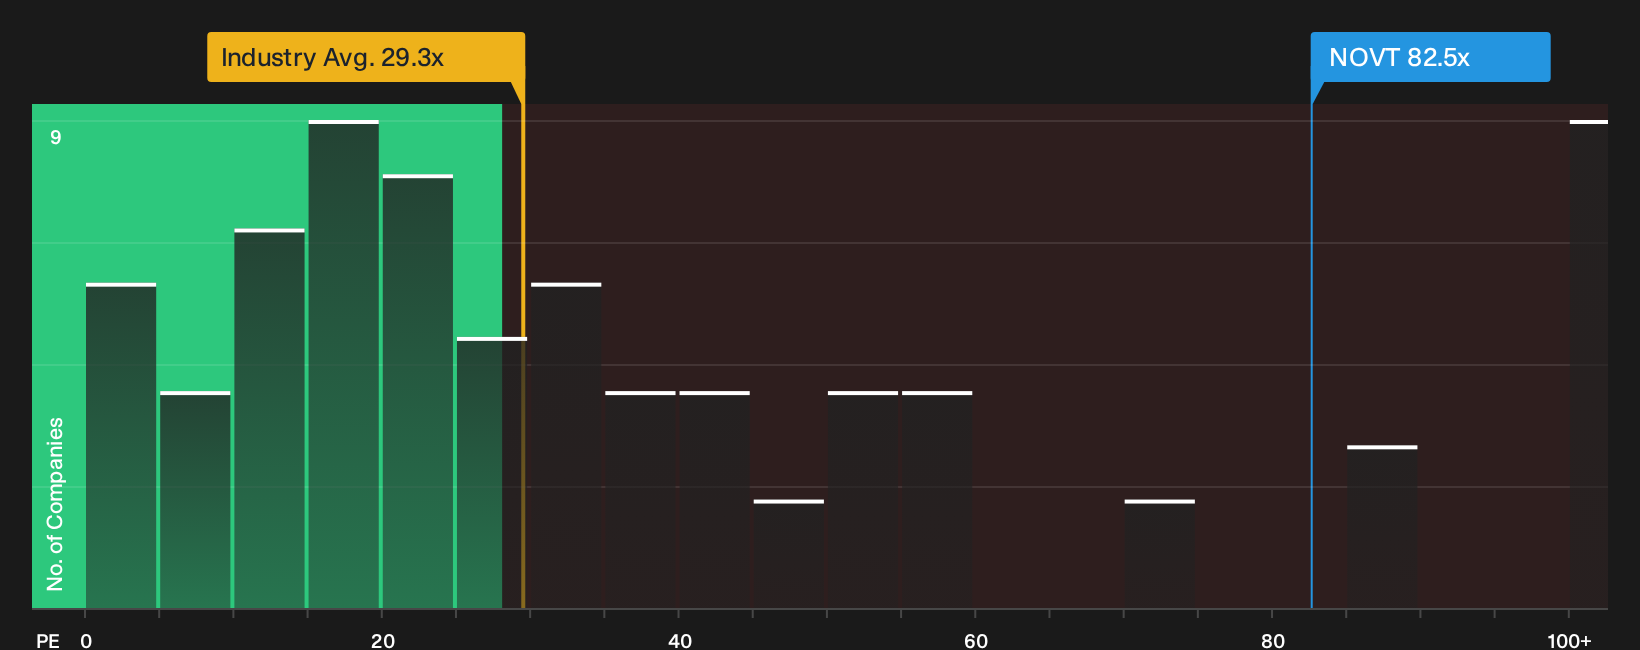
The story around Novanta’s fair value looks very different once the focus shifts to simple earnings multiples. On a P/E of 82.5x versus 29.3x for the US Electronic industry and 52.5x for peers, the stock trades on a much richer tag that raises clear valuation risk.
The fair ratio sits at 40.6x, roughly half the current level. This suggests there could be significant scope for that multiple to compress if expectations cool. For anyone weighing the recent pullback, the question is whether future growth can support this premium or if the market is already paying up.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Novanta’s valuation and risk can feel messy, so move quickly, test the numbers for yourself, and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Novanta?
If Novanta has you thinking harder about risk and reward, do not stop here. Fresh ideas elsewhere could shift how you position your next move.
- Target resilience first and filter for companies that prioritise balance sheet strength with the list of solid balance sheet and fundamentals (25 results).
- Spot potential value gaps early by scanning a curated set of 32 high quality undervalued stocks before attention moves elsewhere.
- Optimize for smoother rides in rough markets by focusing on 32 resilient stocks with low risk scores that still meet your quality bar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com