
Is Great Portland Estates (LSE:GPE) Undervalued On Strong Leasing And Pre Let Demand?
Great Portland Estates (LSE:GPE) is back in focus after reporting first half leasing activity that generated £19.0m in annual rent, alongside the fully pre let completion of its 30 Duke Street St James’s project.
For investors watching the tape, Great Portland Estates has seen momentum pick up, with a 7.58% 7-day share price return and an 8.74% 30-day share price return, even though the 1-year total shareholder return is slightly down 1.24% and the 5-year total shareholder return is down 40%.
Scan how Great Portland Estates compares with other real estate players by checking our curated list of list of solid balance sheet and fundamentals (9 results).
After that sharp short term bounce and a 5 year record that still shows deep losses, the real question on Great Portland Estates now is whether most of the upside is already in the price or still ahead.
Preferred P/E of 8.5x: Is it justified?
Valuation for Great Portland Estates right now revolves around a relatively low P/E of 8.5x set against its recent share price recovery.
The P/E ratio compares what investors pay per share with the earnings that Great Portland Estates generates per share. For property owners and REIT style businesses, this measure helps you see how much the market is charging for each pound of underlying profit.
Here the comparison is blunt. Great Portland Estates trades on a P/E of 8.5x while the estimated fair P/E sits at 12.4x. Against peers it is also on a lower multiple, with the UK market on 16.2x, the UK Office REITs peer group on 28.1x and the global Office REITs average on 17.4x. That gap suggests the market is assigning a cheaper price to GPE's current earnings than both the fair ratio points to and what investors are paying elsewhere.
Explore the SWS fair ratio for Great Portland Estates.
Result: Price-to-earnings of 8.5x (UNDERVALUED)
Still, the 5 year shareholder return remains deeply negative, and Great Portland Estates is heavily focused on a single, highly cyclical London market, which can quickly shift sentiment.
Find out about the key risks to this Great Portland Estates narrative.
Another view on Great Portland Estates valuation
On a simple earnings multiple, Great Portland Estates looks cheap. The picture shifts when using the SWS DCF model, which puts future cash flow value at £0.87 per share against a market price around £3.24, implying the stock screens as expensive on that framework.
This clash between an 8.5x P/E that screens as attractive and a DCF output that points to overvaluation raises a practical question: which yardstick do you trust more when the cash flow model and the earnings multiple point in opposite directions for the same company?
Look into how the SWS DCF model arrives at its fair value.
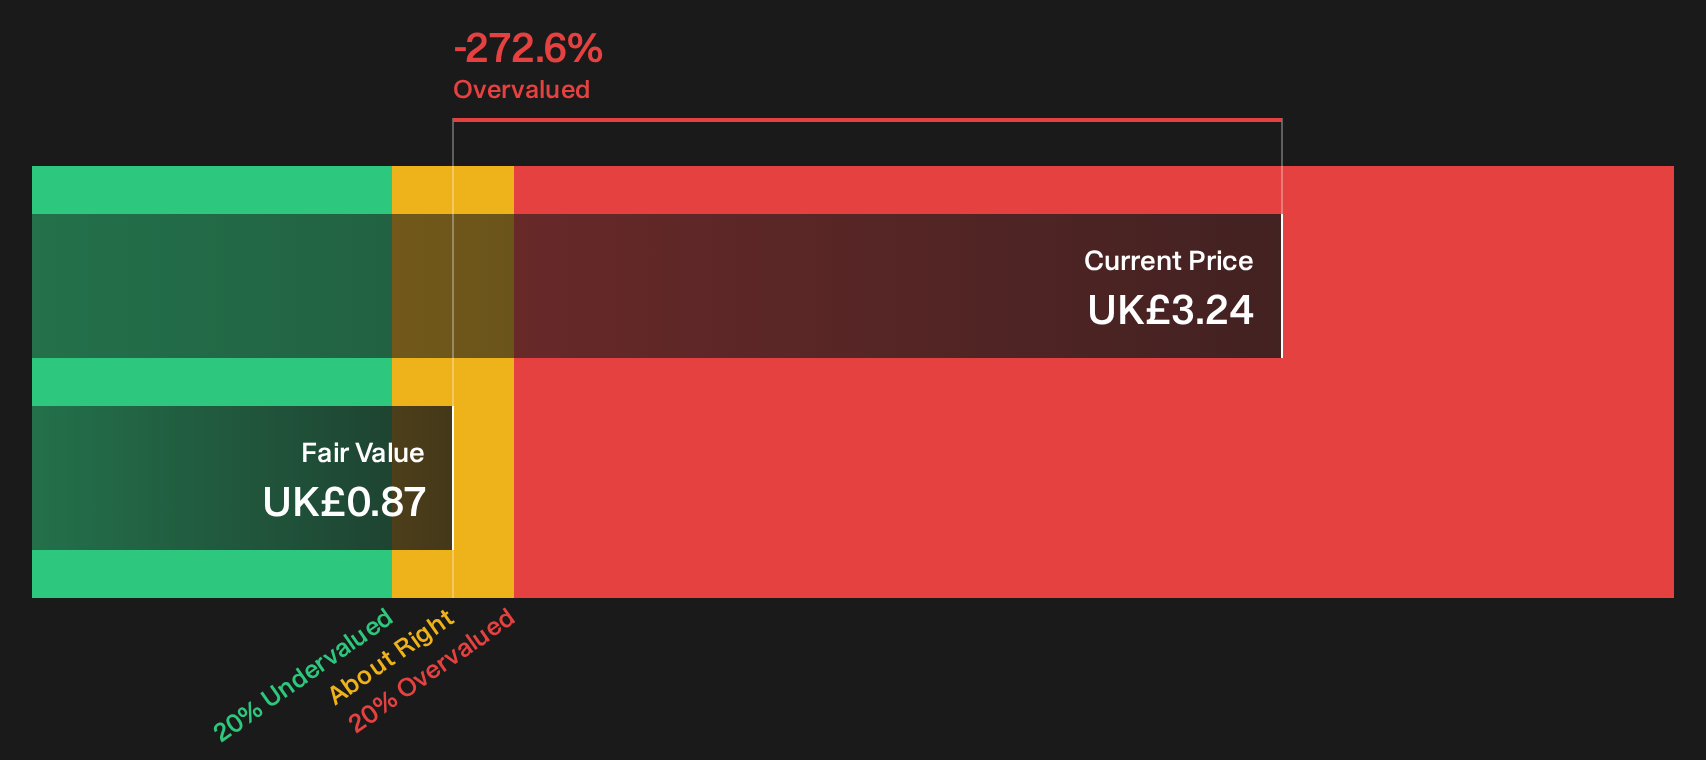
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Great Portland Estates for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 9 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Great Portland Estates valuation and risk profile do not need to leave you on the sidelines. Move quickly and make your own call by weighing its 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Great Portland Estates?
Do not stop at Great Portland Estates. Use the Simply Wall Street Screener to spot other opportunities that fit your goals before the market prices them differently.
- Target potential mispricing by scanning a focused set of 9 high quality undervalued stocks that pair quality fundamentals with comparatively low valuation multiples.
- Prioritise resilience by reviewing 4 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- Get early access to potential future leaders by sorting through 5 high quality undiscovered gems with solid financial profiles that attract less market attention today.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com