
How Investors Are Reacting To Invesco (IVZ) ETF Suite Expansion
- Invesco recently added the Nasdaq International Innovators 100 ETF, ticker QQI, to its Innovation Suite, taking the line-up to six ETFs and broadening its global ETF product shelf.
- The launch underscores Invesco's focus on pricing, transparency, and liquidity in ETFs, while the firm explores tokenization mainly for private markets to improve efficiency and access.
- This article examines how Invesco's broader investment narrative is affected by the QQI launch and the push to expand its Innovation Suite.
Scan how Invesco's QQI launch fits into the wider hunt for listed disruptors by reviewing our hand picked 38 AI small caps across global markets.
Invesco Investment Narrative Recap
To own Invesco, you need to believe the asset manager can keep shifting its mix toward ETFs, index products, and higher-fee alternatives while controlling the drag from legacy active equity and rising compliance costs. The QQI launch extends that ETF shelf but does not materially change the near term story on its own.
The key short term swing factor remains execution on product mix and cost discipline while the firm works back from a recent net loss of US$309.2 million on US$6.9b of revenue. The biggest risk is that fee compression and competitive pressure in ETFs and active strategies keep outpacing efficiency gains.
The QQI ETF fits most cleanly with Invesco's broader ETF and index push, including its established Q series funds such as QQQ and QQQM. This is the area many investors watch for scale benefits, given fee pressure across the industry and the shift to lower cost products that can still generate meaningful aggregate revenue at size.
The more consequential operational development in the story is still the planned modernization of QQQ's structure into an open end ETF. That proposal, if implemented as described, is expected to lift net revenue by about 4 basis points. For a manager of Invesco's scale, even modest improvements in economics on flagship products can be a key earnings catalyst.
Invesco's narrative projects US$7.9b revenue and US$1.5b earnings by 2029. This implies 4.6% yearly revenue growth and an earnings swing of about US$1.8b, from a loss of US$309.2 million today to the forecast consensus earnings level.
Uncover why Invesco's fair value indicates a 21% potential upside to its current price before that discount narrows.
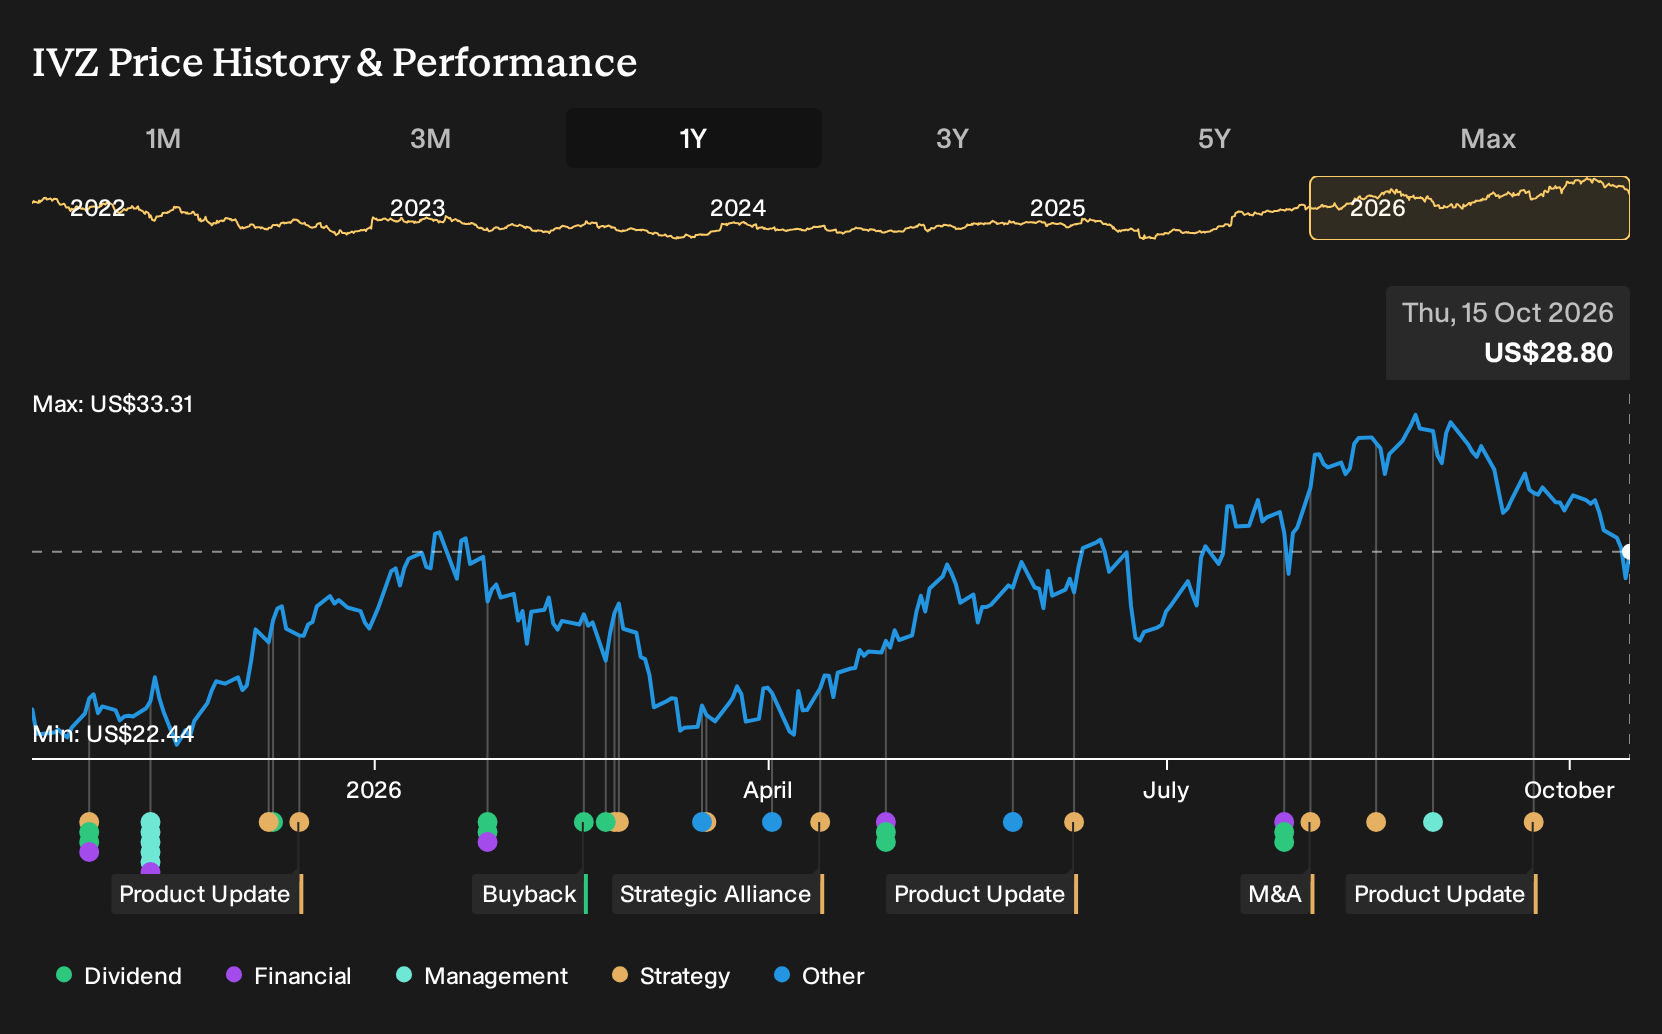
Exploring Other Perspectives
You see QQI as a fresh ETF launch. The most pessimistic Invesco narrative worries that tech driven fee pressure keeps grinding down revenue, with bearish analysts modelling the top line drifting toward about US$6.2b by 2029 but earnings near US$1.7b. Those views pre date QQI, so forecasts may shift from here.
Explore 3 other Invesco fair value estimates, including one that suggests it could be worth just $30.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Invesco research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Invesco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Invesco's overall financial health at a glance.
Looking for more Invesco‑style investment ideas?
If the Invesco story has you thinking about portfolio upgrades, it can help to widen the lens and compare it with other companies that share similar qualities in value, resilience, or balance sheet strength using the Simply Wall St Screener.
- For investors hunting for quality at a discount, scan a curated 32 high quality undervalued stocks that combine strong fundamentals with more modest pricing.
- If capital preservation is high on your list, focus on a 32 resilient stocks with low risk scores that score well on stability and business resilience.
- When you want sturdier finances behind the ticker, start with a list of solid balance sheet and fundamentals (25 results) and see which companies pair healthy leverage with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com