
What Medistim Holders Bought Into
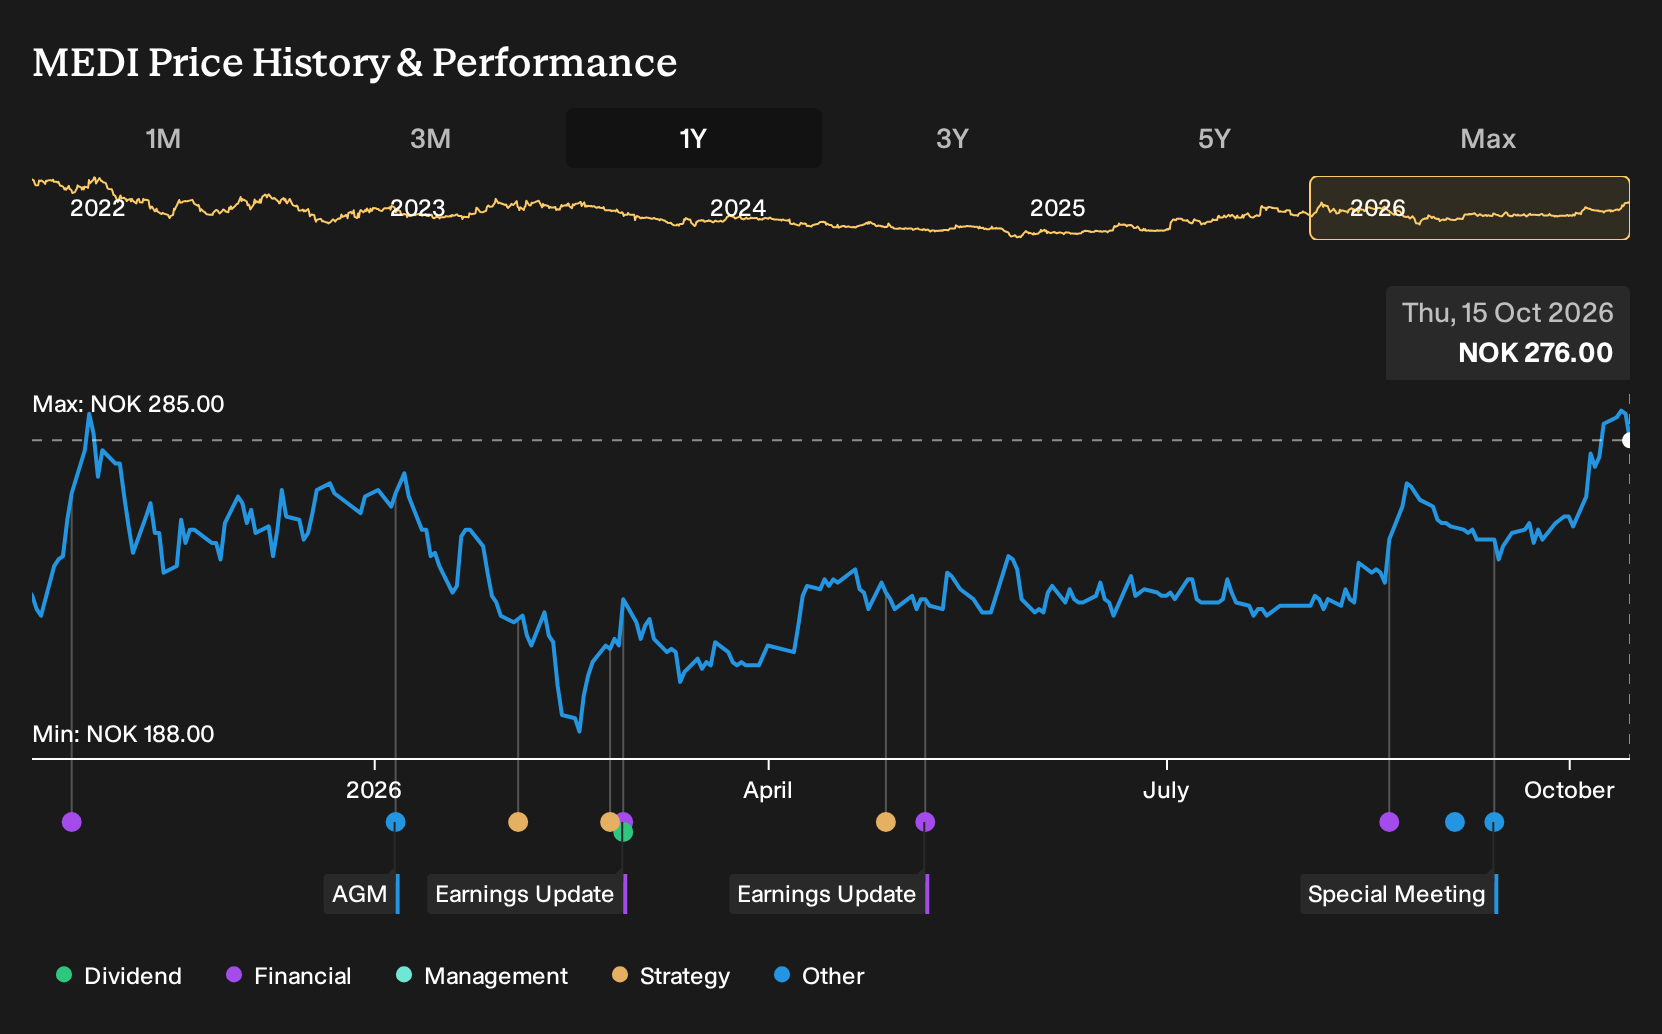
If you watched Medistim roll out its INTUI software upgrades across new systems, the story looked like one about better tools in the operating room rather than a trading outcome. For Medistim shareholders, the return over the past year was 27.1%, including dividends. If you were deciding whether to buy on 15 October 2025, what did you need to believe about future demand and pricing power before the later revenue and profit figures arrived?
If the move has made Medistim harder to judge, start where the gap is still open and scan 197 high quality undervalued stocks.
The Argument Medistim Investors Were Weighing
The shares cost NOK229 at the start of the period, and anyone looking at Medistim then was really deciding which future story felt more plausible.
The bullish narrative put Fair Value at NOK260, a rough guide to the price implied if INTUI upgrades, direct sales and R&D spending did deliver the higher pricing power and margin expansion that optimistic forecasts assumed.
The bearish view pointed to a Fair Value of NOK200, based on expectations that rising cost pressure, tighter reimbursement and a shrinking pool of traditional cardiac surgery patients would restrict revenue growth and keep future P/E closer to 27.3x.
What The Medistim Results Actually Tested
The cleanest datapoint was the Q2 2026 report. Medistim showed revenue of NOK202.031m versus NOK169.076m a year earlier, and net income of NOK52.204m versus NOK42.984m. Net margin edged up from 25.4% to 25.8%. That combination of higher sales, higher profit and slightly stronger profitability supported more of the optimistic case than the cautious one, although only over a single quarter.
The lesson is simple. When a story hinges on pricing power and margin expansion, it is important to keep checking revenue, net income and margin together in each result rather than relying on one headline figure.
What Medistim's Current Price Already Bakes In
Medistim now trades at NOK276, after a 27.1% gain over the past year. The selected Narrative places its own Fair Value above that level, framed around what direct selling and pricing in Flow and Imaging could mean for the business over time.
The Narrative argues that today’s price still does not fully credit successful execution on direct expansion, pricing and key clinical and automation projects.
"Expansion of Medistim’s direct commercial footprint in markets such as China and Japan, building on the decision to go direct and the recently established 10 person team in Japan, can open up new hospitals and surgeons to its own products and shift more revenue into higher margin direct sales, which would affect both revenue and net margins."
The price and this Narrative do not agree. → Uncover what this Narrative says Medistim is actually worth
Where Medistim’s Story Connects Outward
Once you understand Medistim, it is natural to look sideways. Cardiac procedures still depend on reliable ways to diagnose and treat vessels.
One large specialist targets those same clinical decisions from a different angle. It supplies devices that help clear blocked arteries and support rhythm management.
Its tools sit inside many minimally invasive procedures, where surgeons want fast, precise interventions. That mirrors the same push for better information Medistim users care about.
If more treatment shifts into catheter labs instead of open surgery, the balance of value inside heart care could look very different.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 124% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com