
Earnings Beat Might Change The Case For Investing In Constellation Brands Stock (STZ)
- Constellation Brands reported second quarter 2026 sales of US$2,816.7 million and net income of US$565.8 million, with basic earnings per share from continuing operations of US$3.32, and declared a quarterly dividend of US$1.03 per share payable in November 2026.
- The combination of higher quarterly earnings and a maintained cash payout indicates that Constellation Brands is relying on its core beer and Wine & Spirits operations to generate cash while supporting shareholders directly through dividends.
- We will now look at how Constellation Brands' investment narrative could be influenced by this earnings report and dividend affirmation.
Scan how Constellation Brands' latest earnings and dividend stack up against other cash generating consumer stocks in our hand picked list of solid balance sheet and fundamentals (25 results).
Constellation Brands Investment Narrative Recap
Owning Constellation Brands means believing its Mexican beer engine can keep carrying the group while Wine & Spirits slowly stops weighing on profitability. The latest quarter shows higher sales, revenue and net income compared with a year ago, which supports that operating story. The key short term swing factor remains how beer volumes hold up where Hispanic consumers are under pressure.
The biggest near term risk still sits in weaker category trends and soft channels for Wine & Spirits, alongside potential new tariffs that could squeeze costs. On that front, this earnings print does not radically change the risk profile. It mostly confirms the current trajectory rather than resetting it.
The most relevant headline for this catalyst discussion is the quarterly dividend of US$1.03 per share, payable in November 2026. Keeping that payout while basic earnings per share from continuing operations reached US$3.32 in the quarter points to solid cash generation from the core beer and Wine & Spirits portfolio.
For you as a shareholder, that dividend affirmation ties directly to execution risk and balance sheet choices. The company still carries a high level of debt, so ongoing cash returns to investors need to be weighed against potential tariff impacts, margin pressure in Wine & Spirits and the need to keep funding growth opportunities in beer and emerging categories.
Constellation Brands' current analyst narrative points to US$9.5b in revenue and US$2.1b in earnings by 2029. This is based on 1.2% yearly revenue growth and an earnings increase of about US$0.2b from US$1.9b today.
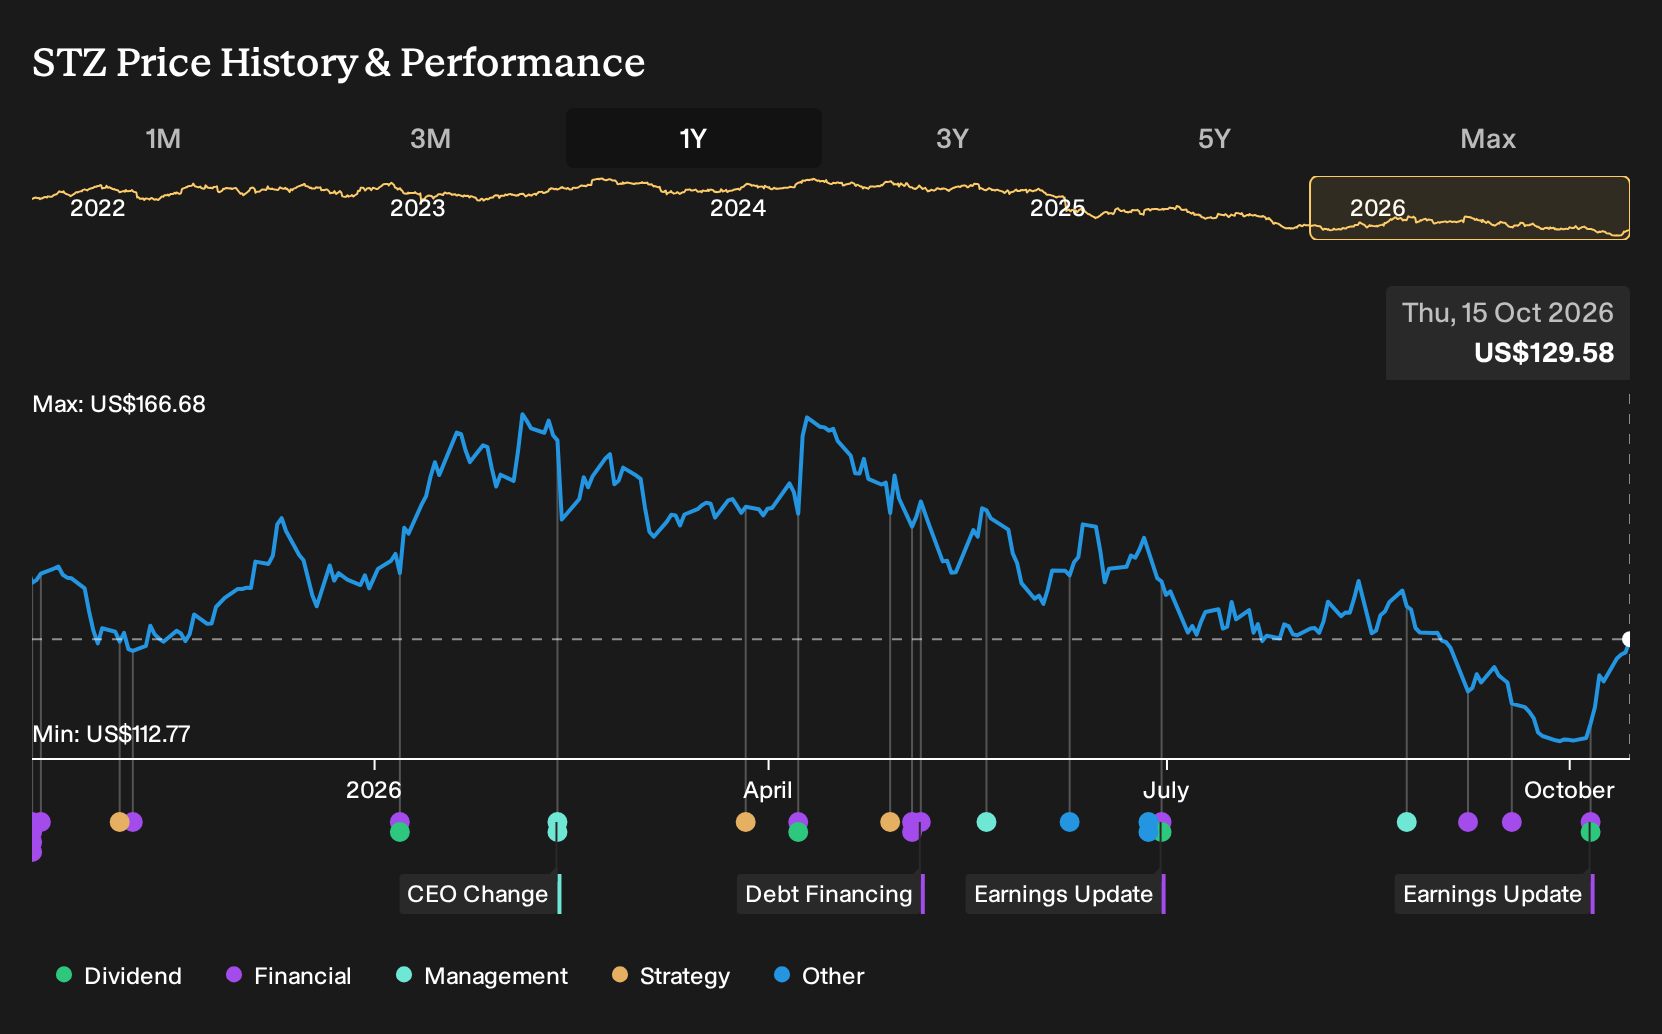
Uncover why Constellation Brands' fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some bullish analysts focus on a different catalyst for Constellation Brands. They lean on the idea that high beer margins can persist, pointing to earlier forecasts of about US$9.9b in revenue and US$2.2b in earnings by 2029. This latest earnings jump and dividend decision could nudge those optimistic narratives, or challenge them. It may be useful to compare a few viewpoints before you decide what feels realistic.
Explore 6 other Constellation Brands fair value estimates, including one that suggests potential upside of up to 140% from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Constellation Brands research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Constellation Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Constellation Brands' overall financial health at a glance.
Looking for more Constellation Brands investment ideas?
If this Constellation Brands update has sharpened your thinking and you want to widen the opportunity set, the Simply Wall St Screener can help you line up other stocks with very different risk and return profiles in just a few minutes.
- If you are hunting for strong balance sheets and cleaner fundamentals, start with a curated list of solid balance sheet and fundamentals (25 results) that share similar financial resilience characteristics.
- For investors who care most about price versus quality, scan a focused group of 32 high quality undervalued stocks that combine fundamentals with a margin of safety.
- If consistent income is higher on your list than rapid capital gains, filter for 8 dividend fortresses that offer higher yields with supporting financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com