
Why Did Hycroft Mining Holding (HYMC) Move Today?
Hycroft Mining Holding (HYMC) just reported the highest grade gold and silver intercept in its history from the 2025 to 2026 drilling at the Vortex system, which has accelerated fresh exploration work.
At a share price of US$17.42, Hycroft Mining Holding has seen short term momentum cool, with the 30 day share price return down 15.85% and the year to date share price return down 28.61%. However, the 3 year total shareholder return of almost 5x signals that longer term sentiment around the project potential remains strong and that fresh drill results are now reshaping how investors weigh upside against risk.
Spot opportunities beyond Hycroft Mining Holding by scanning our curated 35 elite gold producer stocks, which features other companies being reshaped by fresh drilling results and shifting market expectations.Fresh drilling has raised expectations while the HYMC share price has already had a big multi year run, then pulled back. Does the current valuation still leave enough upside to justify that exploration risk?
Preferred Price-to-Book of 6.5x: Is it justified?
Valuation is tight for Hycroft Mining Holding at $17.42, since the stock trades on a 6.5x price-to-book ratio against a sector that sits much lower.
P/B compares the market value of the equity to its book value. For a miner, this can act as a rough check on how aggressively the project pipeline and asset base are being priced. For HYMC, a 6.5x multiple signals that investors as a group are placing a rich value on a business that currently reports no revenue and a net loss of $86.205m.
That premium is steep when put beside the US Metals and Mining industry average of 2.2x and a peer average of 3.6x. On this metric, the market is effectively valuing Hycroft Mining Holding at around triple the broader industry level. This sets a high bar for the mine plan, drilling results and any future ramp up to support.
Result: Price-to-book of 6.5x (OVERVALUED)
See what the numbers say about this price — find out in our valuation breakdown.Still, the story can change quickly if drilling results disappoint or if Hycroft Mining Holding needs fresh capital on terms that heavily dilute existing shareholders.
Find out about the key risks to this Hycroft Mining Holding narrative.
Another view on Hycroft Mining Holding’s value
The P/B multiple suggests that Hycroft Mining Holding is richly priced. A different valuation lens tells another story. Our DCF model estimates fair value at $44.79 per share, while the market price is $17.42, which screens as undervalued using that approach. Which signal do you put more weight on?
Look into how the SWS DCF model arrives at its fair value.
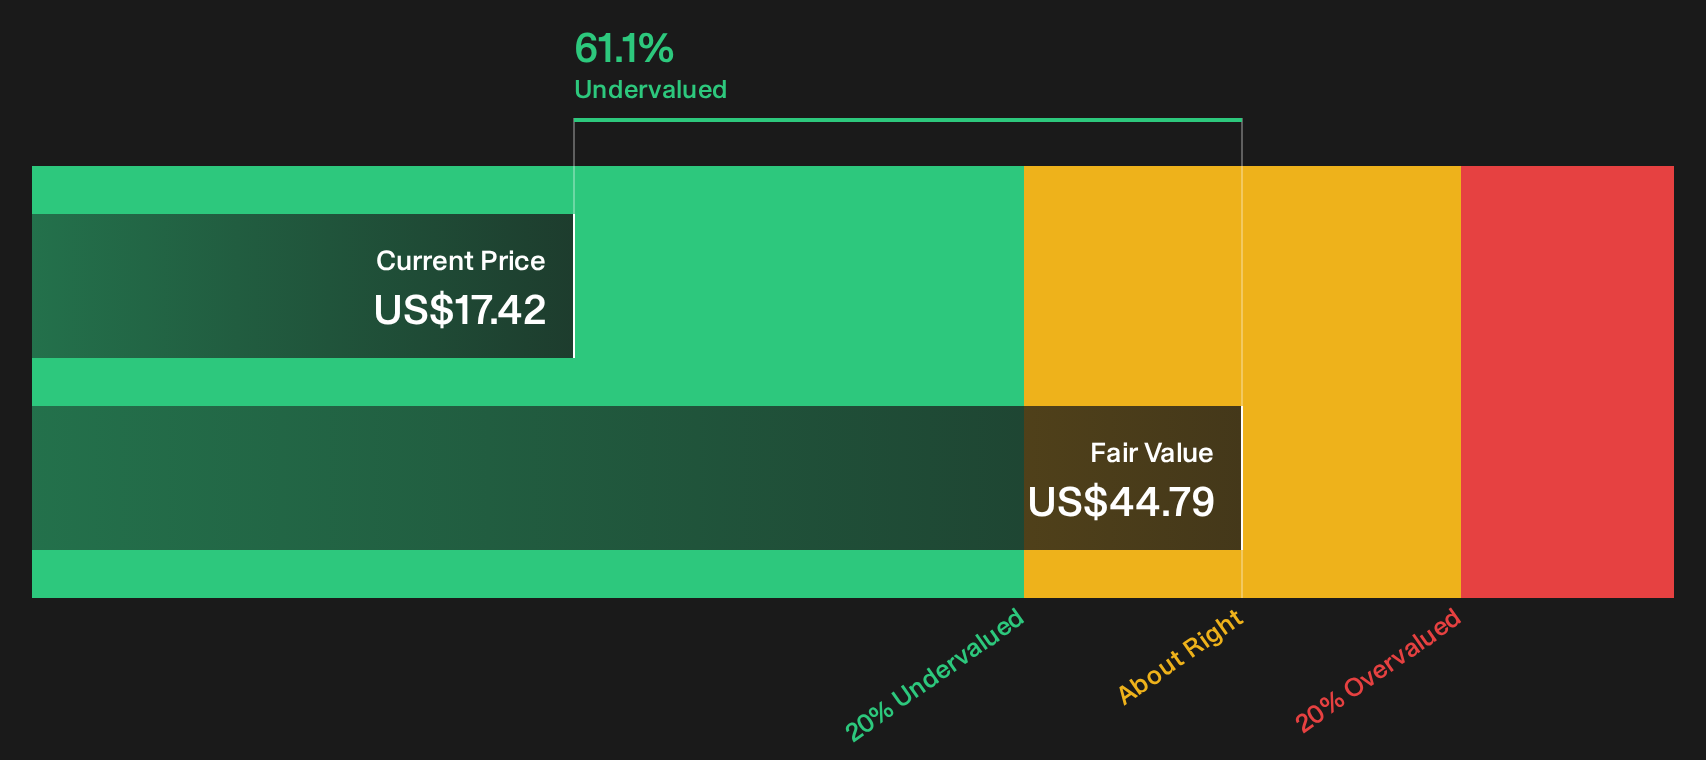
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hycroft Mining Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Hycroft Mining Holding is clearly mixed, with punchy drill results sitting alongside valuation questions and balance sheet concerns. Act quickly to review the underlying numbers, weigh both the upside potential and the specific red flags, and then ground your own view in the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Hycroft Mining Holding?
Do not stop with Hycroft Mining Holding. Use the Simply Wall St screener to pressure test your thinking and uncover fresh ideas before the market focuses on them.
- Target potential mispricing by scanning our curated list of 32 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them yet.
- Build a sturdier core for your portfolio by focusing on companies in the list of solid balance sheet and fundamentals (25 results) that show healthier financial foundations.
- Unearth underfollowed opportunities by running through the 20 high quality undiscovered gems where quality metrics point to stories the broader market may still be ignoring.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com