
Why D Wave Quantum Stock Is In Focus After Italy Quantum Computer Delivery
- D-Wave Quantum reported that its Advantage2 annealing quantum computer, funded under a €10 million agreement with Swiss Quantum Technology, has arrived in Lombardy for installation at Villa Saporiti. It will be made available to European users through the Leap cloud service once operational.
- The Italian deployment gives D-Wave Quantum a physical quantum hub in Europe, widening access for universities and enterprises. It could also support higher utilization of its QCaaS platform as research and commercial projects develop around the VoltaB1 system.
- The next step is to consider how D-Wave Quantum's Italian Advantage2 deployment could reshape the investment narrative around its QCaaS scale up.
Scan D-Wave Quantum's momentum in context alongside other quantum-focused plays with the hand-picked 25 quantum computing stocks to help you compare how different businesses are positioned around similar catalysts.
D-Wave Quantum Investment Narrative Recap
D-Wave Quantum asks you to believe that quantum optimization can move from pilots to repeat usage across logistics, manufacturing, defense and finance. The Italian Advantage2 hub, funded through the €10 million SQT agreement, leans into that view by putting hardware closer to European users. The near term swing factor still looks like whether these high value, lumpy system contracts convert into steadier QCaaS usage.
The biggest risk remains concentration in a few big deployments while operating losses stay high. If European users treat the Italian system as a showcase rather than a workhorse, recurring cloud demand may disappoint and the gap between strong technical ambition and the current small revenue base could stay wide.
Among the recent updates, the multi year extension with SkyWater Technology is the one that ties most directly into the Italy deployment. Every new Advantage2 system, including VoltaB1 in Lombardy, depends on reliable superconducting chip production and process know how, which this agreement aims to secure at SkyWater’s Minnesota fab.
For you as an investor, that manufacturing continuity feeds straight into the core catalyst and the core risk. If D-Wave Quantum can keep rolling out successive processor generations through SkyWater while filling capacity on Leap, the business has a clearer path to scaling QCaaS. Any disruption or underused hardware would quickly expose how dependent current growth is on a handful of large system deals.
D-Wave Quantum's current narrative projects revenue of US$201.1 million and earnings of US$23.0 million by 2029. These projections are based on analysts assuming yearly revenue growth of 152.9% and an earnings change of about US$271.7 million from a current loss of US$248.7 million.
Uncover why D-Wave Quantum's fair value indicates a 175% potential upside to its current price that could narrow quickly.
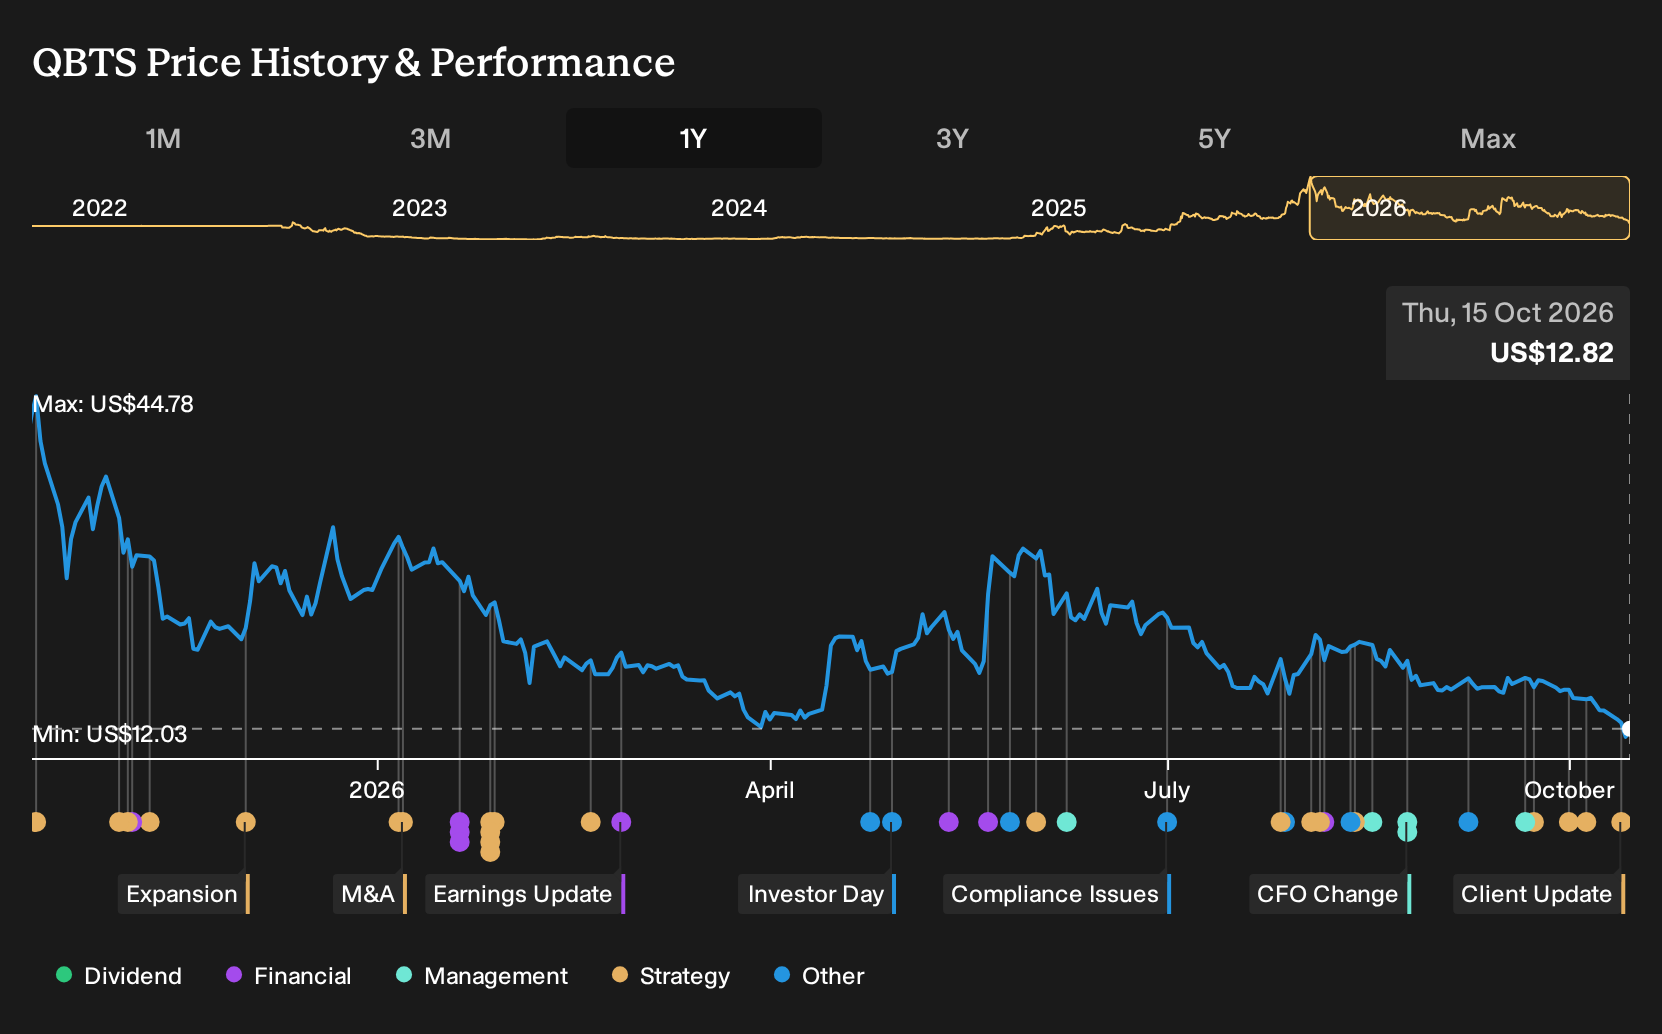
Exploring Other Perspectives
You might see the Italian Advantage2 hub as a clear capacity catalyst for D-Wave Quantum, yet the lowest analysts leaned hard into execution risk. They were only modelling about US$144.0 million of revenue and US$16.9 million of earnings by 2029, far below consensus. Use this gap to explore how your own expectations could shift after the Italy news.
Explore 7 other D-Wave Quantum fair value estimates, including one that suggests it could be worth just $20.97!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your D-Wave Quantum research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for D-Wave Quantum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate D-Wave Quantum's overall financial health at a glance.
Looking for more D-Wave Quantum sized ideas?
If the D-Wave Quantum story has you thinking about where to look next, the Simply Wall St Screener can help you widen the field without losing focus on quality.
- For investors who want to prioritize stability and downside protection, consider a 32 resilient stocks with low risk scores that score well on resilience and lower risk profiles.
- If you are hunting for stronger balance sheets that can support reinvestment and withstand setbacks, filter for companies with a list of solid balance sheet and fundamentals (25 results) to anchor your research.
- For those willing to do deeper homework in search of underfollowed opportunities, start with a 20 high quality undiscovered gems that combine quality fundamentals with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com