
Is ATS (TSX:ATS) Undervalued Following Its Zacks Rank Cut And Earnings Estimate Reset?
ATS (TSX:ATS) has just been placed on the Zacks Rank #5 list after analysts cut current year earnings estimates by 6.7% over the past 60 days. This is a shift that can sway short term sentiment.
The share price move to CA$25.68 comes after a sharp swing in sentiment, with a 4.2% 1 day share price return and a 2.1% 7 day gain following a 33.6% 90 day share price decline and a 30.9% fall in 1 year total shareholder return, which points to fading momentum despite the recent bounce and aligns with the more cautious tone from earnings estimate cuts.
Scan beyond ATS and see how it stacks up against 6 high quality undervalued stocks that analysts rate as having stronger fundamentals and potentially more resilient sentiment shifts.
ATS now trades well below where it started the year, yet still sits at a discount to analyst price targets. Has the recent rebound used up most of the easier potential upside, or is a larger move still ahead as valuation comes into focus?
Most Popular Narrative: 9.6% Undervalued
Against the last close at CA$25.68, the most followed narrative pegs ATS at a Fair Value of CA$28.39, which frames the recent share price slide as more than just a short term sentiment swing.
Although radiopharmaceutical applications are expanding and ATS is involved in isotope production projects, the high complexity and regulatory intensity of these facilities can slow project awards and ramp up timing. This can defer revenue recognition and delay the anticipated contribution to earnings.
See why 0 investors see ATS as 10% undervalued.
Result: Fair Value of CA$28.39 (UNDERVALUED)
Still, ATS faces two clear swing factors: prolonged delays on radiopharma and nuclear projects, and any stumble in its cost transformation that keeps margins subdued for longer.
Find out about the key risks to this ATS narrative.
Another View: What ATS’s P/E Is Telling You
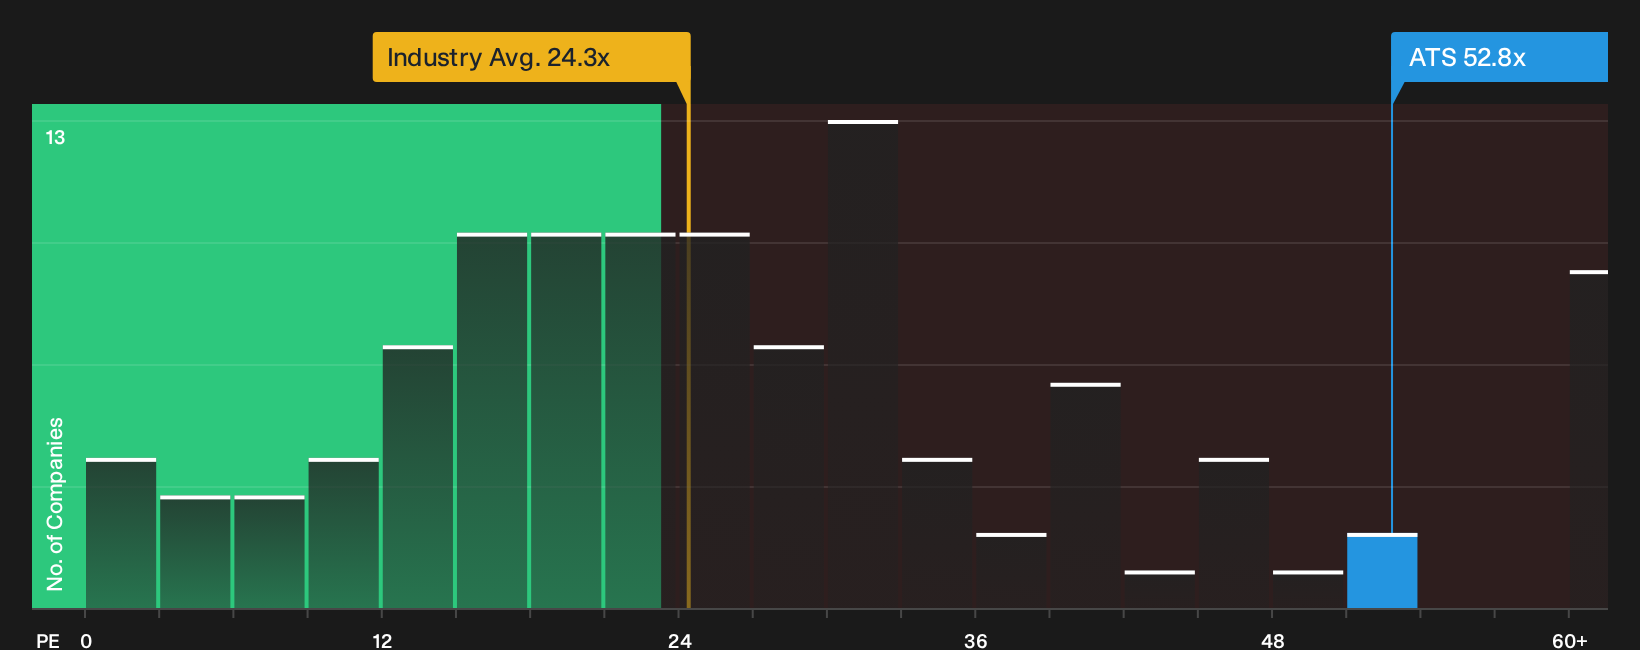
On one hand, ATS screens as undervalued against fair value estimates. On the other, the current P/E of 52.8x is much richer than the North American Machinery industry on 24.3x and the peer average of 26x, even if it sits below a fair ratio of 58.8x. Is that a sensible premium or a lot of hope priced in?
For a closer look at how that valuation gap could close, either through earnings progress or a lower multiple, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling mixed on ATS after all this information, or already leaning one way? Act quickly on the data, compare the trade offs, and ground your view in the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond ATS?
If ATS has you reassessing your watchlist, use this moment to widen the net. A broader set of ideas can sharpen your next move.
- Target steadier opportunities by scanning a 8 resilient stocks with low risk scores that align with a calmer risk profile without giving up quality.
- Hunt for stronger fundamentals through a list of solid balance sheet and fundamentals (8 results) that can better withstand earnings surprises and sentiment swings.
- Pursue early stage potential with a focused 19 elite penny stocks with strong financials before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com