
3 Asian Stocks That Could Be Trading At Discounts Of Up To 44.1%
Amidst the backdrop of global economic uncertainties and fluctuating oil prices, Asian markets have been navigating a complex landscape influenced by geopolitical tensions and inflationary pressures. Investors are increasingly looking for opportunities in undervalued stocks that could potentially offer significant returns as these markets adjust to evolving conditions. Identifying stocks trading at discounts requires careful analysis of their fundamentals, growth potential, and how they align with current market dynamics.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| XTC New Energy Materials(Xiamen)Ltd (SHSE:688778) | CN¥38.68 | CN¥75.56 | 48.8% |
| Riken Technos (TSE:4220) | ¥2391.00 | ¥4766.49 | 49.8% |
| Nissui (TSE:1332) | ¥1098.00 | ¥2153.17 | 49% |
| Kingnet Network (SZSE:002517) | CN¥15.42 | CN¥30.52 | 49.5% |
| KB Financial Group (KOSE:A105560) | ₩156700.00 | ₩304269.99 | 48.5% |
| ENN Energy Holdings (SEHK:2688) | HK$49.54 | HK$97.00 | 48.9% |
| Cuckoo Holdings (KOSE:A192400) | ₩26500.00 | ₩50923.26 | 48% |
| China Coal Energy (SEHK:1898) | HK$10.35 | HK$20.14 | 48.6% |
| China Automotive Engineering Research Institute (SHSE:601965) | CN¥13.64 | CN¥26.46 | 48.4% |
| Central Automotive Products (TSE:8117) | ¥2012.00 | ¥3900.46 | 48.4% |
Let's explore several standout options from the results in the screener.
Thai Airways International (SET:THAI)
Overview: Thai Airways International Public Company Limited, along with its subsidiaries, operates in the airline industry providing transportation services both within Thailand and internationally, with a market capitalization of approximately THB158.50 billion.
Operations: Thai Airways International's revenue is primarily derived from Air Transportation, which accounts for THB170.35 billion, followed by Business Units at THB16.93 billion and Other Activities contributing THB4.60 billion.
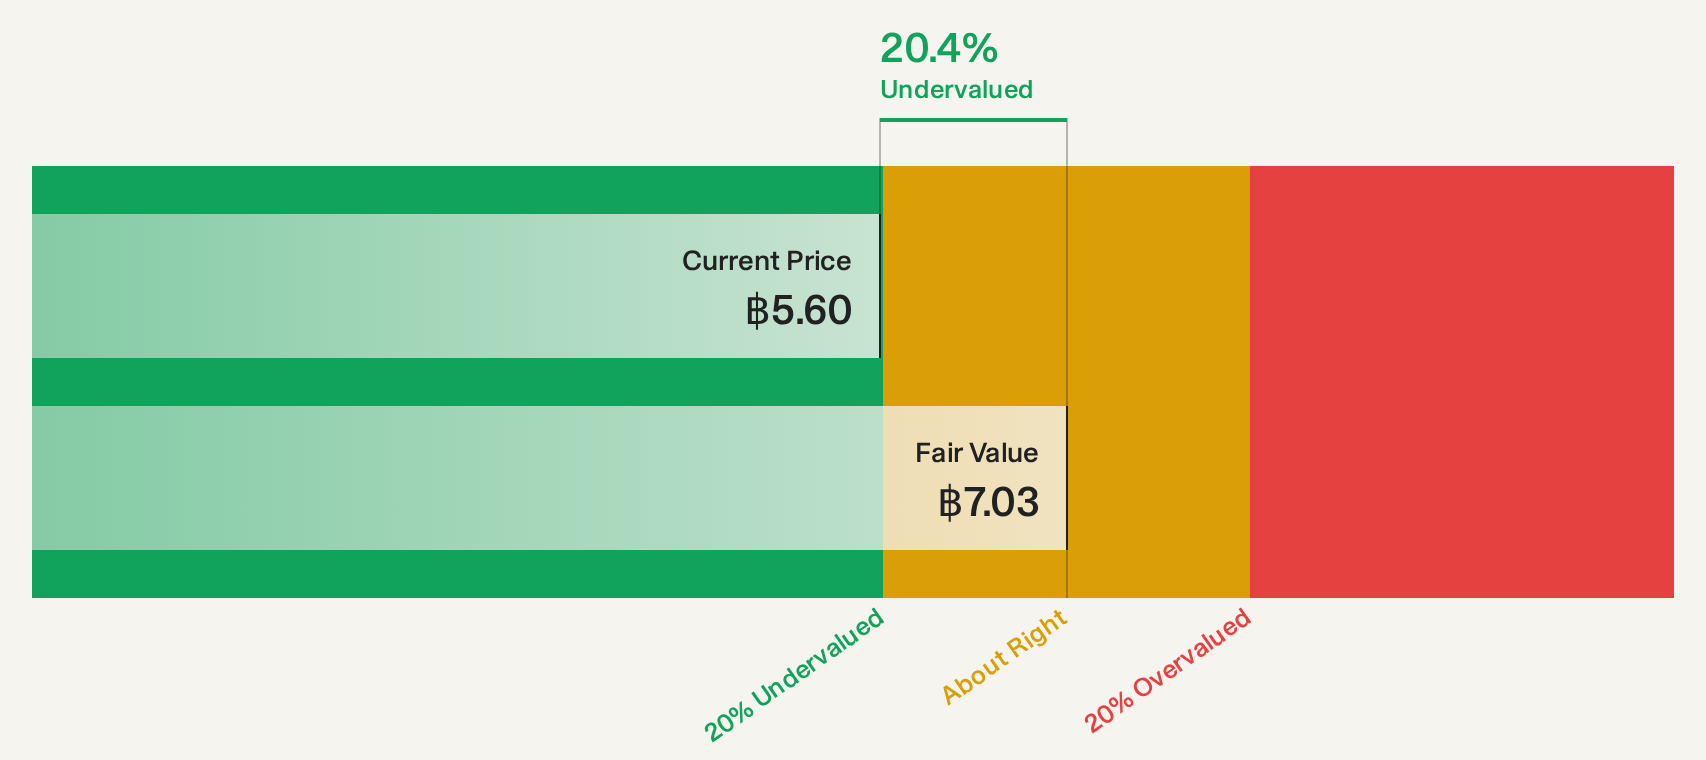
Estimated Discount To Fair Value: 20.2%
Thai Airways International is trading at 20.2% below its estimated fair value and below future cash flow value by over 20%, highlighting potential undervaluation based on cash flows. Despite a forecasted revenue growth of 6.9% annually, which is slower than the Thai market average, its return on equity is expected to be robust at 21.4% in three years. Recent executive changes amid operational challenges could impact management stability and strategic direction moving forward.
- Insights from our recent growth report point to a promising forecast for Thai Airways International's business outlook.
- Take a closer look at Thai Airways International's balance sheet health here in our report.
Wus Printed Circuit (Kunshan) (SZSE:002463)
Overview: Wus Printed Circuit (Kunshan) Co., Ltd. is involved in the production, sale, and after-sales services of printed circuit boards in China, with a market cap of CN¥223.57 billion.
Operations: The company generates revenue primarily from its Printed Circuit Board segment, which accounted for CN¥22.99 billion.
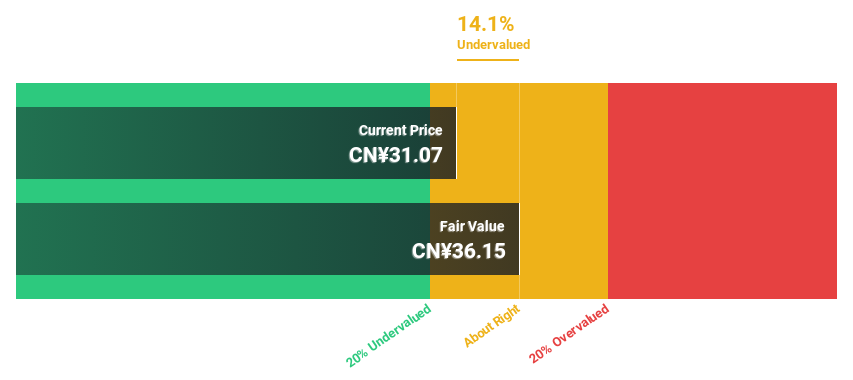
Estimated Discount To Fair Value: 44.1%
Wus Printed Circuit (Kunshan) is trading at CN¥116.18, significantly below its estimated future cash flow value of CN¥207.81, indicating potential undervaluation. The company's earnings are expected to grow by 31.6% annually, outpacing the Chinese market average of 26.7%. Despite recent shareholder activism regarding dividend proposals and a volatile share price, Wus Printed Circuit maintains high-quality earnings and strong revenue growth forecasts of 27.6% per year.
- Upon reviewing our latest growth report, Wus Printed Circuit (Kunshan)'s projected financial performance appears quite optimistic.
- Get an in-depth perspective on Wus Printed Circuit (Kunshan)'s balance sheet by reading our health report here.
Maruzen Showa Unyu (TSE:9068)
Overview: Maruzen Showa Unyu Co., Ltd. operates in the logistics sector both within Japan and internationally, with a market capitalization of ¥141.31 billion.
Operations: The company's revenue primarily comes from its Logistics Business, generating ¥130.92 billion, and its On-Site Work and Mechanical Cargo Handling Business, contributing ¥16.97 billion.
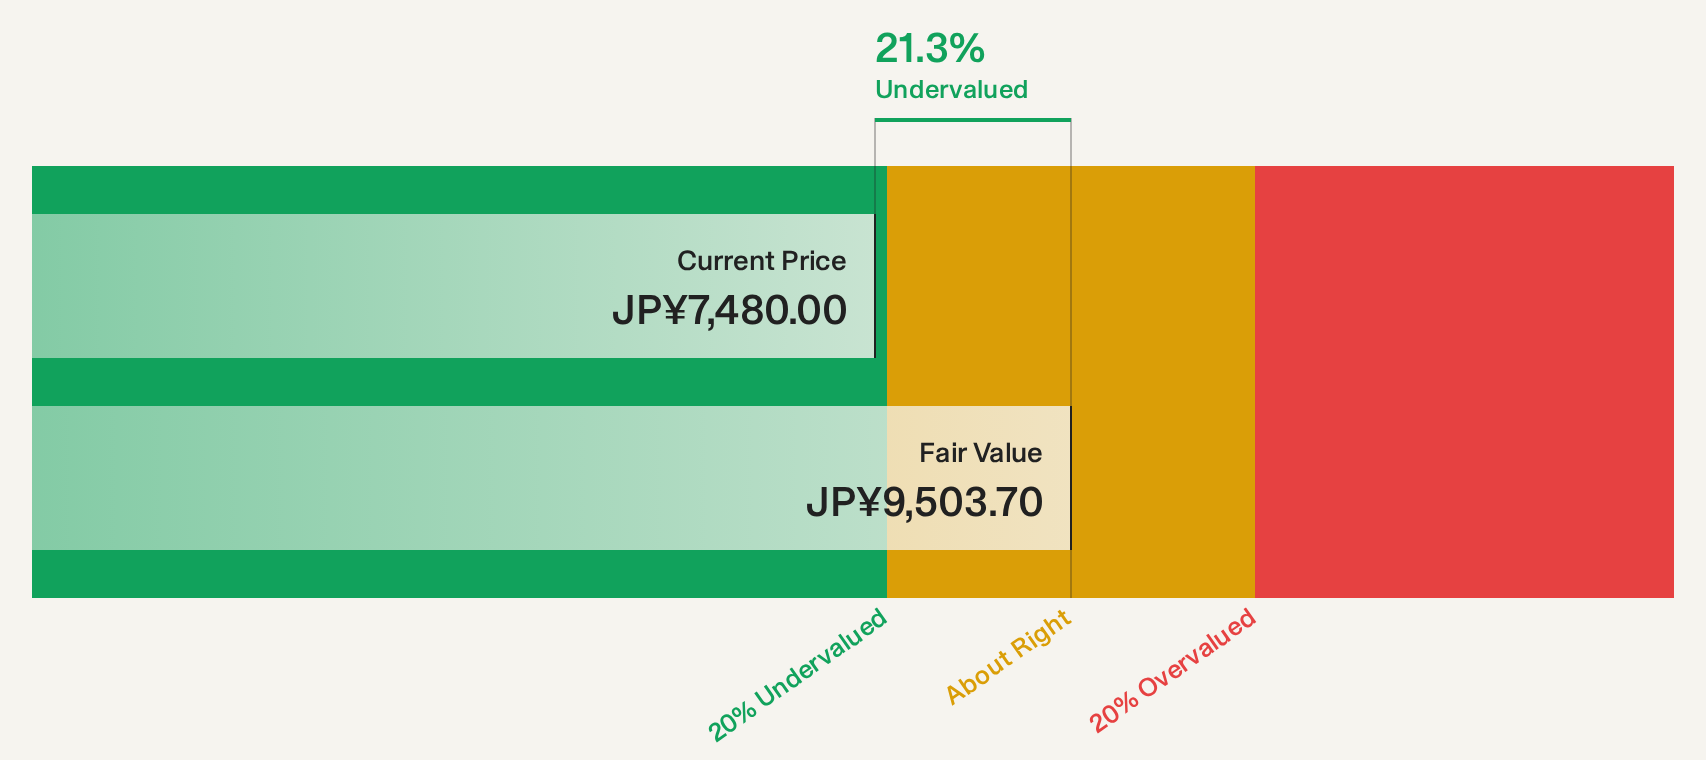
Estimated Discount To Fair Value: 21.4%
Maruzen Showa Unyu is trading at ¥3,665, below its estimated future cash flow value of ¥4,665.73, suggesting it may be undervalued. The company's earnings grew by 24.1% last year but are forecast to grow only 1% annually, slower than the Japanese market average of 9.6%. Recent corporate actions include a 2-for-1 stock split and revised dividend guidance for fiscal year ending March 2027, reflecting an unstable dividend track record despite good relative value in its industry.
- Our earnings growth report unveils the potential for significant increases in Maruzen Showa Unyu's future results.
- Unlock comprehensive insights into our analysis of Maruzen Showa Unyu stock in this financial health report.
Seize The Opportunity
- Access the full spectrum of 187 Undervalued Asian Stocks Based On Cash Flows by clicking on this link.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com