
SiteOne Landscape Supply (SITE) Extends Credit Facility, Is The Upside Still Undervalued?
SiteOne Landscape Supply (SITE) is back in focus after management extended its credit facility to 2031, tying fresh borrowing flexibility to an ongoing push on acquisitions, digital sales growth, and productivity programs.
Recent price action shows that sentiment around SiteOne Landscape Supply has been mixed, with the share price down 17.1% over the past 90 days and the year to date share price return down 28.6%. The 1 year total shareholder return has declined 26.9% and the 5 year total shareholder return is down 58.1%, hinting that investors are still adjusting their expectations even as the extended credit facility and acquisition pipeline keep the long term story in play.
Scan other building supply and industrial distributors facing similar growth-versus-volatility trade offs with our curated list of list of solid balance sheet and fundamentals (25 results)
After a share slide and a fresh credit line that gives SiteOne Landscape Supply more room to execute, the core debate tightens. Is meaningful upside still ahead, or has most of the rebound already happened in the stock price?
Most Popular Narrative: 30% Undervalued
The most followed narrative on SiteOne Landscape Supply pegs fair value at $127.08, well above the last close at $89.36, and ties that gap to a long runway of consolidation, digital growth, and margin work.
Ongoing acquisition of smaller, high-margin businesses in a fragmented market, supported by SiteOne Landscape Supply holding roughly 13% share of an estimated US$36b wholesale market and having completed 108 deals that added about US$2.2b of sales since 2014, along with a stated goal to add more than US$2b of acquired revenue over the next decade, points to further potential increases in revenue scale and EBITDA.
See why 2 investors see SiteOne Landscape Supply as 30% undervalued.
Result: Fair Value of $127.08 (UNDERVALUED)
Still, weak volumes in key Sunbelt states, along with pressure in residential and repair markets, could easily delay the margin and consolidation story for SiteOne Landscape Supply.
Find out about the key risks to this SiteOne Landscape Supply narrative.
Another View On SiteOne Landscape Supply’s Value
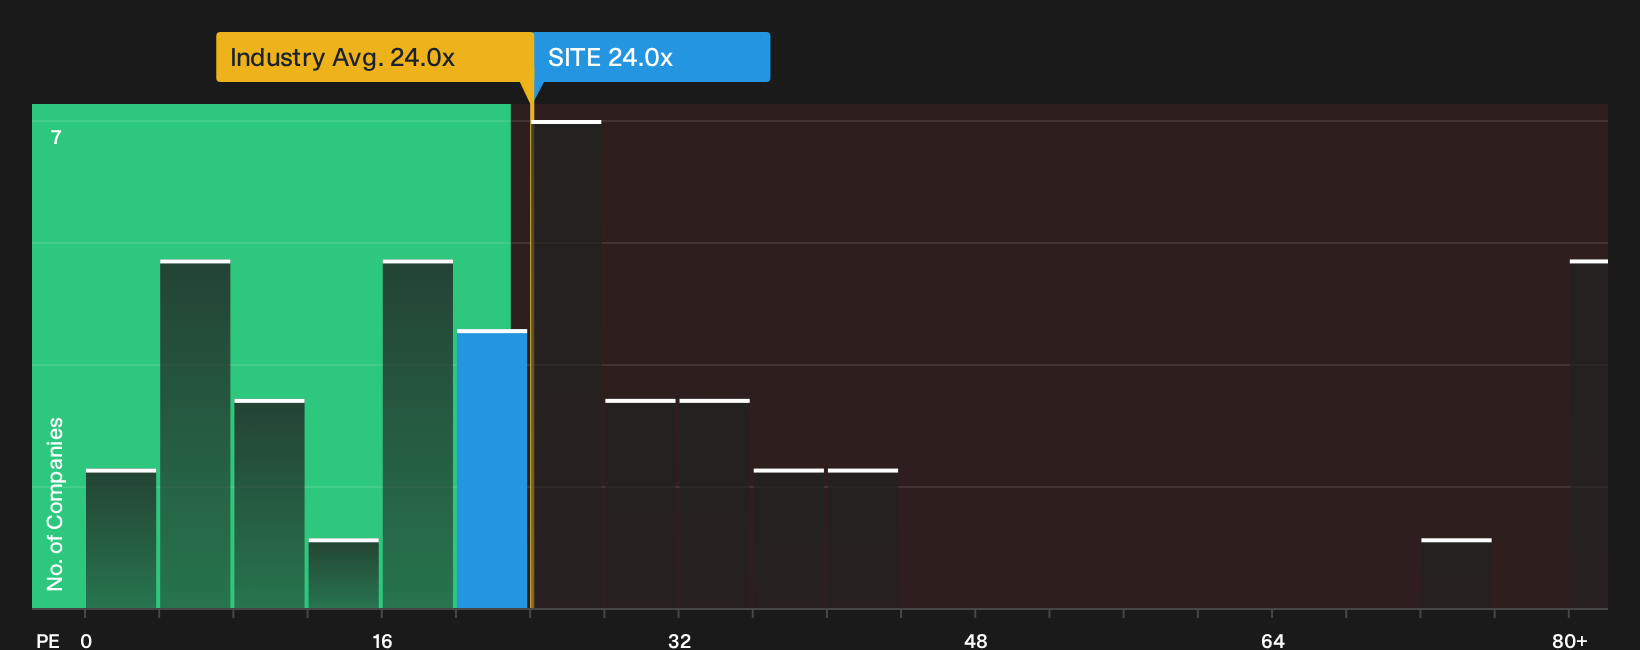
There is a twist when shifting from that narrative fair value of $127.08 to the multiples used in the Simply Wall St checks. SiteOne Landscape Supply trades on a P/E of 24x, which screens slightly expensive against a fair ratio of 23.6x, yet comes through as better value than both the US Trade Distributors industry on 24.5x and peers at 70.7x. For an investor weighing fresh capital, does that mix of mild fair ratio premium and relative peer discount feel like a margin of safety or a sign of valuation risk building?
To pressure test those earnings multiples against a fuller breakdown, it helps to look at what the numbers say in context of the wider sector and peers, then compare that with your own expectations for margins and growth from here See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece has been mixed, and that is the point. Use the numbers, stress test your own assumptions, and then see how they line up with the 3 key rewards.
Ready for more investment ideas beyond SiteOne Landscape Supply?
Do not stop with one ticker. Use the Simply Wall Street Screener to quickly surface fresh ideas that fit the kind of portfolio you actually want to build.
- Target potential mispricing by scanning a focused set of 32 high quality undervalued stocks that combine solid fundamentals with room for market expectations to catch up.
- Strengthen portfolio resilience by filtering for 32 resilient stocks with low risk scores where balance sheets and risk scores line up with a steadier ride.
- Get ahead of the crowd by hunting through 20 high quality undiscovered gems before attention and liquidity move elsewhere.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com