
Lakeland Financial (LKFN) Could Be 42% Below Fair Value On Its Dividend Update
Lakeland Financial (LKFN) just affirmed a quarterly dividend of US$0.52 per share, with investors keyed in on the ex dividend date on October 23 and the payment date on November 5.
At a share price of US$57.02, Lakeland Financial’s recent 30 day share price return is down 6.2% and the 90 day move is down 10.4%. This points to fading momentum even though year to date share price performance is slightly positive and the three year total shareholder return of 25.5% is still ahead of the one year total shareholder return, which is down 4.6%.
Compare Lakeland Financial's dividend story and recent share price moves with a curated 7 dividend fortresses that combine income potential with more resilient price trends.
Lakeland Financial looks like a solid regional bank on the surface, with steady revenue and earnings growth, yet the recent share price slide raises a sharper issue. Is this quality already fully baked into today’s valuation, or not?
Price-to-Earnings of 12.7x: Is it justified?
Lakeland Financial trades on a P/E of 12.7x, which frames the recent share price slide against what investors are currently willing to pay for its earnings.
The P/E ratio compares the share price to earnings per share. For a bank like Lakeland Financial, it is a quick way to see how the market prices the earnings stream relative to other financial institutions where profitability and balance sheet strength tend to drive sentiment.
On one side, the stock is flagged as good value compared to peers, with a P/E of 12.7x versus a peer average of 19.6x. On the other, it screens as expensive against both the US Banks industry average P/E of 11.4x and an estimated fair P/E of 10.4x. That fair ratio gives a level the market could shift toward if sentiment cools on the current earnings profile.
Explore the SWS fair ratio for Lakeland Financial.
Result: Price-to-Earnings of 12.7x (ABOUT RIGHT)
Still, Lakeland Financial faces two clear pressure points. A weaker share price trend can feed into sentiment, and any setback in earnings growth could quickly challenge that 12.7x P/E.
Find out about the key risks to this Lakeland Financial narrative.
Another View: What The SWS DCF Model Says About Lakeland Financial
The P/E conversation paints Lakeland Financial as roughly fairly priced, yet the SWS DCF model points in a very different direction. On that measure, the shares trade around US$57.02 while the estimated future cash flow value sits at US$98.09, implying the stock changes hands at a large discount.
That gap suggests the market is pricing Lakeland Financial more harshly on headline earnings than on its long term cash generation. It raises a direct question for investors: Is the DCF being too generous about future cash flows, or is the market leaning too hard on recent sentiment and relative comparisons?
Look into how the SWS DCF model arrives at its fair value.
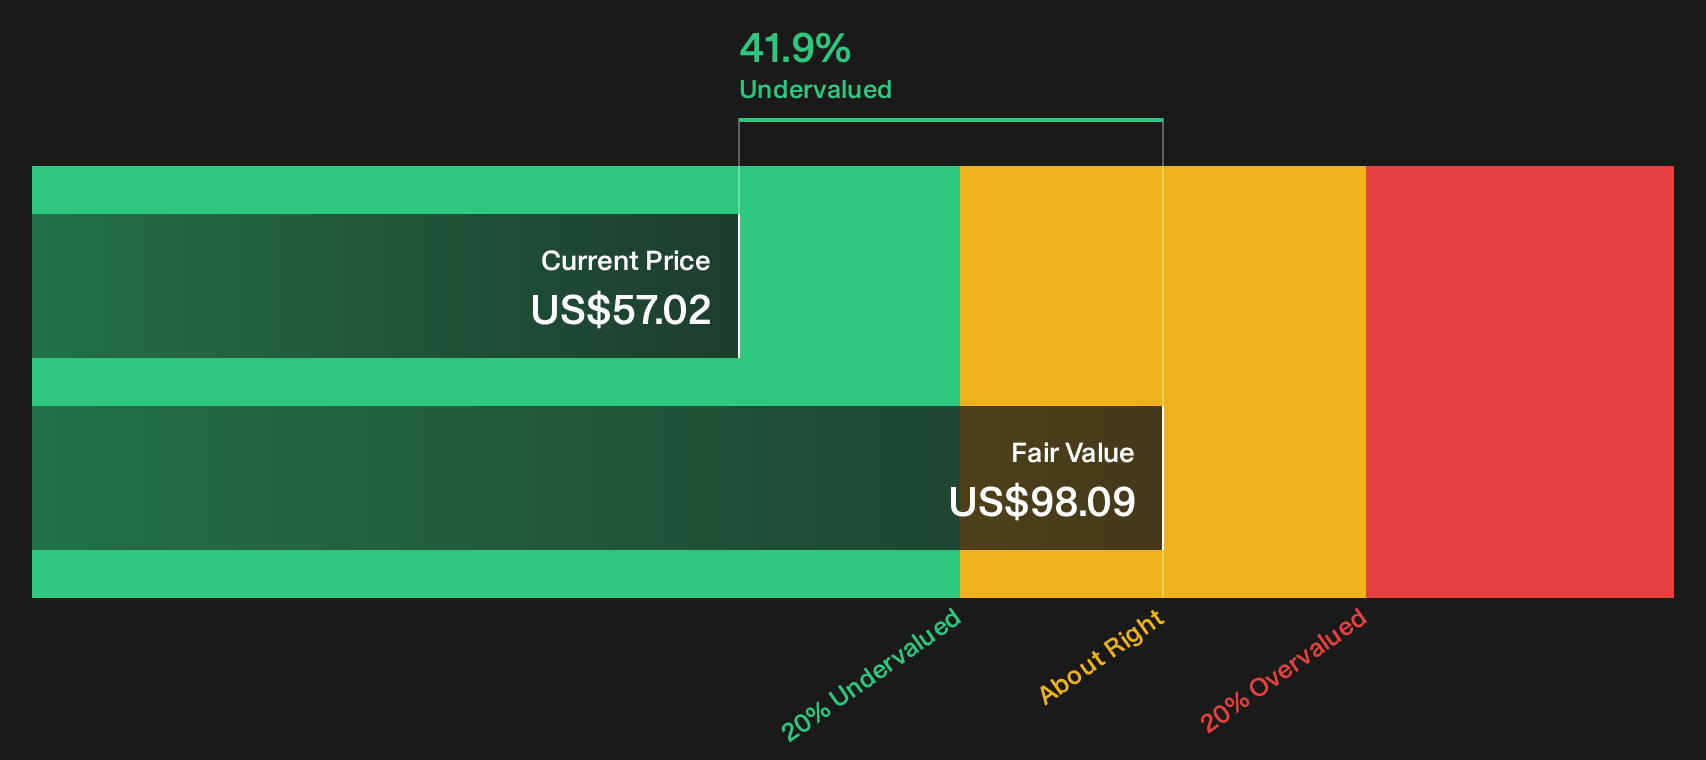
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lakeland Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Lakeland Financial’s story so far. Use the valuation and dividend data as a starting point, then pressure test the upside yourself with the 3 key rewards.
Looking for more investment ideas beyond Lakeland Financial?
If Lakeland Financial has raised your interest, do not stop here. Broaden your watchlist with fresh ideas that line up with your income, value, and risk preferences.
- Target stronger value candidates by reviewing companies that combine quality fundamentals with attractive pricing through the 32 high quality undervalued stocks.
- Boost the reliability of your portfolio by scanning financially robust businesses using the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by checking a curated 20 high quality undiscovered gems before those opportunities become crowded trades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com