
Mobility Global (MBGL) Holds Argus Support, Is The Valuation Gap Too Wide To Ignore?
Mobility Global (MBGL) is back in focus after Argus reiterated a HOLD rating, paired with mixed subratings that highlight strong industry positioning but weaker views on management quality and long term growth potential.
Against that ratings backdrop, Mobility Global’s recent trading tells a cautious story. The share price has slipped around 12% over the past month and about 15% year to date, so short term momentum has cooled. At the same time, Argus’ HOLD stance keeps attention on whether recent weakness reflects concerns around growth and management execution or simply changing risk appetite toward data driven auto services businesses.
Scan the wider field of data driven auto and mobility stocks under pressure and see which ones still show resilient fundamentals in our curated list of solid balance sheet and fundamentals (25 results).
Mobility Global runs a sizeable, data heavy business with US$1,814 million in revenue and US$205 million in net income. After a 15% slide this year, is that engine priced fairly or on sale?
DCF Check: Is Mobility Global’s $41.14 Fair Value Credible?
On Simply Wall St’s DCF view, Mobility Global carries an estimated fair value of $41.14, compared with a last close of $17.84, which points to a wide gap between the share price and the model’s view of future cash generation.
The SWS DCF model projects future cash flows for a business, then discounts those projected dollars back into today’s money using a required return. It is a cash flow driven framework, so it leans heavily on assumptions about how earnings and free cash flow progress over time rather than short term market sentiment.
Mobility Global already produces US$205 million in net income on US$1,814 million in revenue, and earnings are forecast to grow 14.43% per year with revenue projected to advance 7.1% annually. For a data focused auto services group selling mostly through subscriptions and transactions, that blend of current profitability and expected growth gives the model quite a lot of input to work with, although the recent one off $84.0 million loss and modest 2.1% current return on equity mean investors may still question how efficiently that future cash is generated.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of $41.14 (UNDERVALUED)
Still, Mobility Global’s story could be knocked off course if subscription demand softens or if questions around management execution grow louder.
Find out about the key risks to this Mobility Global narrative.
Another View on Mobility Global’s Valuation
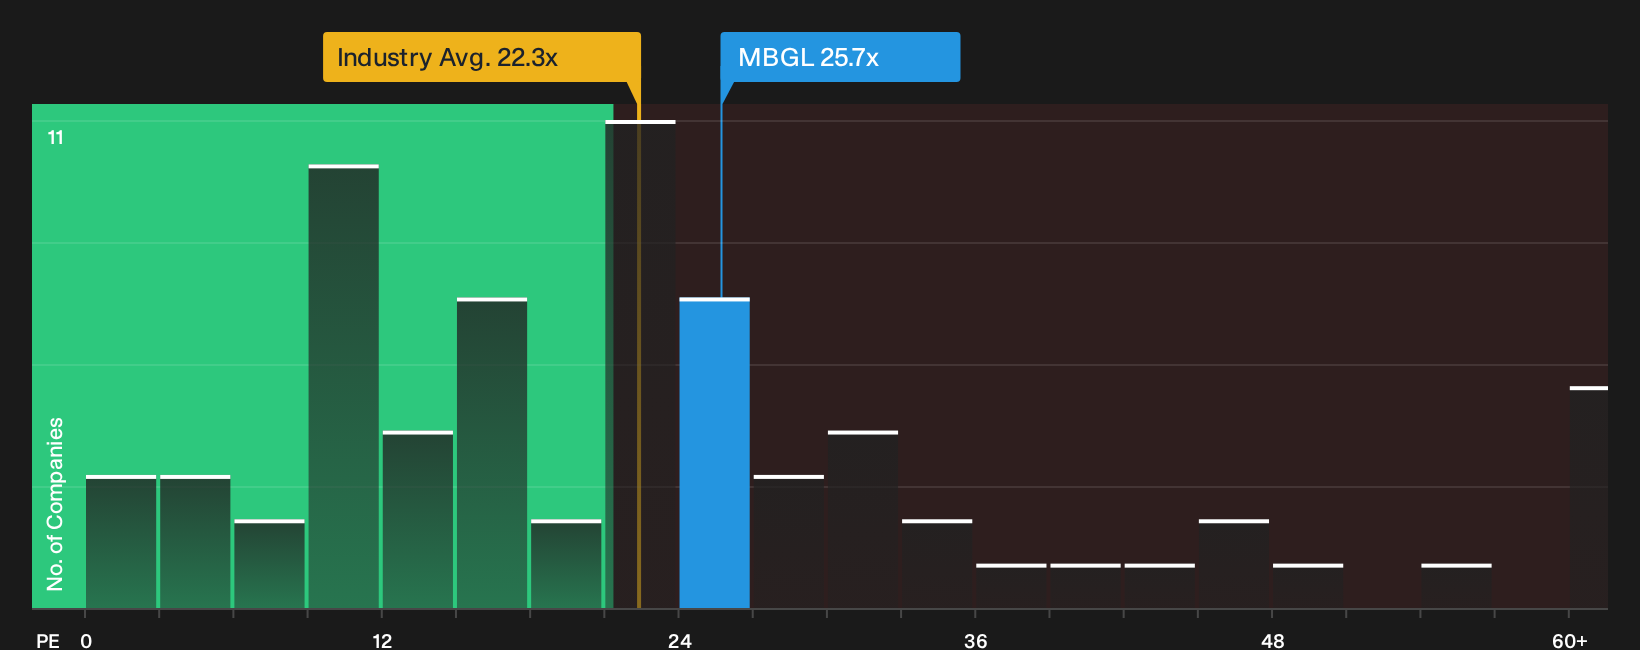
That wide SWS DCF gap makes Mobility Global look cheap, yet the market is treating it differently. The stock trades on a P/E of 25.7x, compared with 22.2x for the US Professional Services industry and 22.5x for its peer group. This points to a richer tag rather than a bargain.
A higher multiple with lower forecast earnings growth than the broader US market raises a practical question for you: is the premium price a sign that investors trust Mobility Global’s data assets more than the near term growth profile suggests, or is it a valuation risk that could unwind if expectations cool?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mobility Global for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on valuation and growth potential can cut both ways, so move quickly, review the underlying data, and weigh both the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mobility Global?
If Mobility Global has you thinking harder about valuation and quality, do not stop here. Broader opportunities can sharpen your next move and reduce blind spots.
- Zero in on potential bargains backed by earnings strength by scanning companies flagged as 32 high quality undervalued stocks.
- Focus on resilience first and filter for businesses with healthier finances through the 32 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd pays attention by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com