
How Investors Are Reacting To Wynn Resorts (WYNN) UAE Resort Plans Advance
- Officials from Ras Al Khaimah visited Wynn Resorts and other U.S. tourism hubs in 2026 to study tourism development ahead of the planned September 2027 opening of the US$5.7b Wynn Al Marjan Island resort. Management indicated that construction supply chains were functioning normally despite regional conflict and higher projected project costs.
- The roughly US$600m increase in expected spending on Wynn Al Marjan Island highlights the execution and capital allocation pressure on Wynn Resorts as it builds out a large integrated resort in a new geography. This project could reshape the mix of future earnings once operating.
- We will now look at how Wynn Resorts' higher Al Marjan project budget could influence the broader investment narrative around its expansion strategy.
Scan how Wynn Resorts compares with other tourism and travel plays by reviewing our curated list of 20 high quality undiscovered gems that may be flying under most investors' radar.
Wynn Resorts Investment Narrative Recap
For Wynn Resorts, the core belief is that a premium, destination focused portfolio in Las Vegas, Macau and Ras Al Khaimah can support healthy earnings over time despite periods of volatility. In the short term, the focus is on controlling operating costs and keeping high end visitation steady while major projects like the Encore remodel and Enclave tower move forward.
The Ras Al Khaimah visit and confirmation that Wynn Al Marjan supply chains are functioning normally help reduce one of the bigger near term worries around construction disruption. The US$600m budget uplift keeps execution risk very real, particularly given higher interest costs and labor inflation that can squeeze EBITDAR margins if demand softens.
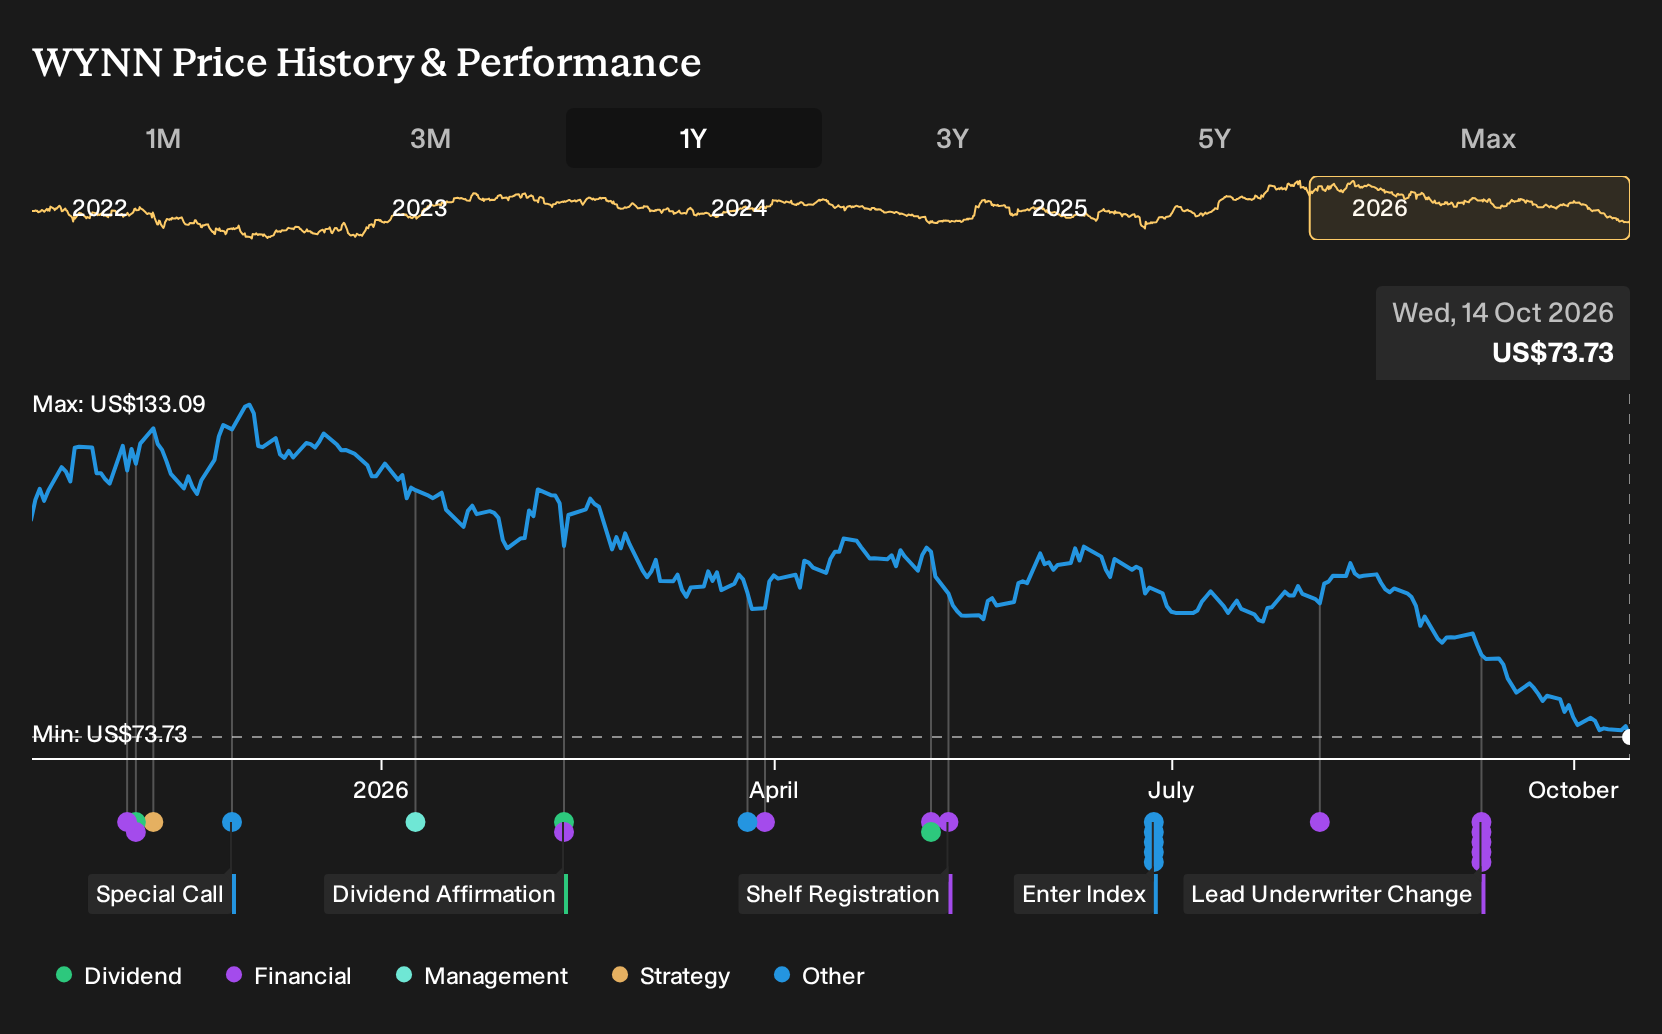
The Al Marjan Island update is the most relevant disclosure for this move in Wynn Resorts shares. Construction reportedly running on normal supply chains supports the view that the September 2027 opening target remains realistic. This matters because the resort is one of the largest potential future earnings drivers in the group.
Higher projected project costs, now about US$600m above earlier expectations, change the risk reward mix for that catalyst. Investors need to weigh the larger capital outlay against the potential for a new integrated destination to broaden Wynn Resorts cash generation, while also keeping an eye on interest coverage and the impact of any further cost creep.
Wynn Resorts' current analyst narrative points to about US$9.2b in revenue and US$582.4m in earnings by 2029, based on consensus estimates that assume roughly 7.4% yearly revenue growth and an earnings increase of about US$133.5m from US$448.9m today.
Uncover why Wynn Resorts' fair value indicates a 79% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses squarely on Wynn Resorts’ exposure to Ras Al Khaimah. The most cautious analysts were only pencilling in about US$7.9b of revenue and US$496.9m of earnings by 2029 even before this cost update. That is a much tougher stance on future cash generation. Use it as a reminder that expectations can swing widely, and explore how these different forecasts might evolve after the latest news.
Explore 3 other Wynn Resorts fair value estimates, including one that suggests it could be worth just $128.20!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Wynn Resorts research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Wynn Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wynn Resorts' overall financial health at a glance.
Looking For More Investment Ideas Beyond Wynn Resorts?
If the Wynn Resorts story has sharpened your view on risk, returns, and project execution, you can use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- For investors who want income with staying power, consider 7 dividend fortresses that combine higher yields with balance sheets that can better support regular payouts.
- If capital protection sits high on your priority list, review 32 resilient stocks with low risk scores that score well on financial strength and business stability metrics.
- For those hunting for quality that is not yet crowded, look across 20 high quality undiscovered gems where fundamentals may not fully match current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com