
NextEra Energy (NEE) Proposes Legal Settlement, Is It Still Undervalued?
NextEra Energy (NEE) is back in focus after disclosing a proposed settlement of shareholder derivative litigation that combines governance reforms with a US$15.5 million insurer-funded payment to the utility.
The legal proposal lands as NextEra Energy shares trade at US$78.37, with the price down 12.29% on a 90 day share price return and 3.99% over 30 days, even though the 3 year total shareholder return of 60.92% points to a much stronger longer run story. Recent attention has shifted toward the Dominion Energy acquisition process, the upcoming Q3 earnings release expected on 21 October 2026, and the governance settlement. Together, these factors are shaping how investors reassess both growth potential and legal or regulatory risk around the stock.
Position your portfolio for the same kind of earnings and regulatory catalysts driving interest in NextEra Energy by reviewing our hand picked list of 32 resilient stocks with low risk scores.For NextEra Energy, the recent pullback sits awkwardly beside solid earnings growth and a major acquisition on the horizon. Is the price now tracking business reality, or just a sentiment swing before the next results and merger updates?
Most Popular Narrative: 16% Undervalued
Against NextEra Energy's last close at $78.37, the most followed thesis on Simply Wall St points to a fair value of $93.71. This frames the current pullback as a discount rather than a warning signal.
The proposed NextEra Energy and Dominion Energy merger should not be viewed as a traditional utility consolidation alone. In my opinion, the strategic value is much larger because Dominion gives NextEra direct exposure to one of the most important electricity-demand markets in the world: Northern Virginia’s data-center corridor.
See why 48 investors see NextEra Energy as 16% undervalued.
Result: Fair Value of $93.71 (UNDERVALUED)
Still, this bullish fair value story can be knocked off course if regulators push back harder on the Dominion merger or if integration costs hit earnings harder than expected.
Find out about the key risks to this NextEra Energy narrative.
Another View On NextEra Energy's Value
The fair value narrative around NextEra Energy leans on a community estimate of $93.71, yet the SWS DCF model lands much closer to the current quote. On that measure, the shares at $78.37 sit just above a future cash flow value of $77.25, which points to a stock that is roughly fully priced rather than clearly cheap. If one method signals a discount and the other looks closer to fair, which story do you give more weight to when real money is on the line?
Before leaning too heavily on either lens, it helps to see exactly how the cash flow math was built in our DCF model, and where small changes in assumptions could tilt the result toward opportunity or risk. Look into how the SWS DCF model arrives at its fair value.
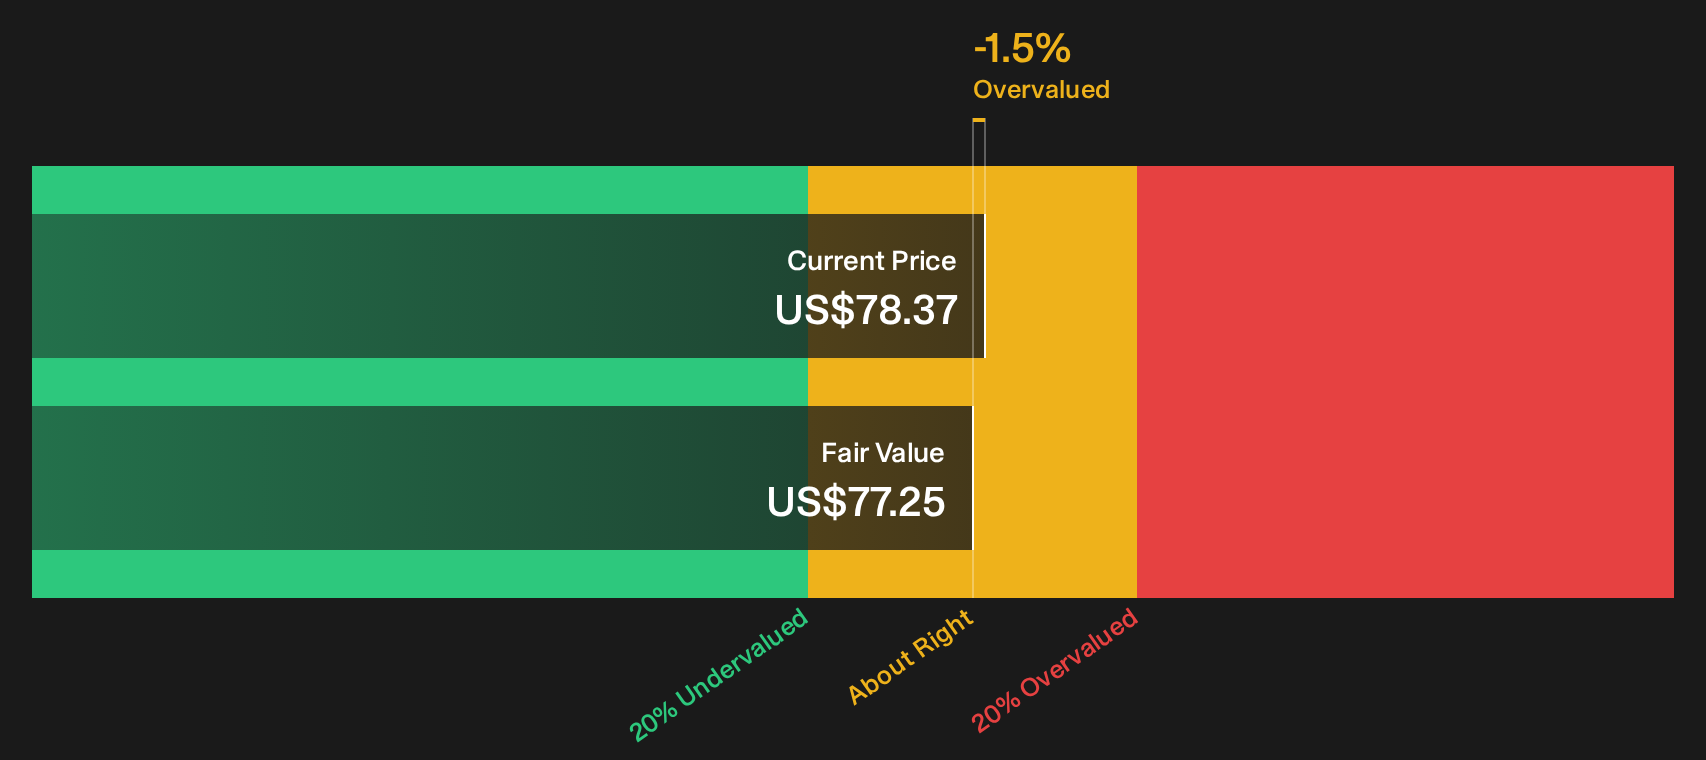
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NextEra Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on NextEra Energy's valuation and legal backdrop are clear. Consider your options while the narrative is still forming and decide where you stand by reviewing the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond NextEra Energy?
If you only watch NextEra Energy, you risk missing other opportunities that match your risk tolerance, income needs, and return expectations across the wider market.
- Target dependable income streams by reviewing 7 dividend fortresses that focus on steady payouts for investors who want yield front and center.
- Hunt for potential mispriced opportunities through the 32 high quality undervalued stocks that filters for strong fundamentals at prices that may look more forgiving.
- Strengthen your downside protection with the list of solid balance sheet and fundamentals (25 results) that highlights businesses built on healthier cash and debt profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com