
What Hana Financial Group Holders Got Right
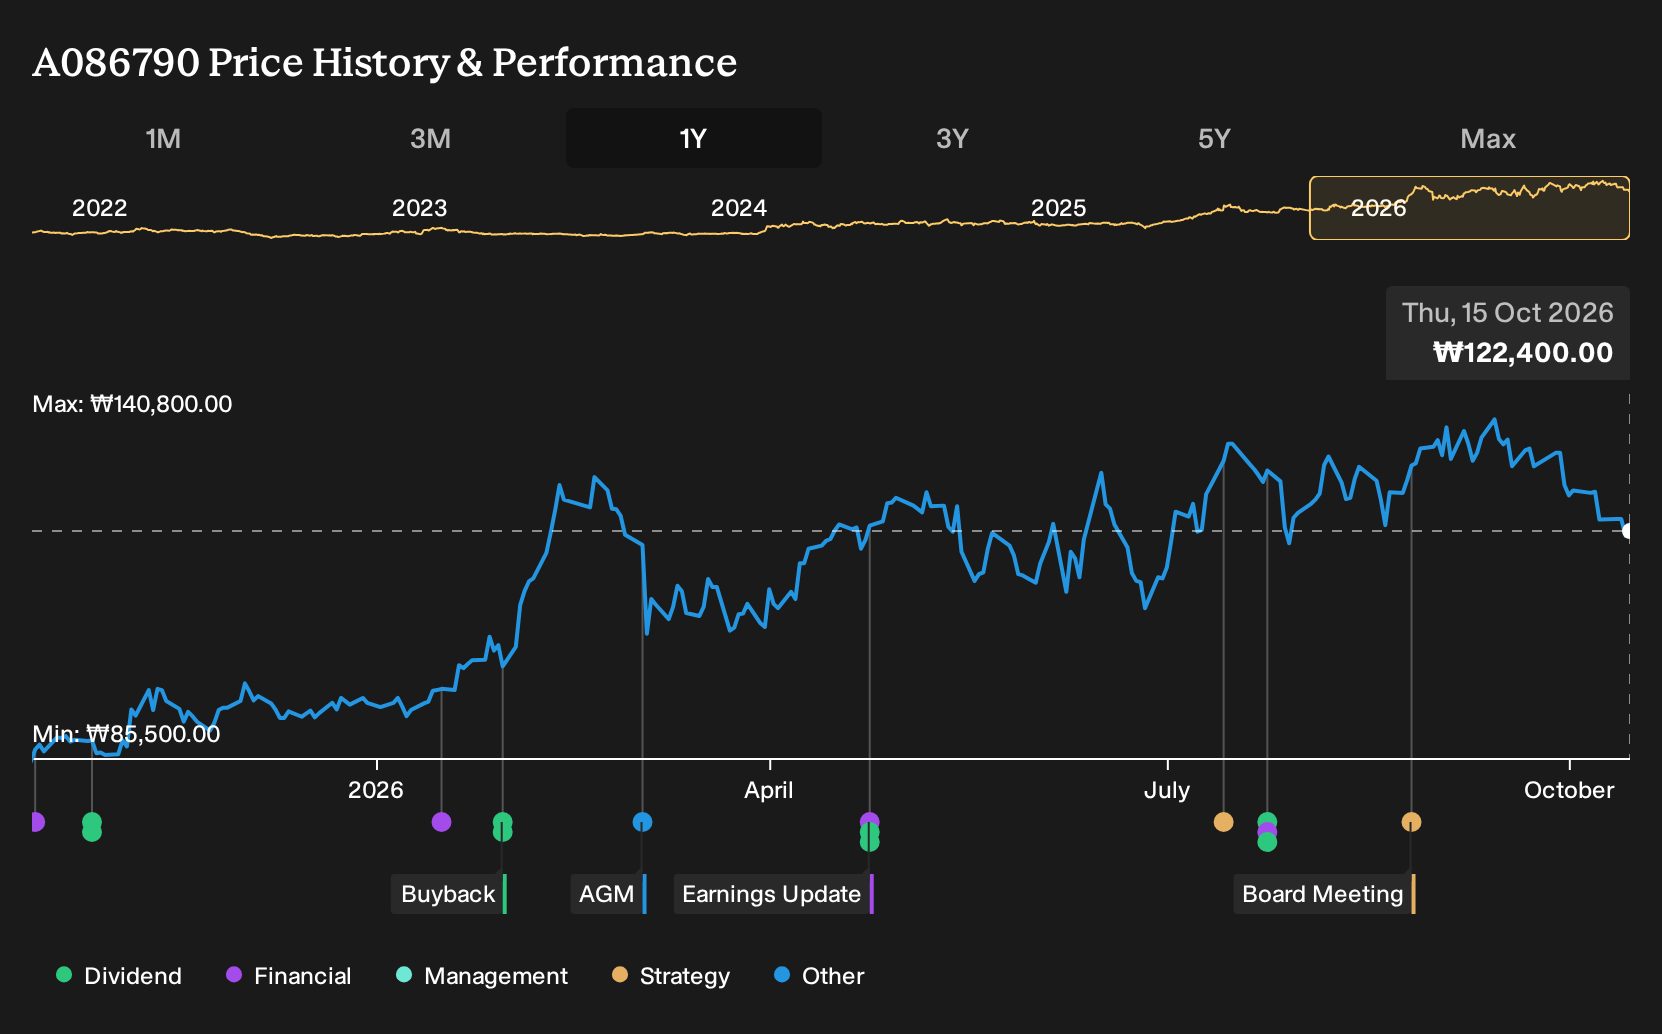
Hana Financial Group’s latest report showed higher total revenue and net income in Q2 2026 than a year earlier, but with a slimmer net margin as costs reduced profitability. For Hana Financial Group shareholders, the return over the past year was 45.8%, including dividends. If you had been weighing a purchase back in October 2025, what assumptions about digital growth, demographics and valuation would you have needed to accept before any of this was on record?
If the move has made Hana Financial Group harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Hana Financial Group Stories Investors Faced
The shares cost ₩86,700 at the start of the period, so anyone looking at Hana Financial Group had to decide which future seemed more reasonable.
On the optimistic side, one camp saw digital growth reshaping Asia, with a Fair Value of ₩106,448. This was a price implied by assumptions rather than a given outcome. That scenario required believing in 2.0% annual revenue growth and profit margins reaching 36.4% on a 7.9x future P/E.
A more cautious view put Fair Value at ₩65,500 and focused on pressure from fintech rivals and aging demographics. That story emphasized the risk that domestic lending concentration, rising regulatory costs and higher delinquency ratios would keep profitability under strain.
What The Results Changed For Hana Financial Group
The clearest new fact was Q2 2026 performance. Hana Financial Group reported total revenue of ₩8,715,490m and net income of ₩1,149,492m, both above Q2 2025. Net margin slipped from 15.3% to 13.2%. The higher revenue and profit lent some support to the optimistic growth story, while the thinner margin kept the cautious profitability case alive. Overall, the evidence cut both ways.
The episode turned on profitability quality rather than just size. When you weigh any bank, check whether margin trends confirm the growth story or quietly pull in the other direction.
What Hana Financial Group’s Price Is Asking You To Believe Now
Hana Financial Group now trades at ₩122,400. The selected Narrative argues that its Fair Value sits above this level and leans on fee income, digital projects and nonbank units to explain why the recent 45.8% return over the past year might still leave room for that thesis.
For anyone paying today’s price, the key test is whether Hana Financial Group can keep growing fee based earnings while holding firm on capital discipline and asset quality so that this supported assumption stays intact long enough for the Narrative’s higher figure to be reached.
"Institutionalized shareholder return targets, including a total shareholder return goal of at least 50% of earnings and a commitment to grow total cash dividends by at least 10% each year until a 40% payout ratio is reached, together with ongoing buybacks, are expected to drive higher cash returns per share and can support the valuation multiple on future earnings."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 24% below our estimate - targets higher sales by adding boutiques and enhancing mobile shopping features.
- Company 2 - 49% below our estimate - wins multi-year public contracts bundling design, construction and ongoing technical maintenance.
- Company 3 - 33% below our estimate - expands nutrition offerings through new product development and deeper export market penetration.
Those are three of them. See every one of the 202 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com