
Did PowerTitan 3.0 Win Just Shift ON Semiconductor's (ON) Investment Narrative?
- Onsemi reported that Sungrow adopted its latest EliteSiC silicon carbide hybrid power module and high density power integrated modules for the PowerTitan 3.0 utility scale energy storage platform, targeting inverter efficiencies that are 0.4% higher than the prior generation and supporting power conversion units up to 450 kW.
- This design win points to deeper integration of onsemi’s EliteSiC technology into large battery energy storage systems, which directly aligns with the firm’s focus on higher value power solutions and intensive collaboration with key industrial customers.
- We will now look at how this PowerTitan 3.0 EliteSiC win could influence onsemi's investment narrative around differentiated power technologies.
Scan beyond ON Semiconductor to see which grid and storage players are already lining up for the next energy build out with the curated 43 power grid technology and infrastructure stocks
ON Semiconductor Investment Narrative Recap
To own ON Semiconductor, you need to believe the pivot to higher value power and sensing products will continue to scale across autos, industrial applications and AI infrastructure. The Sungrow PowerTitan 3.0 win fits cleanly into that story, since it pushes EliteSiC deeper into real world grid level deployments rather than leaving it primarily as a spec sheet product.
In the near term, the key swing factor is whether demand in autos, industrial applications and data centers is strong enough to keep fabs tightly loaded and protect the margin structure management has built through Fab Right actions. The biggest risk is a softer order book, which could leave utilization below plan. This Sungrow deal supports the long-term strategy but does not materially change that short-term risk.
The recent focus on AI data center and power infrastructure makes this Sungrow update more notable in light of management’s 2030 AI server and data center addressable market estimate. ON Semiconductor is directing its silicon carbide and power platforms toward grid to processor use cases, and Sungrow’s utility scale energy storage effectively represents the grid side of that chain.
For investors, the connection is execution. Design wins such as PowerTitan 3.0 show the firm placing EliteSiC into complex, high power systems where efficiency gains of 0.4% and support for 450 kW units directly affect operating costs. The operational challenge is to replicate this across more customers while keeping factories sufficiently utilized to support the targeted margin profile.
How the Sungrow win lines up with ON Semiconductor's forecasts
ON Semiconductor's narrative projects US$9.0b revenue and US$2.5b earnings by 2029. Analysts are assuming revenue growth of 13.3% per year and earnings rising by about US$1.9b from US$630.2m today to reach that 2029 consensus level.
Discover why ON Semiconductor's fair value indicates a 42% potential upside to its current price, which could be realized sooner than many investors expect.
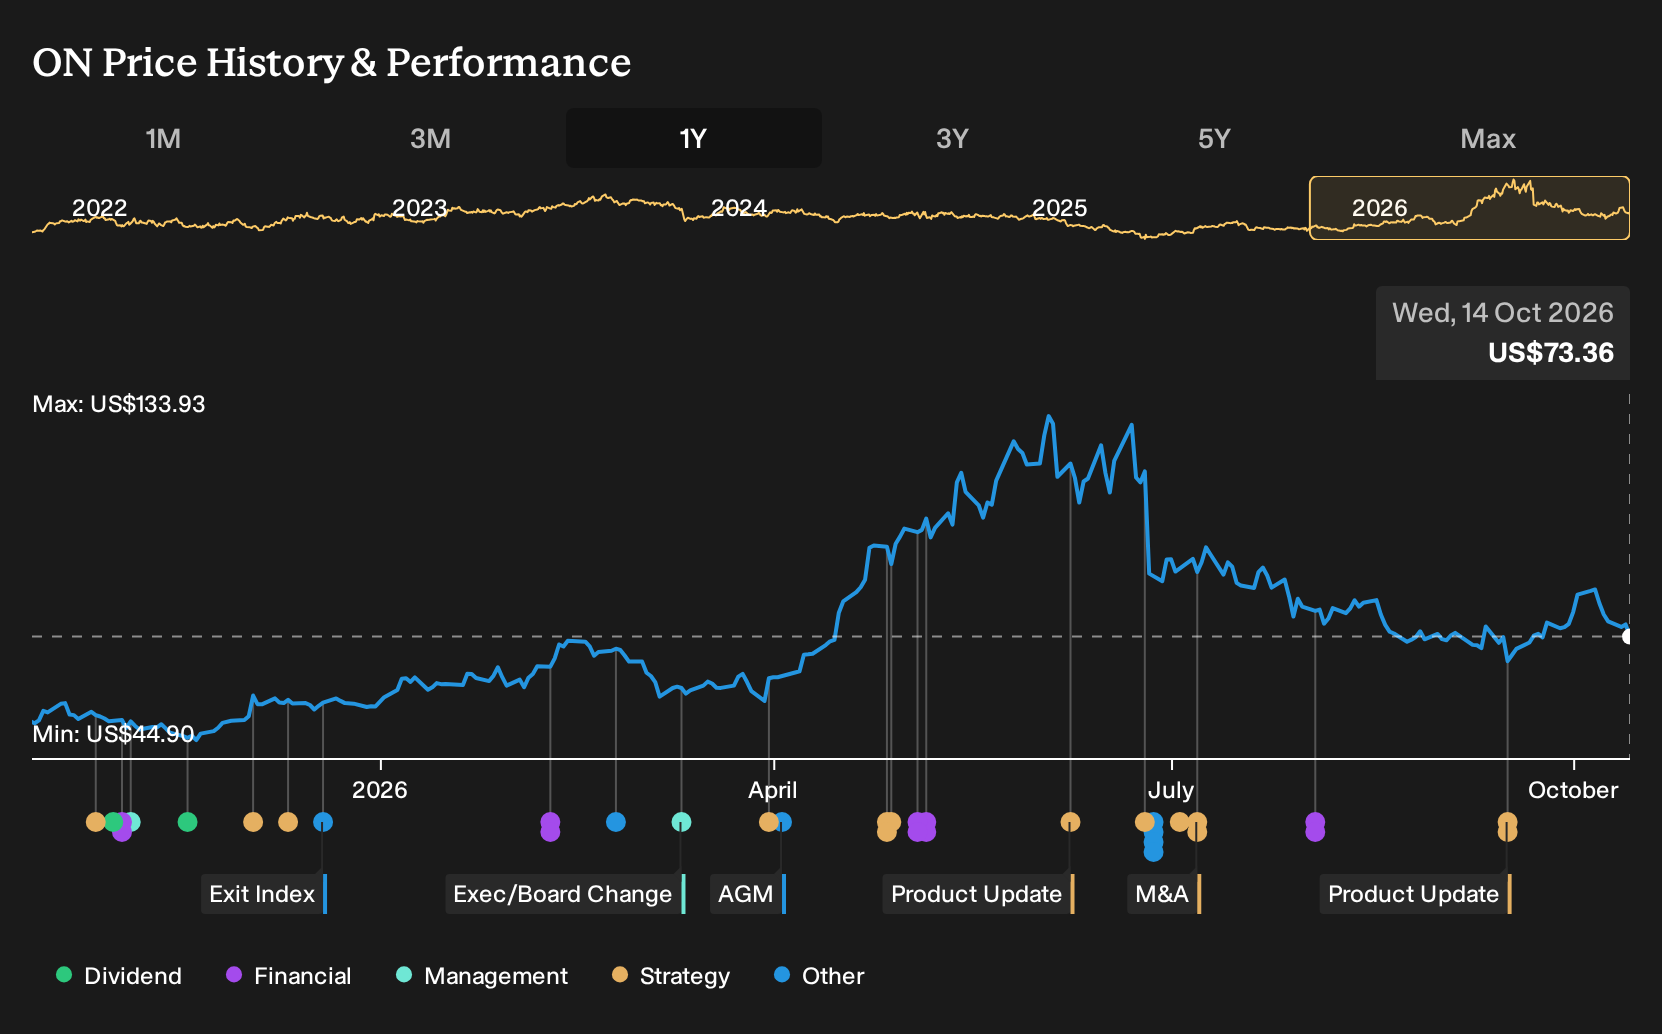
Exploring Other Perspectives
Some of the most optimistic analysts already model ON Semiconductor reaching about US$10.0b of revenue and US$3.0b of earnings by 2029, versus consensus at US$9.0b and US$2.5b. You now have a fresh SiC grid win with Sungrow that none of those forecasts include yet, so viewpoints could shift. Explore both sides.
Explore 3 other ON Semiconductor fair value estimates, including one that suggests there could be as much as 92% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ON Semiconductor research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ON Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ON Semiconductor's overall financial health at a glance.
Looking for more investment ideas beyond ON Semiconductor?
If the ON Semiconductor story has sharpened your interest in power, grids and cash generative hardware, it can help to widen the lens and compare it with other opportunities that share similar financial strengths or income profiles.
- For investors who want potential mispricing combined with solid fundamentals, scan through 32 high quality undervalued stocks and see which businesses the screener flags as quality at a discount.
- If capital preservation and steadier profiles matter more to you than headline growth, focus on companies highlighted in the 32 resilient stocks with low risk scores and see which resilient balance sheets and earnings profiles stand out.
- When you care about robust finances backing up the equity story, filter for companies with healthier leverage and coverage using the list of solid balance sheet and fundamentals (25 results) to identify sturdier balance sheets that may complement higher volatility holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com