
Diamondback Energy (FANG) Is Drawing Fresh Attention, What Is Behind It?
Diamondback Energy (FANG) is drawing fresh attention after positive earnings estimate revisions ahead of its November 2, 2026, report, combined with supportive analyst commentary following recent quarterly results.
Recent trading has been choppy for Diamondback Energy, with the share price down 6.63% over the past 30 days but still up 29.65% year to date at US$197.51. That shorter term pullback contrasts with a 45.06% 1 year total shareholder return and a 124.07% 5 year total shareholder return. Together, these figures indicate that momentum has cooled recently but remains strong over a longer horizon as investors weigh earnings optimism against changing risk perceptions.
Scan other energy producers showing similar estimate momentum and analyst interest with our curated list of 32 high quality undervalued stocks alongside Diamondback Energy.
Short-term momentum has cooled while analyst targets and intrinsic value models indicate levels above US$197.51. Where does fair value for Diamondback Energy really land within that gap?
Most Popular Narrative: 16% Undervalued
Against the last close at $197.51, the most followed narrative on Diamondback Energy points to a fair value of $234.52, so the current quote sits at a clear discount based on that framework.
Ongoing consolidation in the Permian Basin, with Diamondback Energy positioned as a consolidator that has already integrated large acquisitions and realized lower lease operating expense through automation and pump by exception, supports further scale driven synergies that can help sustain EBITDA margins and free cash flow. Consistent operational efficiency improvements, including record low drilling cost per foot in zones like Wolfcamp D and progress toward sub $400 per foot Barnett wells, point to durable cost reductions that can support resilient net margins and free cash flow generation.
See why 78 investors see Diamondback Energy as 16% undervalued.
Result: Fair Value of $234.52 (UNDERVALUED)
Still, heavy insider share sales and higher water and power costs in the Permian could pressure Diamondback Energy’s margins and weaken confidence in the case for undervaluation.
Find out about the key risks to this Diamondback Energy narrative.
Another View: Valuation Signals From P/E
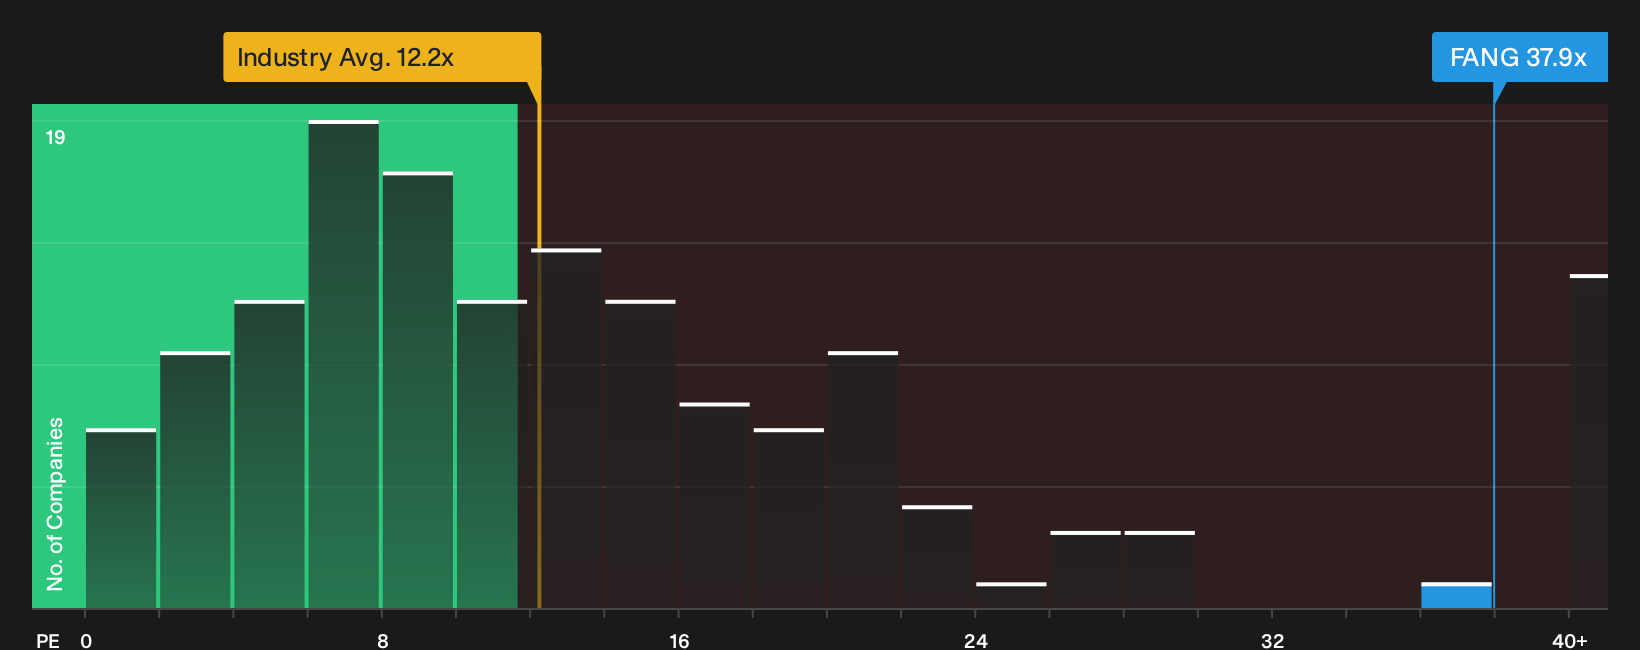
There is a very different picture when pricing Diamondback Energy on earnings. The shares trade on a P/E of 37.9x, while the US Oil and Gas group sits near 12.2x and the peer set around 12.3x. The fair ratio sits lower at 24.3x, which points to meaningful valuation risk if sentiment cools.
That gap on earnings leaves a simple question. Is the premium a fair price for the current story, or are you paying up for expectations that may already be in the rear-view mirror, as the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Diamondback Energy can feel confusing. Move quickly from headline noise to your own conclusion by weighing the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Diamondback Energy?
Do not stop your research with Diamondback Energy alone. Broaden your watchlist and pressure test your thesis using focused stock ideas built from the Simply Wall Street screener.
- Target higher income potential and stress test your yield expectations with a curated pool of 7 dividend fortresses that already clear strict payout and balance sheet filters.
- Search for quality at a sensible entry point by scanning a 32 high quality undervalued stocks that combine robust fundamentals with pricing that still leaves room for upside.
- Spot opportunities others may be missing and widen your opportunity set with a 20 high quality undiscovered gems that rarely make it into headline coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com