
Martin Marietta Materials (MLM) Following Share Price Weakness, Fair Value Stays In Focus
Martin Marietta Materials (MLM) has drawn investor attention after recent share price weakness. The construction materials supplier trades around US$471, with returns over the past month and past 3 months both showing double digit declines.
That recent weakness comes after a tougher stretch for Martin Marietta Materials, with the share price down 5.95% over the past month and 18.34% over 3 months, while the 1-year total shareholder return is down 25.88% despite still positive 3-year and 5-year total returns.
Look beyond Martin Marietta Materials to see how other construction and infrastructure suppliers are pricing in similar pressure points with our hand picked list of solid balance sheet and fundamentals (25 results)
After a drop of more than 25% over the past year, the question around Martin Marietta Materials has flipped. Is most of the value reset now behind the stock, or is the real upside still in front of you as the valuation case unfolds?
Most Popular Narrative: 6.5% Undervalued
On the latest numbers, the most followed valuation narrative pegs Martin Marietta Materials at a Fair Value of $503.78 versus a last close of $471.10. This frames recent share price weakness as a discount rather than a premium.
Although Martin Marietta Materials is building a larger aggregates and lime platform, the expected about $50 million energy and diesel headwind in 2026, including a $20 million to $25 million drag in Q2, risks becoming a recurring cost pressure that keeps reported net margins below what current earnings expectations imply.
See why 0 investors see Martin Marietta Materials as 6% undervalued.
Result: Fair Value of $503.78 (UNDERVALUED)
Still, if the Lhoist North America combination delivers the planned $350 million pretax cash flow uplift and heavy nonresidential demand holds up, the bearish Martin Marietta Materials narrative could unravel.
Find out about the key risks to this Martin Marietta Materials narrative.
Another View: What Martin Marietta Materials Looks Like On Earnings Multiples
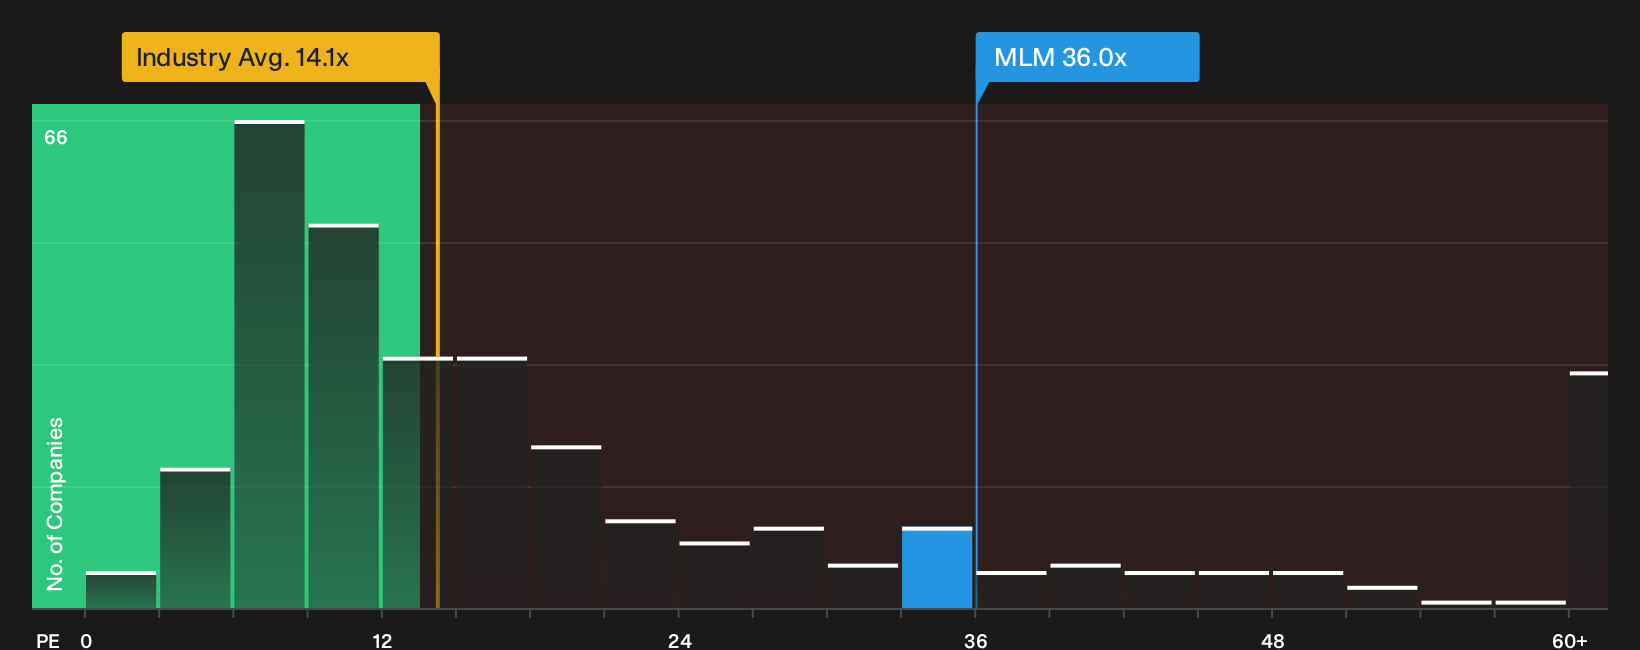
That 6.5% discount to Fair Value tells only one story. On P/E, Martin Marietta Materials trades at about 36x earnings, roughly double the US Basic Materials peer average of 18.4x and well above its own fair ratio of 23x. That premium points to real valuation risk if sentiment cools again.
For a closer look at how that earnings multiple could reset over time, and what it might mean for the share price, see the full breakdown in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Martin Marietta Materials is clearly mixed right now, so move quickly, review the underlying data for yourself, and weigh both the upside and the downside using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Martin Marietta Materials?
If Martin Marietta Materials has raised fresh questions for you, broaden your watchlist now and benchmark it against other opportunities before the next wave of price moves.
- Target resilient balance sheets and dependable fundamentals by scanning our list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispriced quality by reviewing the 32 high quality undervalued stocks.
- Build a cash flow focused watchlist by zeroing in on the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com