
Should AI Remediation Launch Require Action From Qualys (QLYS) Investors?
- Qualys announced TruRisk Eliminate 2.0 with TruConfidence in October 2026, adding an AI powered remediation engine that orchestrates autonomous cyber risk fixes across hybrid IT environments and offering a free upgrade for existing TruRisk Eliminate customers.
- The focus on Autonomous RemOps, backed by data from half a billion patch deployments and a rollback rate of less than 0.1%, highlights Qualys' effort to turn remediation into a repeatable operating model rather than a series of ad hoc security tasks.
- We will now look at how Qualys' investment narrative could be influenced by TruRisk Eliminate 2.0 and its AI driven remediation engine.
Qualys Investment Narrative Recap
To own Qualys, you need to believe its risk operations platform and AI remediation can keep turning a fairly mature, high margin security business into a steady compounder rather than a one product story. The TruRisk Eliminate 2.0 launch fits that view, since it pushes Qualys deeper into autonomous fixes across hybrid environments, not just better detection.
The key near term catalyst remains whether newer offerings like ETM, CSAM, Patch Management and now Autonomous RemOps translate into stronger new logo wins and higher net expansion. The biggest risk is that AI security evolves faster than Qualys executes, which could lift R&D spend without meaningfully improving bookings.
The TruRisk Eliminate 2.0 announcement looks most relevant alongside Qualys' Agentic AI platform and cloud native risk operations center. These already aim to orchestrate remediation across Qualys and non Qualys data. TruConfidence effectively plugs into that thesis by trying to turn remediation into a repeatable operating loop, instead of tickets handed off to overworked IT teams.
For catalysts, the interesting piece is how this autonomy layer might support higher average revenue per customer when paired with flex pricing and multi module adoption in areas like cloud security and enterprise risk. Execution risk remains real, since competitors are pushing similar AI remediation stories. Investors will likely watch whether billings growth moves meaningfully above the current 7% to 10% expectation range.
Qualys Forecasts Tied To TruRisk Eliminate 2.0
Qualys' narrative references projections of US$871.6 million revenue and US$225.7 million earnings by 2029, which analysts link to the broader AI driven risk operations push that includes TruRisk Eliminate 2.0. That profile corresponds to an assumed 7.4% yearly revenue growth rate and an earnings increase of about US$19.2 million from US$206.5 million today, based on the current consensus estimates.
Uncover why Qualys' fair value indicates a 5% potential downside to its current price, which leaves little room for error.
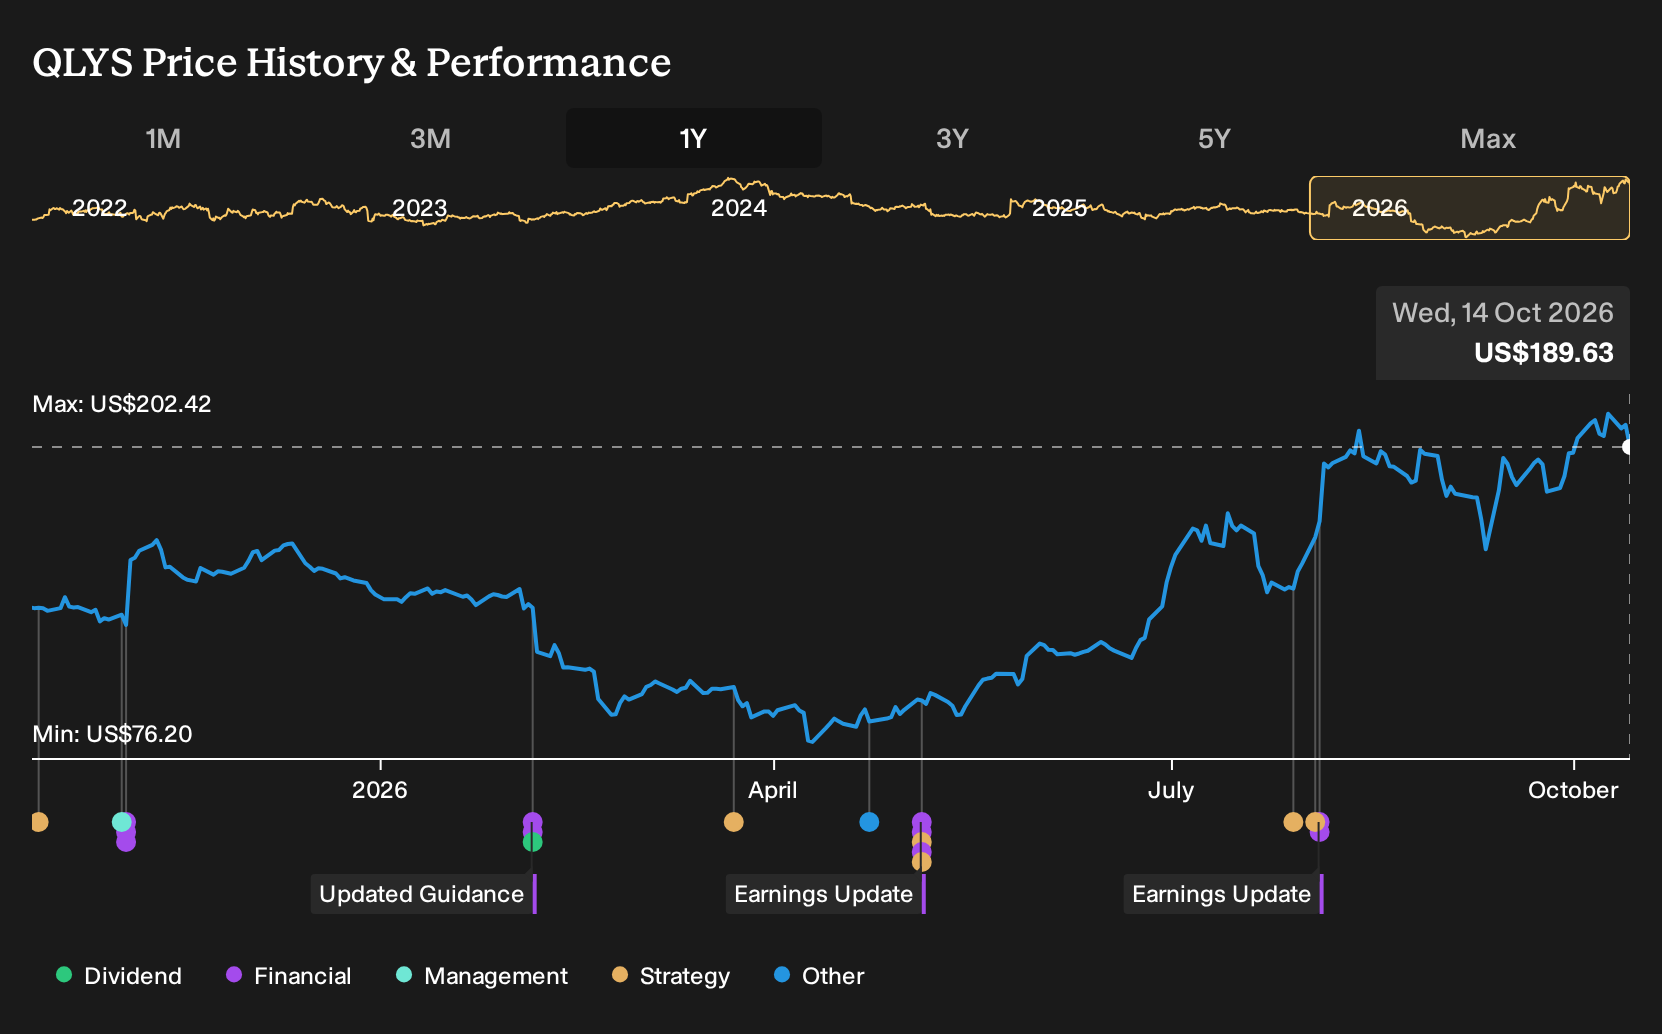
Exploring Other Perspectives
You are seeing only the middle ground. The most optimistic analysts frame TruRisk Eliminate style autonomy as the real catalyst for Qualys, with earlier forecasts already pointing to about US$934.6 million in revenue and US$258.5 million in earnings by 2029. Those projections came before this announcement, so opinions may shift and widen further.
Explore 2 other Qualys fair value estimates, including one that suggests potential upside of up to 23% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Qualys research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Qualys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qualys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Qualys?
Once you have a view on Qualys, it often helps to compare it against other candidates that fit different risk, income, and quality profiles. The Simply Wall St Screener can surface a mix of opportunities that matches how you like to invest.
- If you want to balance quality with a margin of safety, scan through our 32 high quality undervalued stocks that pair solid fundamentals with prices that may sit below intrinsic estimates.
- If capital preservation and smoother portfolio swings matter most to you, focus on 32 resilient stocks with low risk scores that score well on our risk checks and may offer steadier return profiles.
- If you prefer stronger balance sheets and cleaner fundamentals, filter for our list of solid balance sheet and fundamentals (25 results) to see which businesses clear a higher quality bar on debt and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com