
How Ministry Transfer Plans Will Impact EVN Stock Investors
- In early October 2026, the Deputy Prime Minister requested that EVN, alongside PVN, TKV and the National Power Transmission Corporation, be transferred to the Ministry of Industry and Trade once the Ministry of Finance finalizes EVN’s restructuring plan under Politburo directives.
- The same directive asks the Ministry of Industry and Trade to consolidate proposals to adjust Power Development Plan VIII. This could reshape how EVN balances energy security, grid investment and long term capital allocation across its regulated and supply activities.
- We will now assess how EVN's investment narrative could be reshaped by the planned transfer of oversight to the Ministry of Industry.
Compare how EVN's overhaul fits into the wider energy story by scanning a hand picked 43 power grid technology and infrastructure stocks.
EVN Investment Narrative Recap
To own EVN, you need to be comfortable with a heavy grid and renewables build out that leans on about €1b of capex a year and aims to keep an A category rating intact. The recent request to shift oversight to the Ministry of Industry and Trade looks more like a governance change than a fundamental reset of this plan and may not be a material short term earnings catalyst on its own.
The near term swing factor still sits in execution. Delivery on regulated network investment and new wind, solar and storage projects will be tested against rising customer owned generation and weather driven volatility in hydro and wind output. The main risk remains that high capex and potentially less favourable financing conditions squeeze free cash flow if new assets do not earn the returns investors expect.
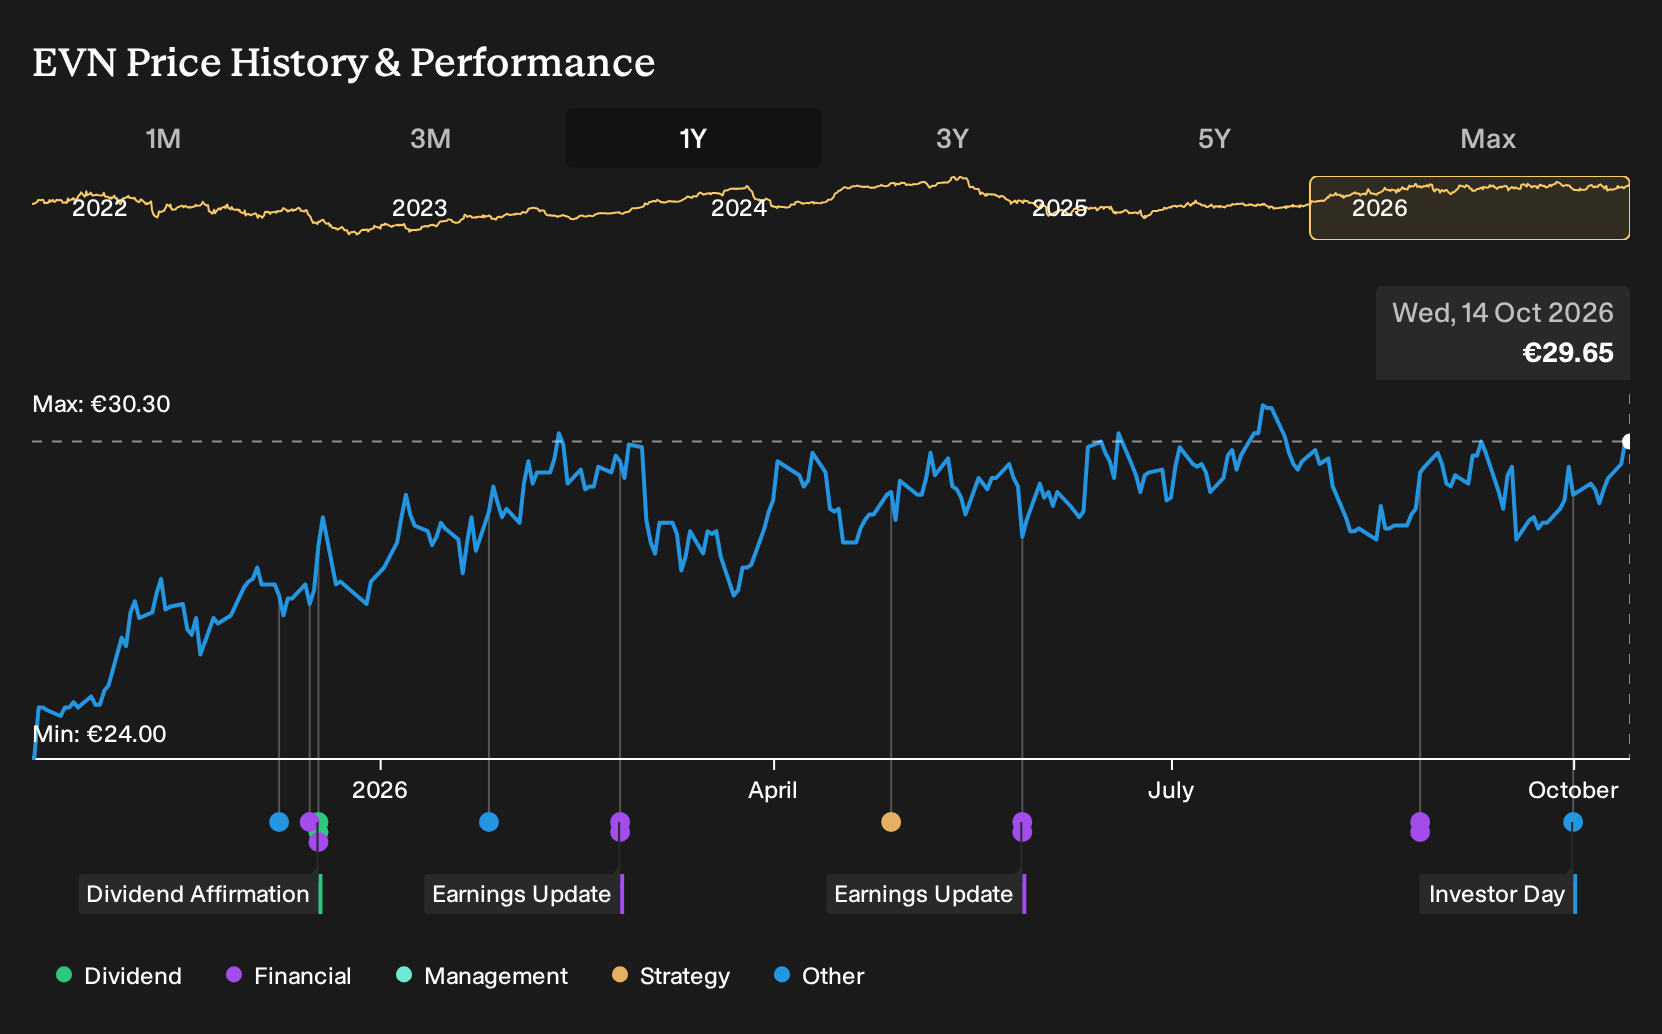
The EVN Analyst or Investor Day at the start of October 2026 matters here. That forum gives management a chance to spell out how the €1b per year investment pipeline, storage projects and grid upgrades line up with the evolving Power Development Plan and any policy changes from the new oversight structure.
For you as a shareholder or prospective investor, the key question is whether the messaging from that event supports confidence in execution. Clarity on capex phasing, tariff frameworks, funding mix and how EVN intends to deal with customer rooftop PV and hydro variability will shape how credible the current earnings profile and dividend look against expected conditions over the next three years.
EVN Analyst Expectations Under The New Oversight Structure
EVN's narrative projects €3.4b revenue and €437.5m earnings by 2029. This assumes 2.6% yearly revenue growth and an earnings decrease of about €66.8m from €504.3m today.
Uncover why EVN's fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bearish twist on the EVN story is the fear that social tariffs and weaker Generation EBITDA keep earnings under pressure. The lowest analysts were working with about €3.3b revenue and €403.4m earnings for 2029, far below consensus. Those forecasts came before this oversight shake up, so your own view may shift as the narrative is updated.
Explore 4 other EVN fair value estimates, including one that suggests as much as 38% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your EVN research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for EVN. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EVN's overall financial health at a glance.
Looking For More Ideas Beyond EVN?
If the EVN story leaves you wanting a broader watchlist, the Simply Wall St Screener lets you quickly filter for different types of opportunities that might suit your risk appetite and income needs.
- If you want potential mispricing with quality on your side, scan a curated set of 196 high quality undervalued stocks that combine strong fundamentals with more appealing valuations.
- For investors who care most about income resilience, focus on businesses that score well for payout strength and balance sheet support through a targeted 217 dividend fortresses.
- If capital preservation is your priority, narrow your search to steadier profiles by working through a carefully filtered 223 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com