
Is Williams Sonoma (WSM) Expensive Following Pottery Barns Ashley Stark Collection Launch?
Williams-Sonoma (WSM) is back in focus after its Pottery Barn brand launched an exclusive Ashley Stark collection, a line of more than 50 pieces now available only through potterybarn.com.
The Ashley Stark launch lands while Williams-Sonoma shares trade at US$242.48, with a 30-day share price return of 5.69% and a year-to-date share price gain of 29.08%. This is supported by a 1-year total shareholder return of 29.38% and a very large 3-year total shareholder return of about 22 times that, which suggests momentum has been building rather than fading.
Scan beyond Williams-Sonoma and this Ashley Stark launch by sizing up other premium home and lifestyle retailers on our hand picked 20 high quality undiscovered gems that may still be flying under most radars.
Williams-Sonoma now trades only slightly below both analyst targets and an intrinsic value estimate, despite a sharp run. Is that a fair safety margin, or a sign that caution on the stock is fading too quickly?
Most Popular Narrative: 29% Overvalued
Against a fair value estimate of $188.51 from the most followed narrative, Williams-Sonoma at $242.48 is priced for a lot to go right. This puts fresh focus on what could squeeze or support future margins.
While Williams-Sonoma continues to emphasize consistent dividend growth and sizeable share repurchases, the combination of declining gross margin, tariff volatility, and a shrinking store base over the past three years increases the risk that future cash returns draw on financial flexibility. That flexibility may be needed to protect revenue, margins, and earnings.
See why 0 investors see Williams-Sonoma as 29% overvalued.
Result: Fair Value of $188.51 (OVERVALUED)
Still, Williams-Sonoma could pressure this bearish script if emerging brands keep adding higher margin sales and AI tools sustain stronger engagement than cautious models allow.
Find out about the key risks to this Williams-Sonoma narrative.
Another View: Williams-Sonoma Through The SWS DCF Lens
The bearish narrative says Williams-Sonoma at $242.48 sits above a fair value of $188.51. In contrast, the SWS DCF model points the other way, with an estimated future cash flow value of $252.50, implying the current quote is about 4% below that mark. Which set of assumptions feels closer to your own?
Look into how the SWS DCF model arrives at its fair value.
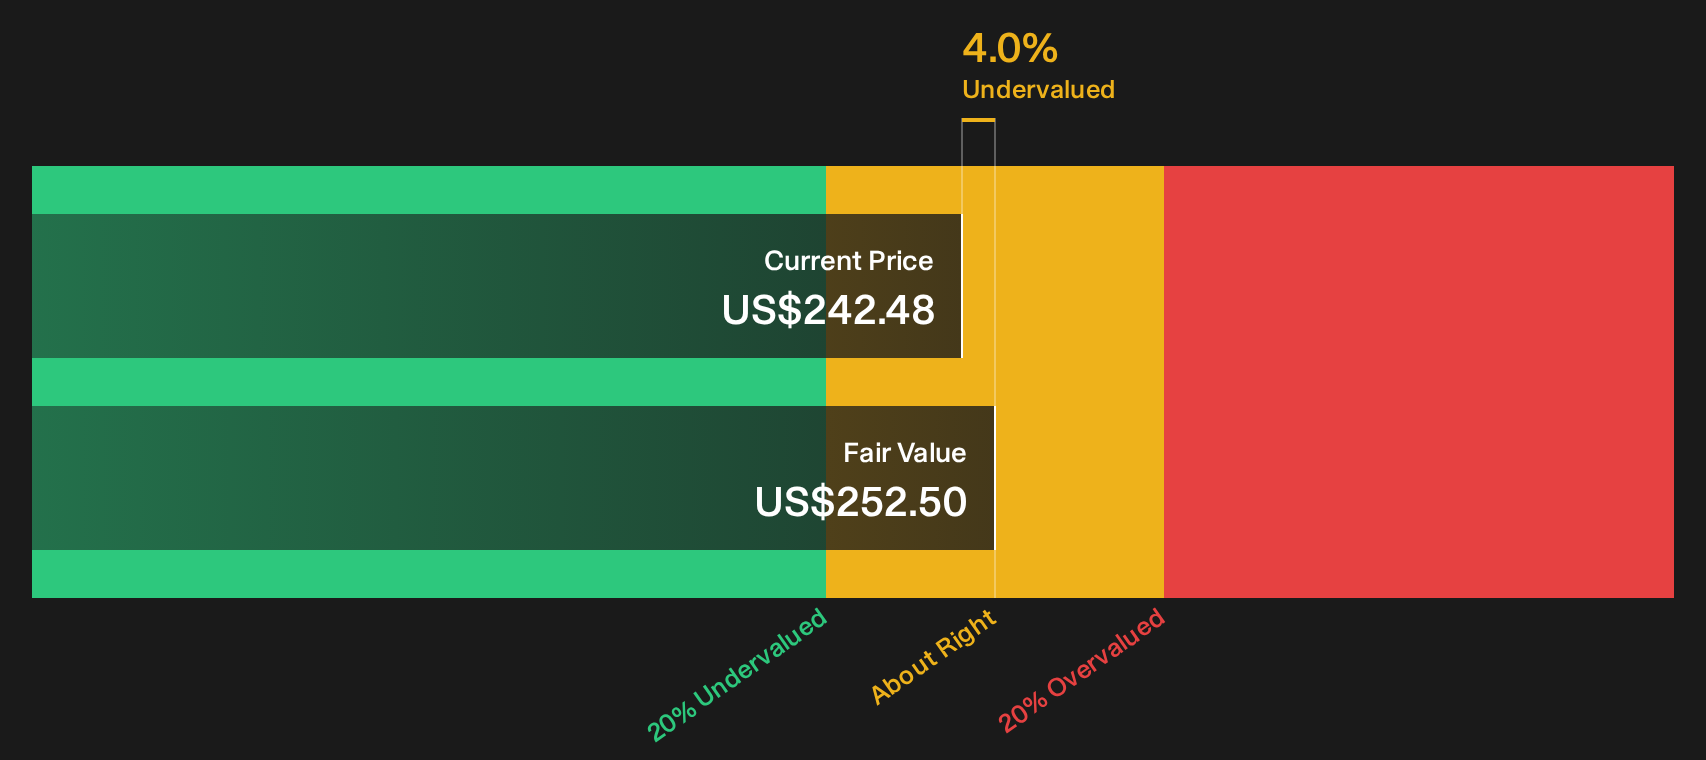
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Williams-Sonoma for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Views on Williams-Sonoma are clearly split, so treat that as your prompt to move fast, test the numbers yourself, weigh the optimism against the risks that matter most to you, and then round out your picture by checking the 3 key rewards.
Looking for more investment ideas beyond Williams-Sonoma?
If Williams-Sonoma has you thinking about what else might be hiding in plain sight, do not stop here. The right shortlist can reshape your watchlist.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center for your next idea.
- Pursue mispriced opportunities by running through a focused 32 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Prioritize stability and income by reviewing a hand picked 32 resilient stocks with low risk scores tailored for investors who want fewer surprises with their potential returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com