
Axcelis Technologies (ACLS) Dropped, So What Is Behind The Latest Attention?
Axcelis Technologies (ACLS) trades at $118.61 after mixed recent performance, with the share price rising over the past month but declining over the past 3 months and past year.
Short term momentum for Axcelis Technologies has cooled, with the share price falling 5.02% over the last day and 14.30% over the past week. This follows a 12.63% 1 month share price return and a 37.73% year to date share price gain that sits alongside a 41.59% 1 year total shareholder return. The 3 year total shareholder return is down 24.34%, which hints that recent moves reflect investors reassessing both growth potential and risk after a 5 year total shareholder return of 137.36%.
Scan for other semiconductor equipment stocks showing similar momentum shifts by running the 92 AI infrastructure stocks together with Axcelis Technologies in your watchlist.
Axcelis Technologies has surged this year but stumbled in recent weeks, which puts you at a fork in the road. Is this a reasonable entry now, or does it make more sense to wait for a cheaper price once the valuation picture is clear?
Most Popular Narrative: 26% Undervalued
Axcelis Technologies screens as undervalued against a $161 fair value narrative, with the last close at $118.61 suggesting the market is pricing in less than the earnings and margin path that analysts are building into their models.
Emerging requirements for higher voltage and advanced power management in data centers, including 800V architectures, together with 5G and renewable applications are now reflected in stronger DRAM and silicon carbide related bookings and in management’s raised 2026 and 2027 revenue outlook, which ties these usage cases more directly to Axcelis Technologies order growth and potential future revenue and EPS.
See why 78 investors see Axcelis Technologies as 26% undervalued.
This widely followed view rests on a discount rate of 11.33% and a fair value of $161, which is roughly 26% above the current price. The thesis leans on Axcelis Technologies converting demand for DRAM, power and compound semiconductors, and the planned Veeco merger, into orders that support both higher revenue and a profit margin path toward 16.2%.
Analysts fold in several moving parts to reach that figure. They assume revenue of about $1.2b and earnings of $202.7m by 2029, compared with $866.1m of revenue and $92.8m of net income today. They then apply a future P/E of 33.5x that is below their cited 52.4x industry level. That setup implies the current Axcelis Technologies share price already reflects some of this trajectory, but not all of the earnings and margin expansion embedded in the narrative.
For anyone weighing that gap, the key questions are whether the firm can sustain higher margin CS&I contributions, manage China concentration risk, and absorb the fixed cost of the planned Korea facility without eroding returns. The narrative’s fair value sits at the intersection of those assumptions, so a different view on execution, mix or capital intensity could justify a higher or lower figure for your own model.
Result: Fair Value of $161 (UNDERVALUED)
Still, Axcelis Technologies leans heavily on China for a large slice of revenue, and the planned US$35m Korea plant could weigh on margins if demand disappoints.
Find out about the key risks to this Axcelis Technologies narrative.
Another View: Axcelis Technologies Through The Cash Flow Lens
The analyst narrative presents Axcelis Technologies as 26% undervalued at $118.61 using earnings and multiples. A very different picture comes from the SWS DCF model, which puts future cash flow value at just $10.81 per share, implying the stock trades well above that estimate. Which side of that gap appears more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
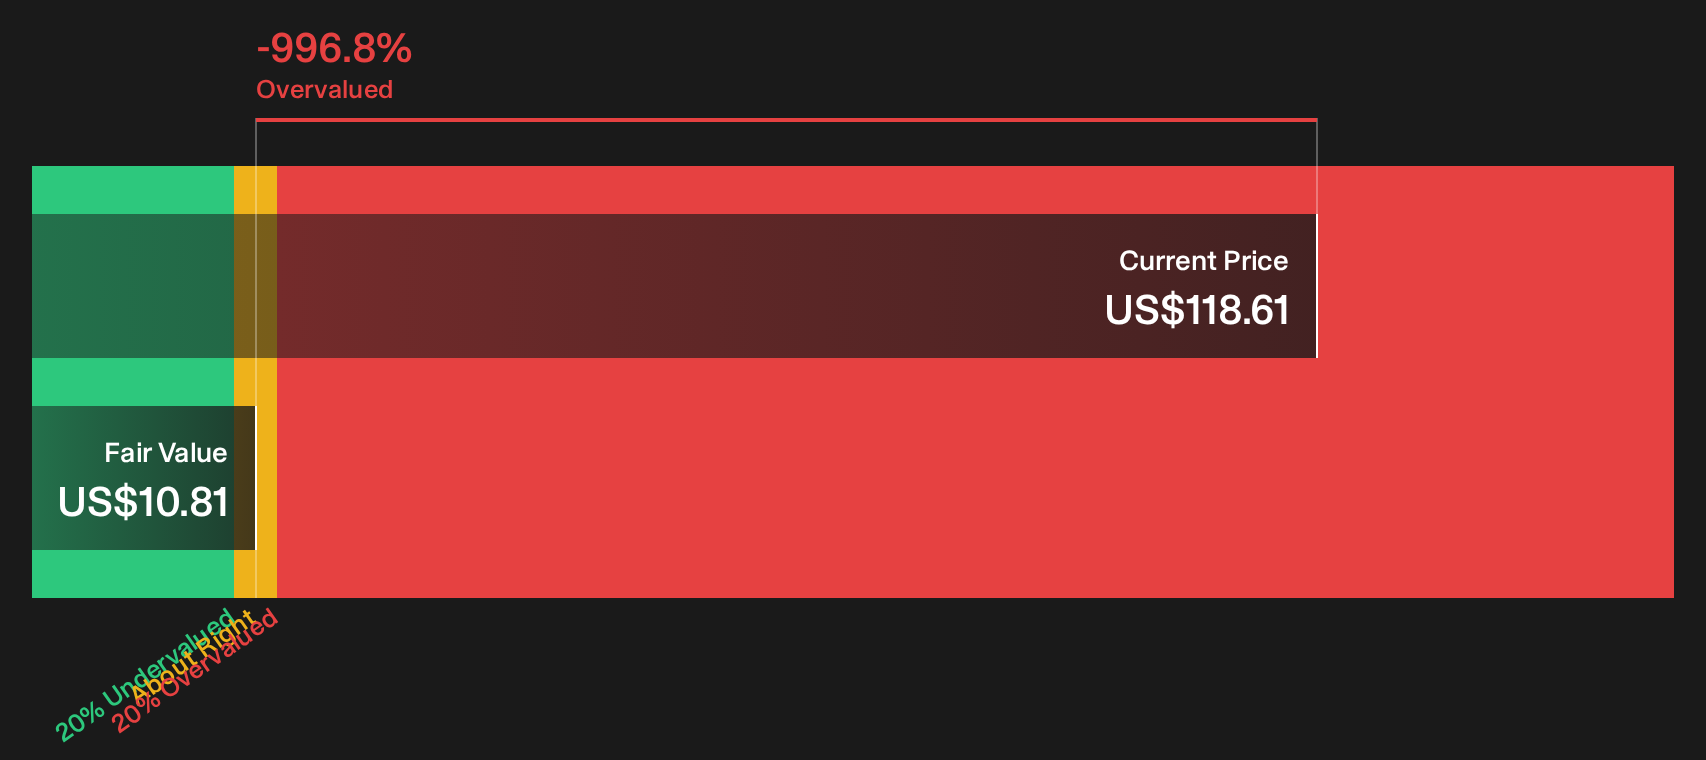
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Axcelis Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Axcelis Technologies often trigger hesitation, yet the data is right in front of you and the window to act on your own research never stays open forever. Weigh the upside and the cautions for yourself by starting with the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Axcelis Technologies?
If Axcelis Technologies has your attention, use that momentum and widen your watchlist now, before fresh opportunities slip past while you stay focused on a single ticker.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that can help anchor your portfolio when volatility picks up.
- Hunt for mispriced opportunities through a 32 high quality undervalued stocks that highlights businesses where fundamentals and current prices may not yet line up.
- Stack potential income streams by reviewing a 7 dividend fortresses designed for investors who want higher yields without ignoring balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com