
Navios Maritime Partners (NMM) Stock May Still Be A Bargain On Earnings
Navios Maritime Partners has been on a powerful run, and the pace of that climb raises a simple question for you as an investor. Is the current share price still grounded in what the partnership is earning today, or has sentiment run ahead of its income power?
- Over the past 3 years, Navios Maritime Partners has delivered a total return of 314.4%, which puts real pressure on the question of how much earnings can justify the current price.
- The business relies on its shipping fleet to turn freight demand into operating profit, so asset utilization, charter rates and capital spending needs can all feed directly into how much earnings support the valuation at any given time.
- There is a second opinion on Navios Maritime Partners worth weighing. See what analysts think Navios Maritime Partners's shares could be worth.
The issue now is whether Navios Maritime Partners' recent share price level is justified by its earnings power when set against the Fair Ratio benchmark.
If you are weighing whether Navios Maritime Partners still lines up with its earnings, it can help to compare it with a wider set of stocks that meet clear, predefined criteria through 32 high quality undervalued stocks.
Does Navios Maritime Partners Look Undervalued on Earnings?
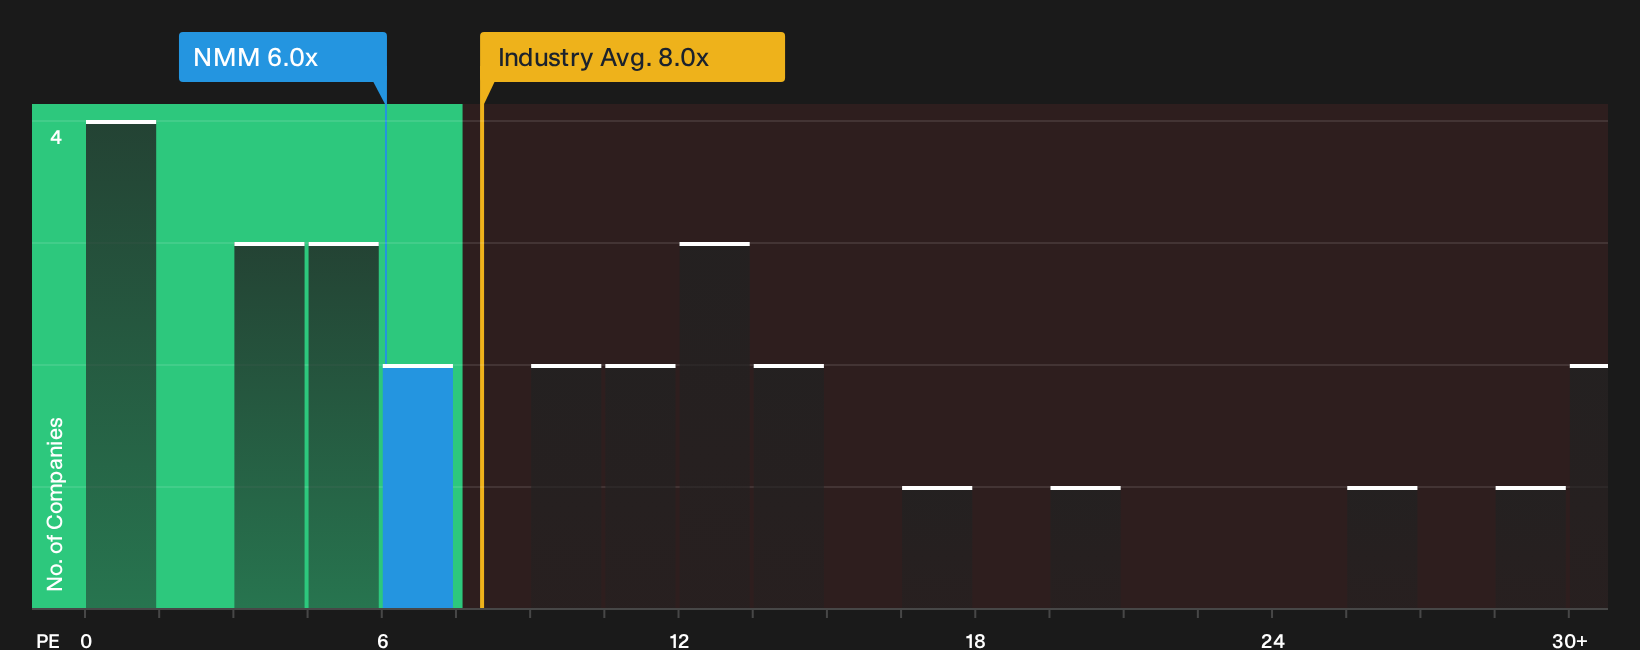
The P/E lens fits Navios Maritime Partners because earnings are a core driver of how investors tend to value shipping partnerships. On this yardstick, the partnership trades on a P/E of 6.0x, compared with a Shipping industry average of about 8.0x and a peer group closer to 11.8x. That places the stock at a marked discount to both the sector and similar companies that investors track against it.
The Fair Ratio, which reflects what you might expect for Navios Maritime Partners once its growth profile, margins, size and risk are factored in, points higher than where the shares trade today. The current 6.0x P/E sits below that tailored benchmark, which frames the units as undervalued on this earnings measure and invites questions about whether the market is being cautious about the sustainability or quality of those profits. Explore the numbers behind Navios Maritime Partners's P/E valuation.
The Navios Maritime Partners Narrative: What Would Justify Today's Price?
Narratives for Navios Maritime Partners pick up exactly where this valuation puzzle leaves you, by spelling out which paths for growth, margins and earnings would need to play out for the units to be worth materially more or materially less than today’s price. Each narrative frames that fair value view as a thesis about the business that can be revisited over time rather than a one-off snapshot, all housed on Simply Wall St’s Community page.
One of the top community narratives on Navios Maritime Partners: 9% undervalued
"Ongoing fleet renewal, with significant investment in newer, more energy-efficient vessels, positions Navios to capitalize on tightening environmental regulations..."
Discover why this Narrative puts Navios Maritime Partners at 9% undervalued.
One more Navios Maritime Partners check beyond the earnings multiple
Before closing the book on Navios Maritime Partners, it is worth looking at who actually pulls the levers inside the partnership and how their incentives line up with unitholders. See who runs Navios Maritime Partners and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com