
Rambus (RMBS) Puts AI Memory Narrative In Focus Following LPDDR6 PMIC Launch
Rambus (RMBS) put its power management work front and center, announcing a new PMIC for LPDDR6 SOCAMM2 server memory aimed at future AI infrastructure and currently sampling to lead customers.
Recent trading has been choppy for Rambus, with the share price falling 6.17% in the last session and down 17.38% over the past week, even after a 14.58% gain over 30 days. The one year total shareholder return is down 5.26%, but remains very strong over three and five years at 58.10% and about 3x respectively. This suggests that longer term momentum remains in place despite near term volatility around AI related product announcements such as the new LPDDR6 PMIC.
Scan beyond Rambus and compare this AI infrastructure story with other hand-picked chip and hardware plays in our 92 AI infrastructure stocks for context on where capital is concentrating right now.
Bulls see Rambus as an AI memory toll collector after the LPDDR6 PMIC launch, while bears point to a choppy chart and rich expectations. Which story most closely matches the current valuation setup?
Most Popular Narrative: 38% Undervalued
Rambus last closed at $92.11 while the most followed narrative anchors fair value around $147.86, which implies a wide gap that investors are actively trying to explain.
The company's sharpened focus on a core IP licensing and semiconductor business model is being reinforced by silicon IP growth expectations of 10% to 15% annually and record cash from operations of US$360 million in 2025. This supports a revenue mix that can help sustain net margins and fund further product and IP development.
See why 36 investors see Rambus as 38% undervalued.
Result: Fair Value of $147.86 (UNDERVALUED)
Still, Rambus faces real pressure from margin compression and the ongoing antitrust subpoena, either of which could undercut the bullish AI-driven thesis.
Find out about the key risks to this Rambus narrative.
Another View: Rambus Through The P/E Lens
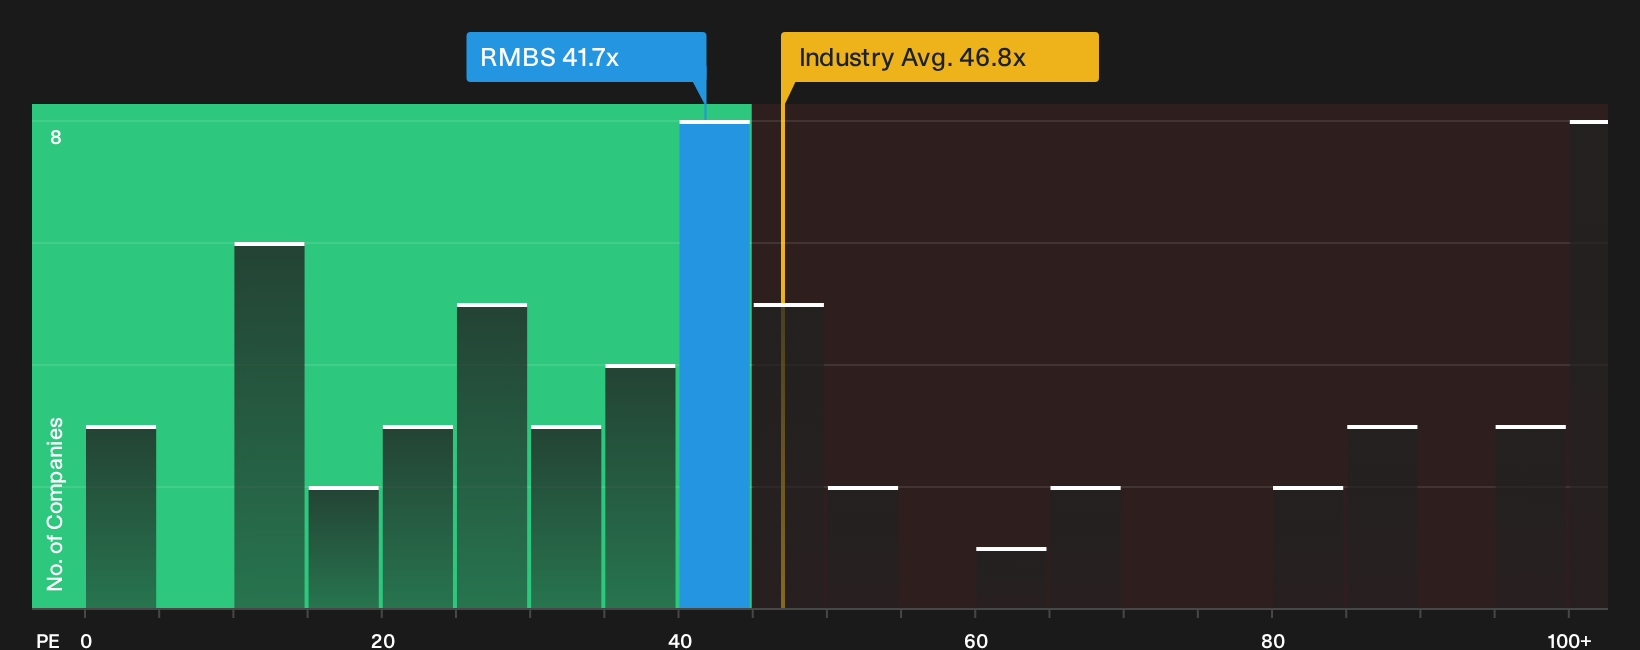
Rambus may look undervalued against a $147.86 fair value anchor, yet the current P/E of 41.7x is above an estimated fair ratio of 36.5x. The multiple also sits below the US Semiconductor average of 46.8x and slightly under peer levels of 43.5x. Is that a margin of safety or a valuation stretch in disguise?
See what the numbers say about this price in our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Rambus debate feels split, move quickly on your own homework and stress test the assumptions that matter most to you. To see what optimism in the data looks like in more detail, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Rambus?
You have seen how the Rambus story splits opinion. Do not stop there when a wider set of opportunities could reshape how you think about risk and reward.
- Target long term compounding potential by reviewing a curated set of attractively priced businesses using the 32 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by focusing on companies with robust finances through the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed potential and widen your opportunity set by scanning the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com