
Cullen/Frost Bankers (CFR) Faces Target Cut Pressure, Is It Still 13% Undervalued?
Cullen/Frost Bankers (CFR) came under pressure after Cantor Fitzgerald cut its target, pointing to weaker core fee income. Rising Treasury yields and hotter CPI data also added to the selling.
Despite the latest pullback, Cullen/Frost Bankers has built a stronger backdrop over time, with the 1-year total shareholder return of 22.96% and the 3-year total shareholder return of 81.84% contrasting with a 30-day share price return that is down 7.23%.
Spot opportunities other investors may be missing by scanning 32 resilient stocks with low risk scores, which combines resilient balance sheets with the kind of earnings profile Cullen/Frost Bankers is being judged on today.After that pullback and a price near $151 against analyst targets around $173, along with an intrinsic value estimate implying a larger gap, where does fair value for Cullen/Frost Bankers really sit now?
Most Popular Narrative: 13% Undervalued
Cullen/Frost Bankers last closed at $151.57, against a most-followed fair value estimate of $174.86 that applies a 7.24% discount rate to future earnings and cash flows. That gap sets the stage for a thesis that places more weight on branch expansion, mortgage growth, and capital returns than on short term margin concerns.
Continued Texas branch expansion, with approximately 79 to 80 new locations opened since 2018 and a plan to add another 5 branches over the balance of 2026, is expected to keep adding new loans, deposits and households that can support revenue growth and scale driven improvements in earnings.
The growing mortgage platform, which reached around US$850 million to US$1 billion of residential loans with average borrower credit scores in the mid 700s and a high share of customers new to the bank, is creating a pipeline of primary banking relationships that can contribute to deposit growth, cross sold products and earnings.
See why 4 investors see Cullen/Frost Bankers as 13% undervalued.
Result: Fair Value of $174.86 (UNDERVALUED)
Still, Cullen/Frost Bankers leans heavily on Texas and branch-led growth, so a local credit shock or structurally higher operating costs could quickly challenge this upside story.
Find out about the key risks to this Cullen/Frost Bankers narrative.
Another View On Cullen/Frost Bankers’ Price Tag
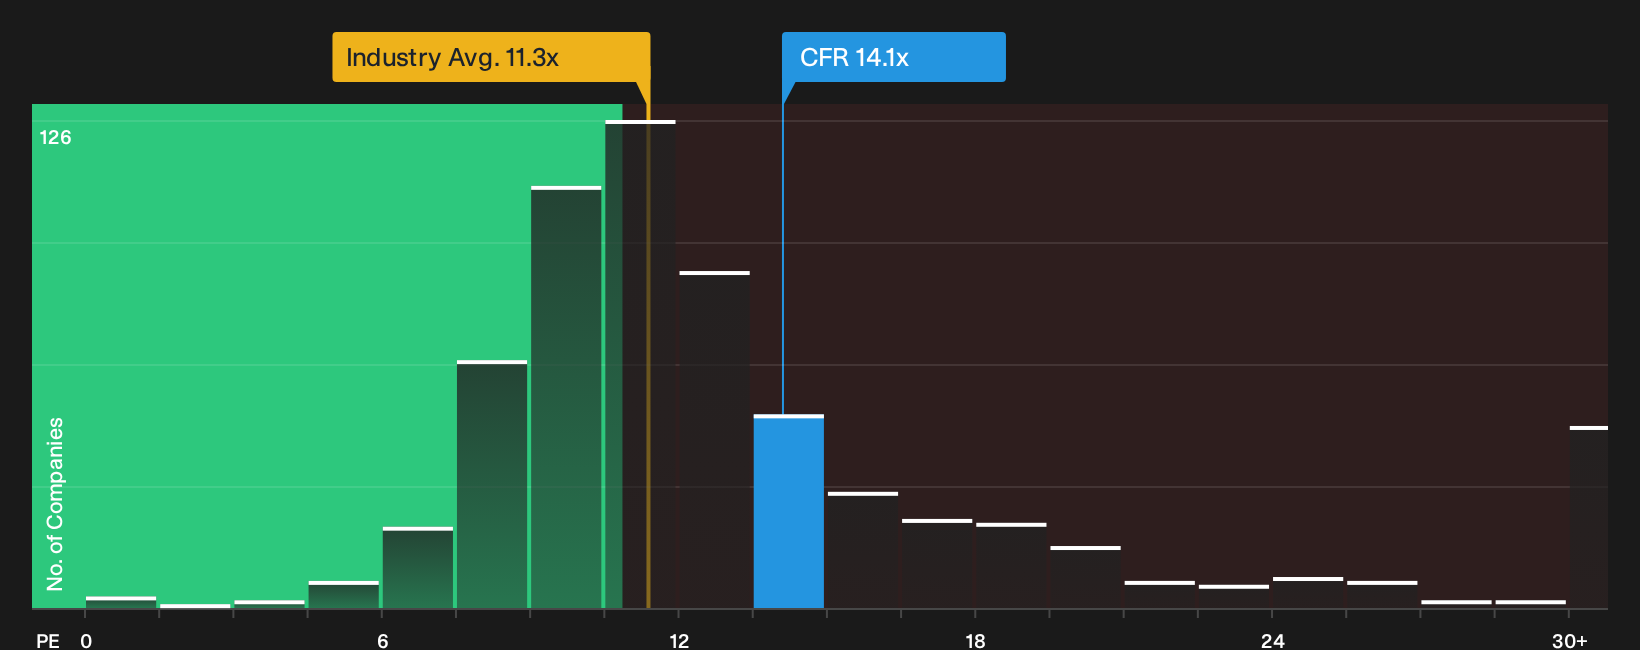
The fair value story built on future cash flows points to Cullen/Frost Bankers as 40.9% below that estimate, yet the simple P/E picture looks far less generous. At about 14.1x earnings versus a US Banks average of 11.4x and a fair ratio of 11.4x, the shares trade at a clear premium. Is the richer multiple a signal that the cash flow model is too optimistic, or that the market is underpricing the franchise strength in Texas?
To unpack how that premium, the industry gap, and the fair ratio fit together before you form a view on risk or opportunity, it is worth stepping through the valuation breakdown in more detail with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed tone on Cullen/Frost Bankers leaves you torn, move quickly from headlines to hard numbers and shape your own conclusion by reviewing 3 key rewards.
Looking for more investment ideas beyond Cullen/Frost Bankers?
Round out your watchlist with a few fresh angles so you are not relying on just one bank story when the next move hits.
- Target resilience by scanning a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with stronger financial footing than the average ticker.
- Hunt for mispriced opportunities through a 32 high quality undervalued stocks that may surface quality companies trading below their estimated worth.
- Build your income shortlist by checking a 7 dividend fortresses that screens for higher-yield payouts supported by sturdier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com