
Is NiSource (NI) Fully Valued As Its October 28 Earnings Date Nears?
NiSource earnings date puts the stock in focus
NiSource (NI) has set October 28, 2026 for its third quarter results release, with a same day conference call that many shareholders will watch closely for updates on its regulated utility operations.
The share price of NiSource at US$41.26 has slipped over the past quarter, with a 90 day share price return down 10.83%, even though the 3 year total shareholder return of 74.35% and 5 year total shareholder return of 94.86% point to a much stronger longer term journey for investors.
Scan beyond NiSource and compare this earnings setup with other regulated utilities by running the 43 power grid technology and infrastructure stocks in parallel with your research.
After a strong multi year run but a weaker recent stretch, NiSource now sits at a point where investors have to ask if most of the easy upside is spent or if the valuation still leaves meaningful room ahead.
Price-to-earnings of 21.8x for NiSource: Is it justified?
NiSource currently trades at a P/E of 21.8x, which sits below its peer group on this metric but above the wider integrated utilities industry average.
The P/E ratio compares the share price with earnings per share and gives a rough sense of how much investors are paying for each dollar of profit. For a regulated utility like NiSource, where earnings tend to move in relatively measured steps, this yardstick is often a quick shorthand for how the market is weighing stability, growth forecasts and risk.
On one side, NiSource screens as good value versus similar US peers, with its 21.8x P/E sitting well under a 30.6x peer average. On the other side, the same multiple looks more demanding when set against the global integrated utilities average of 18x, which suggests investors are already paying a premium compared to the broader sector. The estimated fair P/E of 20.7x also points a touch lower than where the stock is currently priced, which is a level the market could move towards if sentiment cools.
Explore the SWS fair ratio for NiSource.
Result: Preferred multiple of 21.8x price-to-earnings (OVERVALUED)
Still, NiSource faces risks if regulated returns tighten or if capital spending on its gas and power network has a greater impact on future earnings expectations.
Find out about the key risks to this NiSource narrative.
Another view on NiSource valuation
The P/E discussion points one way, yet the SWS DCF model points another. On that framework, NiSource at $41.26 trades above an estimated future cash flow value of $36.02, which frames the shares as expensive. Investors may consider which signal should carry more weight when earnings guidance lands on October 28.
Look into how the SWS DCF model arrives at its fair value.
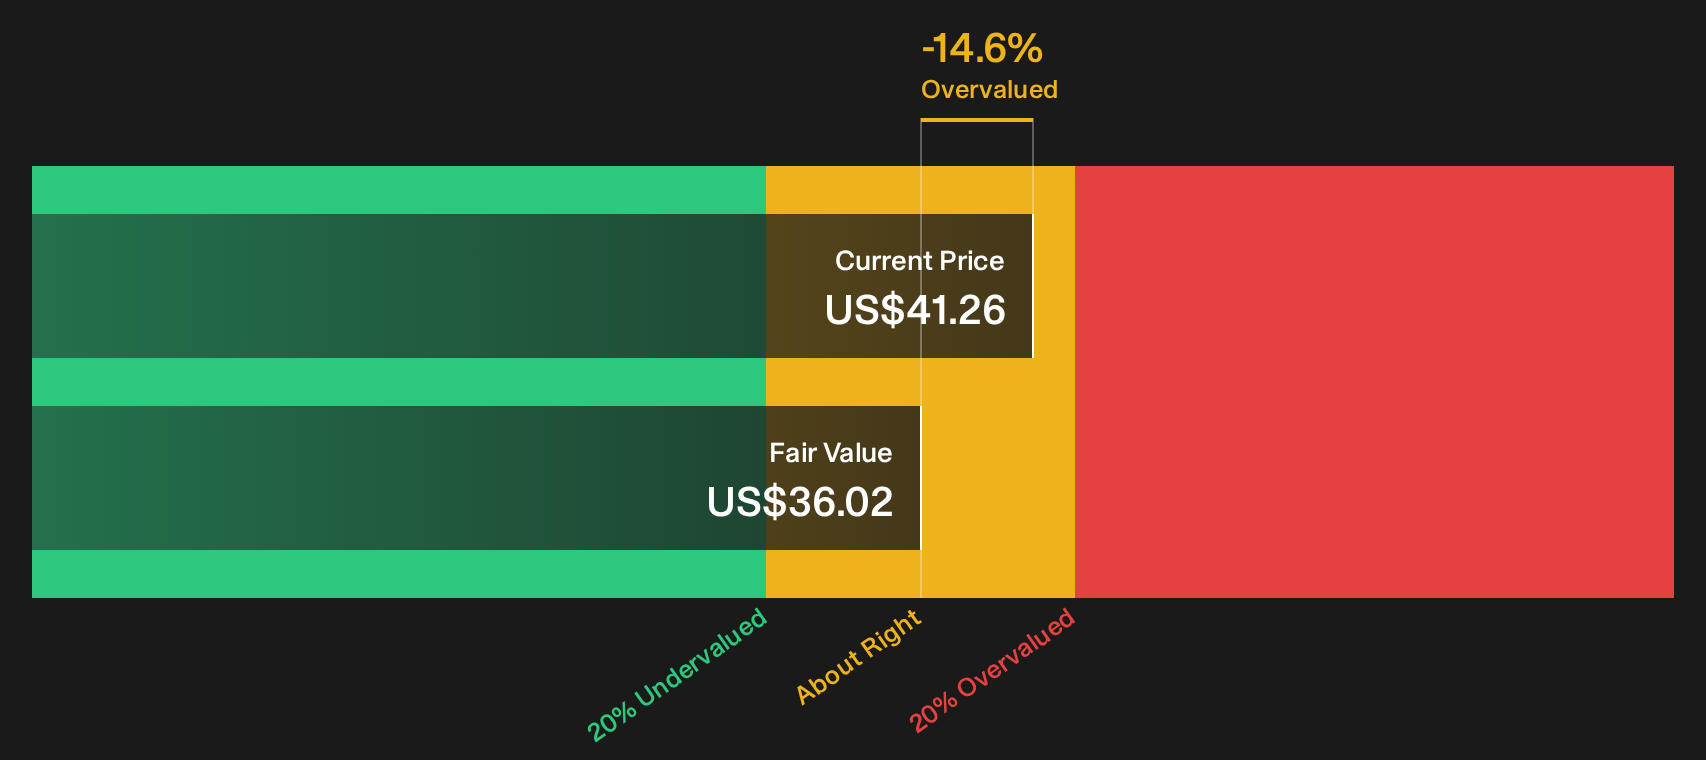
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NiSource for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The mix of richer valuation signals and a softer recent share price run leaves the NiSource story feeling finely balanced rather than settled. Act quickly and test that balance against your own expectations by weighing up the 2 key rewards and 3 important warning signs
Looking for more NiSource sized investment ideas?
If NiSource has your attention today, you can use that momentum to broaden your watchlist and uncover other potential opportunities before the market prices them differently.
- Spot potential deep value setups by scanning for companies that combine quality fundamentals with lower valuations through the 32 high quality undervalued stocks.
- Strengthen your income toolkit by focusing on businesses with higher yields and resilient payouts using the 7 dividend fortresses.
- Prioritise capital protection by filtering for companies with sturdier finances through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com