
Nektar Therapeutics (NKTR) Could Be 72% Undervalued On New Rezpegaldesleukin Data
Nektar Therapeutics (NKTR) is in focus after presenting long term Phase 2b data on its autoimmune drug candidate rezpegaldesleukin at the 2026 EADV Congress in Vienna, highlighting one year efficacy and maintenance results.
Despite the fresh rezpegaldesleukin data, Nektar Therapeutics shares have come under pressure, with the 30 day share price return down 46.15% and the 1 year total shareholder return declining 35.15%. However, the 3 year total shareholder return remains very large at over 3.5x, pointing to momentum that has cooled sharply in recent months as investors reassess both execution risk and future payoff timing around the pipeline.
Compare Nektar Therapeutics with other high potential biotechs by scanning our hand picked 34 healthcare AI stocks, which could see sentiment swing quickly as trial data and approvals move the needle.
After a near halving of Nektar Therapeutics’ share price in a month, the market is now pricing in a very different balance between pipeline promise and execution risk. The question for investors is whether the current valuation still tilts the risk reward toward new buyers.
Most Popular Narrative: 72% Undervalued
Nektar Therapeutics closed at $36.89, while the most followed narrative pegs fair value at $133.08. The recent sell off therefore sits against a view that the long term opportunity is materially larger than the current price suggests.
Advancing innovative therapies like REZPEG in large, underserved markets could drive substantial revenue growth and improve long-term financial performance. Strong cash reserves and accelerated regulatory paths enable operational stability, support pipeline expansion, and reduce near-term financial risks.
See why 13 investors see Nektar Therapeutics as 72% undervalued.
Result: Fair Value of $133.08 (UNDERVALUED)
Still, the whole Nektar Therapeutics story leans heavily on rezpegaldesleukin, so any clinical stumble or prolonged delay in Phase 3 timelines could quickly change this undervalued narrative.
Find out about the key risks to this Nektar Therapeutics narrative.
Another View: What Nektar Therapeutics’ Sales Multiple Is Telling You
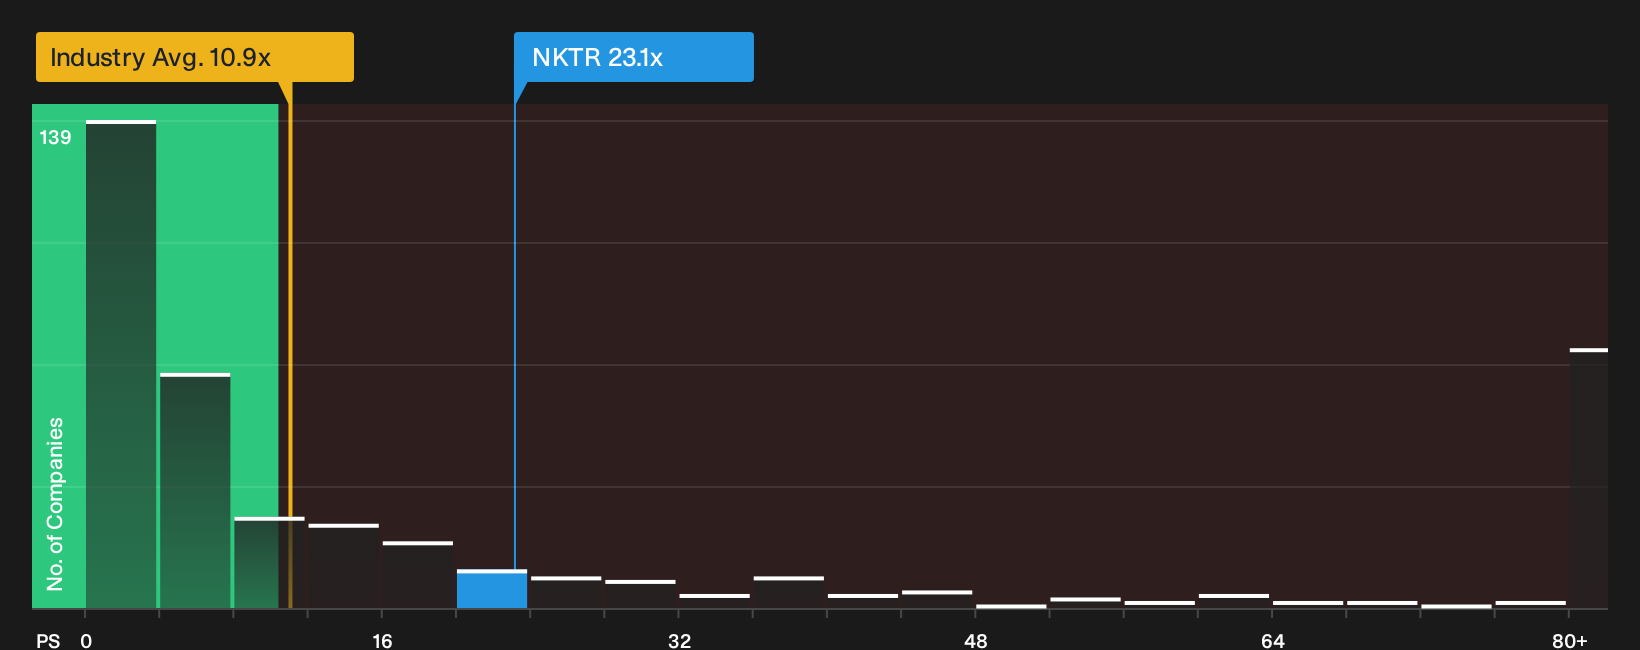
The analyst narrative frames Nektar Therapeutics as 72% undervalued on a fair value of $133.08, yet the current P/S of 23.1x sends a different signal. That ratio is higher than both the US Biotechs average of 11.3x and peer average of 19.8x, and also sits well above an estimated fair ratio of 10x. For you, that gap means the market already prices in a lot of future success, which could leave less room for error than the headline undervaluation suggests.
Before leaning on either story too heavily, it is worth stress testing whether the current sales multiple or the fair ratio feels closer to how you think risk in rezpegaldesleukin should be priced, and what happens to your thesis if the stock drifts back toward that 10x level.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Nektar Therapeutics so far. If you want to move before sentiment shifts again, weigh both sides of the story and start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Nektar Therapeutics?
Do not stop with Nektar Therapeutics. Broaden your watchlist using targeted stock ideas that filter for quality, value, and resilience so you are not caught flat footed.
- Target dependable income streams by reviewing companies in the 7 dividend fortresses that may help anchor your portfolio with higher yielding payouts.
- Hunt for potential mispricings by scanning the 32 high quality undervalued stocks where business quality and valuation filters work together to spotlight candidates for deeper research.
- Strengthen your defensive side by focusing on the 32 resilient stocks with low risk scores, which highlights businesses with more resilient profiles when conditions get choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com