
Why United Utilities Group (LSE:UU.) Is Back In The Spotlight
United Utilities Group (LSE:UU.) is back in focus after reporting reservoir storage across its network well below seasonal averages, with key Cumbrian sources such as Haweswater and Thirlmere at 42.5% compared with a typical 64.1%.
Recent news around reservoir stress sits against a share price that has climbed, with a 30-day share price return of 9.39% and a year-to-date share price gain of 19.73% at a current level of £14.44. The 5-year total shareholder return of 81.48% points to momentum that has been building over a longer horizon.
Compare United Utilities Group with a hand picked 4 resilient stocks with low risk scores that may appeal if resilient balance sheets matter as much to you as headline water stress.
The share price has sprinted ahead while headlines focus on reservoir strain and heavy investment commitments. Does United Utilities Group still offer an appealing trade off between risk and reward at £14.44, or has the easy upside gone?
Most Popular Narrative: 4% Undervalued
On the most followed view, United Utilities Group screens as modestly undervalued, with a fair value of £15.12 set against the latest close at £14.44 and a discount rate of 7.56% applied to those future cash flows and earnings assumptions.
The enlarged AMP8 capital plan of around £11.5b, including significant spend on asset health and projects such as the Lake Windermere programme, is expected to increase the regulated asset base and, in time, to support higher allowed revenue and earnings.
Ofwat’s new annualised totex re-opener process and the recent draft decision that allowed £975m of year one re-opener totex, with most of the asset health and Windermere submissions included, point to a mechanism for United Utilities Group to secure further growth capex during AMP8 that can feed into revenue and earnings in later years.
See why 15 investors see United Utilities Group as 4% undervalued.
Result: Fair Value of £15.12 (UNDERVALUED)
Still, the story around United Utilities Group could shift quickly if credit ratings move from negative outlook to a downgrade or if rising operating costs outpace allowed revenue.
Find out about the key risks to this United Utilities Group narrative.
Another View: United Utilities Group Looks Expensive on Cash Flows
There is a catch. While one fair value lens puts United Utilities Group at £15.12, the Simply Wall St DCF output points to a future cash flow value of just £5.17. That gap suggests investors are paying a heavy premium over what the SWS DCF model supports. Which story do you trust more?
Before leaning on either metric, it can help to see how the full cash flow model is constructed, step by step, in our valuation workup: Look into how the SWS DCF model arrives at its fair value.
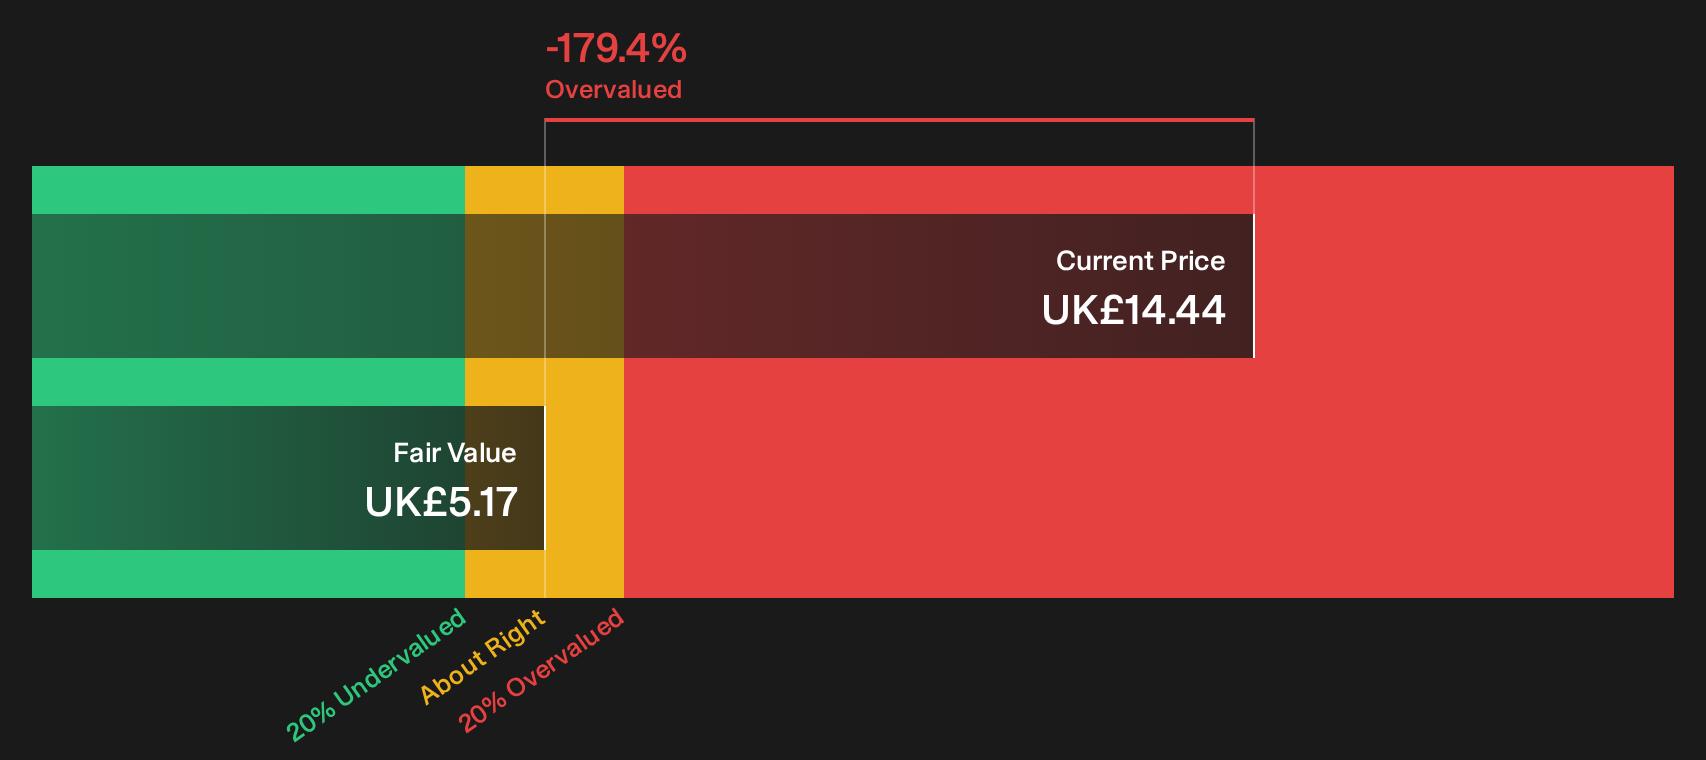
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United Utilities Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages run through this United Utilities Group story, with valuation signals, water stress and capex all pulling in different directions. If you want to move quickly and build your own conviction, start by weighing the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond United Utilities Group?
If you are serious about building a stronger portfolio, do not stop at one utility. A wider watchlist can reveal opportunities you would otherwise miss.
Use the Simply Wall St screener to jump on fresh ideas before they are crowded:
- Target potential mispricings by reviewing a 8 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Strengthen your income stream by scanning a 3 dividend fortresses focused on higher yielding payers with durable distributions in mind.
- Reduce portfolio shocks by checking a list of solid balance sheet and fundamentals (9 results) designed to highlight companies with sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com