
PR TIMES (TSE:3922) Stock Climbs As Earnings Momentum Fades
PR TIMES came into this earnings season with the stock already climbing, up around 16% over the past month and about 25% across three months, as investors leaned into its growth story. The headline this quarter is not revenue, which stayed in the ¥2.5b range, but the squeeze in profitability. Basic earnings per share stepped down to ¥38.41 in Q2 from ¥44.73 in Q1, with net income easing to ¥520.39m from ¥604.61m. This combination tests how much of the recent share price enthusiasm is about momentum rather than near term earnings power.
Love PR TIMES' recent share price strength but concerned that softer earnings per share could point to pressure on quality? Take a look at the list of solid balance sheet and fundamentals stocks (21 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥2,521.35m vs. ¥2,368.94m (up about 6.4%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥520.39m vs. ¥699.30m (down about 25.6%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥38.41 vs. ¥51.84 (down about 25.9%)
- Trailing 12-Month Net Profit Margin (latest vs. prior year): 22.7% vs. 20.0% (improved by about 2.7 percentage points)
Prefer clean visuals over another wall of earnings tables and raw figures? See PR TIMES' full picture, including how its valuation lines up with the recent earnings trend, in the company report for PR TIMES.
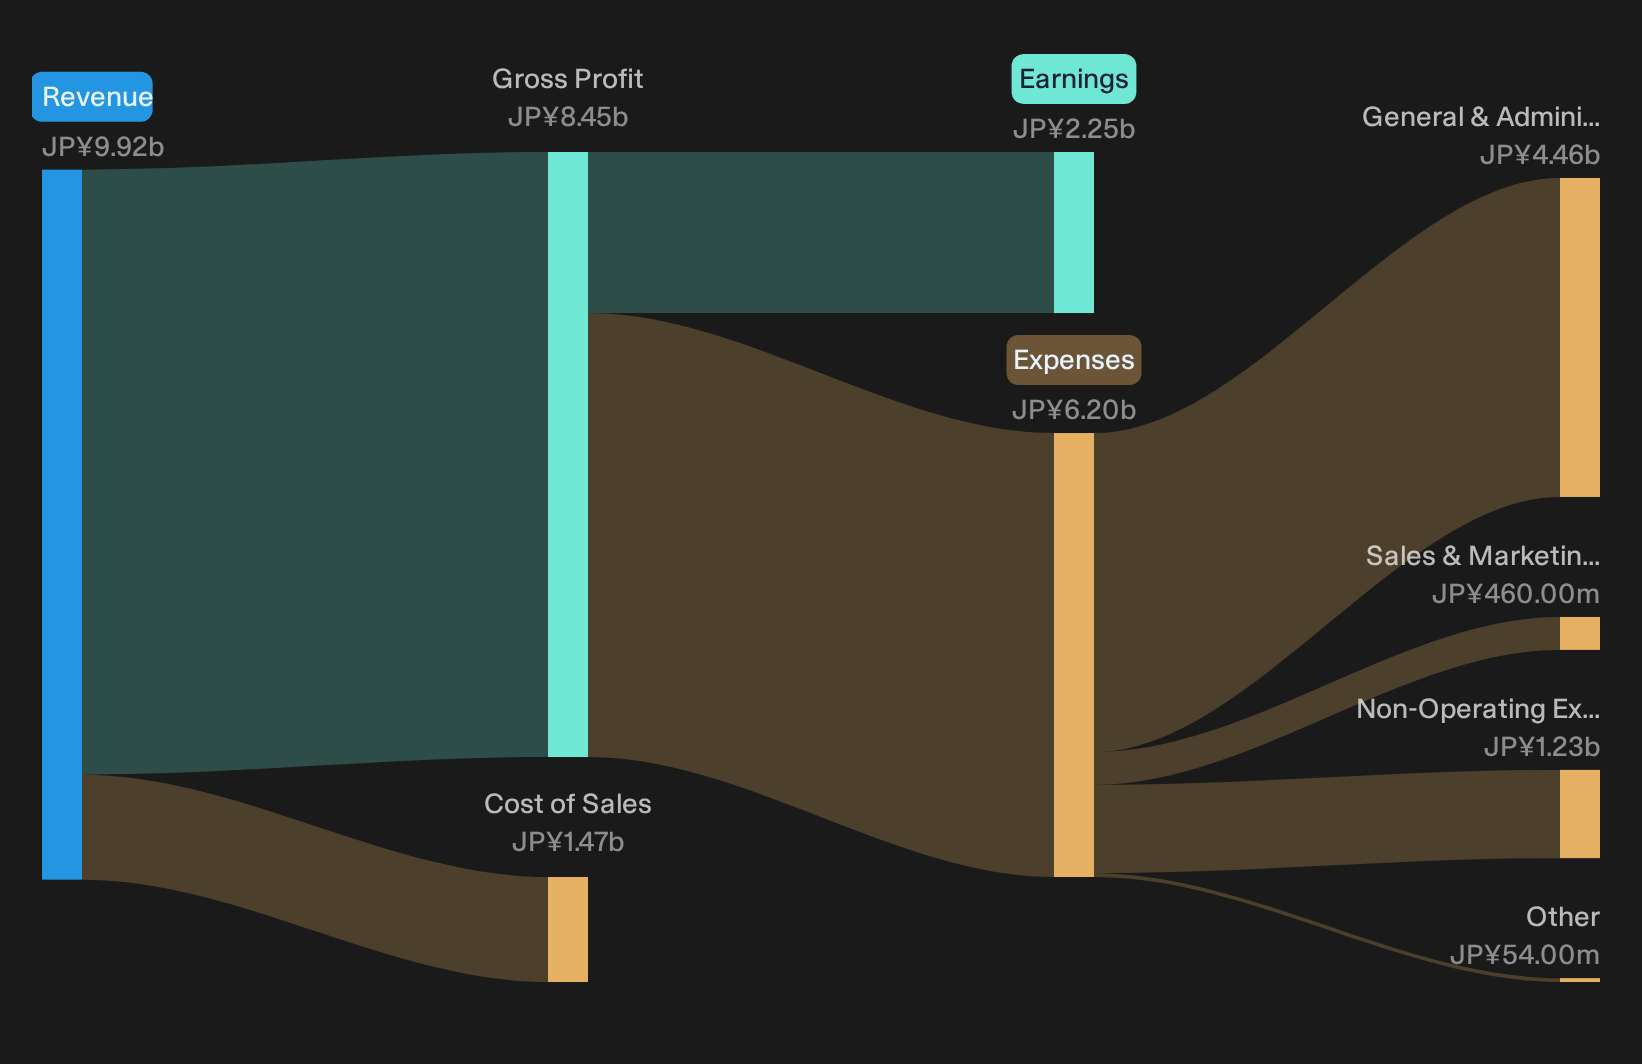
PR TIMES bullish story meets mixed earnings reality
For PR TIMES, the platform and SaaS narrative leans on steady digital adoption. Revenue in Q2 2027 of ¥2,521.35m versus ¥2,368.94m a year earlier supports that idea of a business still pulling in more activity through its ecosystem. The trailing 12‑month net profit margin at 22.7% compared with 20.0% also points to an operation that, over a longer window, is still turning sales into healthy profits.
Short term profitability tests the PR TIMES thesis
The softer side of this quarter gives the PR TIMES bull case a stress test. Net income excluding extra items moved from ¥699.30m in Q2 2026 to ¥520.39m in Q2 2027, with basic EPS easing from ¥51.84 to ¥38.41. That pullback suggests nearer term earnings power is under pressure even as margins look firmer on a trailing view, which keeps questions about the pace of profit generation firmly on the table.
With earnings now easing off the peak and the share price at ¥2,590, the real question is whether PR TIMES has the balance sheet strength to fund its next phase without strain. Check the full liquidity, cash flow and debt picture in the financial health analysis of PR TIMES stock.Guide Your Next Move With PR TIMES
Earnings for PR TIMES are now showing pressure on near term profitability, which makes timing matter more. Register for free with Simply Wall St and add it to a Watchlist so you can track price against fair value before deciding where your ideal entry point sits. Once you own shares, use the Portfolio Command Center to cut through noise and focus on updates that actually affect your thesis. Round it out by tapping into the Community to see how other investors are thinking about the same risks and catalysts, so you spot important shifts early and stay ahead of the wider market.
Seeking Alternatives Beyond PR TIMES?
Fresh ideas move first. Breakout stories, new momentum and under the radar for now stocks can get caught fast once the crowd piles in, so consider acting early.
- Focus on early strength in companies already showing disciplined growth and steady balance sheets by scanning the 22 resilient stocks with low risk scores before that stability is fully reflected in prices.
- Monitor cash-generating businesses quietly building momentum by working through the curated 72 high quality undiscovered gems while these opportunities are still flying below mainstream attention.
- Look for long-term compounding from consistent cash payers by reviewing the hand-picked 31 dividend fortresses while yields remain attractive and before payout stories attract broader interest.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com