
Schneider Electric (ENXTPA:SU) Teams With Apple On Smart Homes, Is The Stock Cheap?
Schneider Electric (ENXTPA:SU) just moved deeper into consumer tech, partnering with Apple on a Smart Thermostat and Power Mount designed for the Apple Home ecosystem and Apple’s Clean Energy Guidance tools.
That Apple tie-up lands at a time when Schneider Electric’s share price has gained 11.54% year to date, with a 7 day share price return of 3.87% hinting at firmer short term momentum, while a 5 year total shareholder return of 102.86% reflects a strong longer run outcome.
Scan for other grid and smart-home players positioned around the same theme as Schneider Electric with our hand picked 43 power grid technology and infrastructure stocks
Schneider Electric’s recent share price increase could reflect growing conviction in its energy and automation business, or it could simply indicate renewed enthusiasm for the Apple partnership. Which story does the current valuation actually tell?
Most Popular Narrative: 19% Undervalued
Schneider Electric’s most followed valuation view sees fair value at €325.04, above the last close of €264.40. This puts the Apple smart-home partnership against a backdrop of broader electrification and automation themes that the market is still debating.
The accelerating global shift towards electrification, renewable energy, and energy efficiency supported by both corporate and government sustainability initiatives continues to expand Schneider's addressable market and supports steady long-term revenue growth, particularly in energy management and grid modernization.
Ongoing R&D and product innovation in areas like AI driven digital twins, grid digitalization, energy efficient building solutions, and advanced industrial automation continue to differentiate the company and support cross selling opportunities, making future top line and margin growth more resilient as secular demand strengthens.
See why 120 investors see Schneider Electric as 19% undervalued.
Result: Fair Value of €325.04 (UNDERVALUED)
Still, the Schneider Electric story can be knocked off course if European construction stays weak for longer, or if heavy investment pressures cash flow and profitability.
Find out about the key risks to this Schneider Electric narrative.
Another View: Schneider Electric Through The P/E Lens
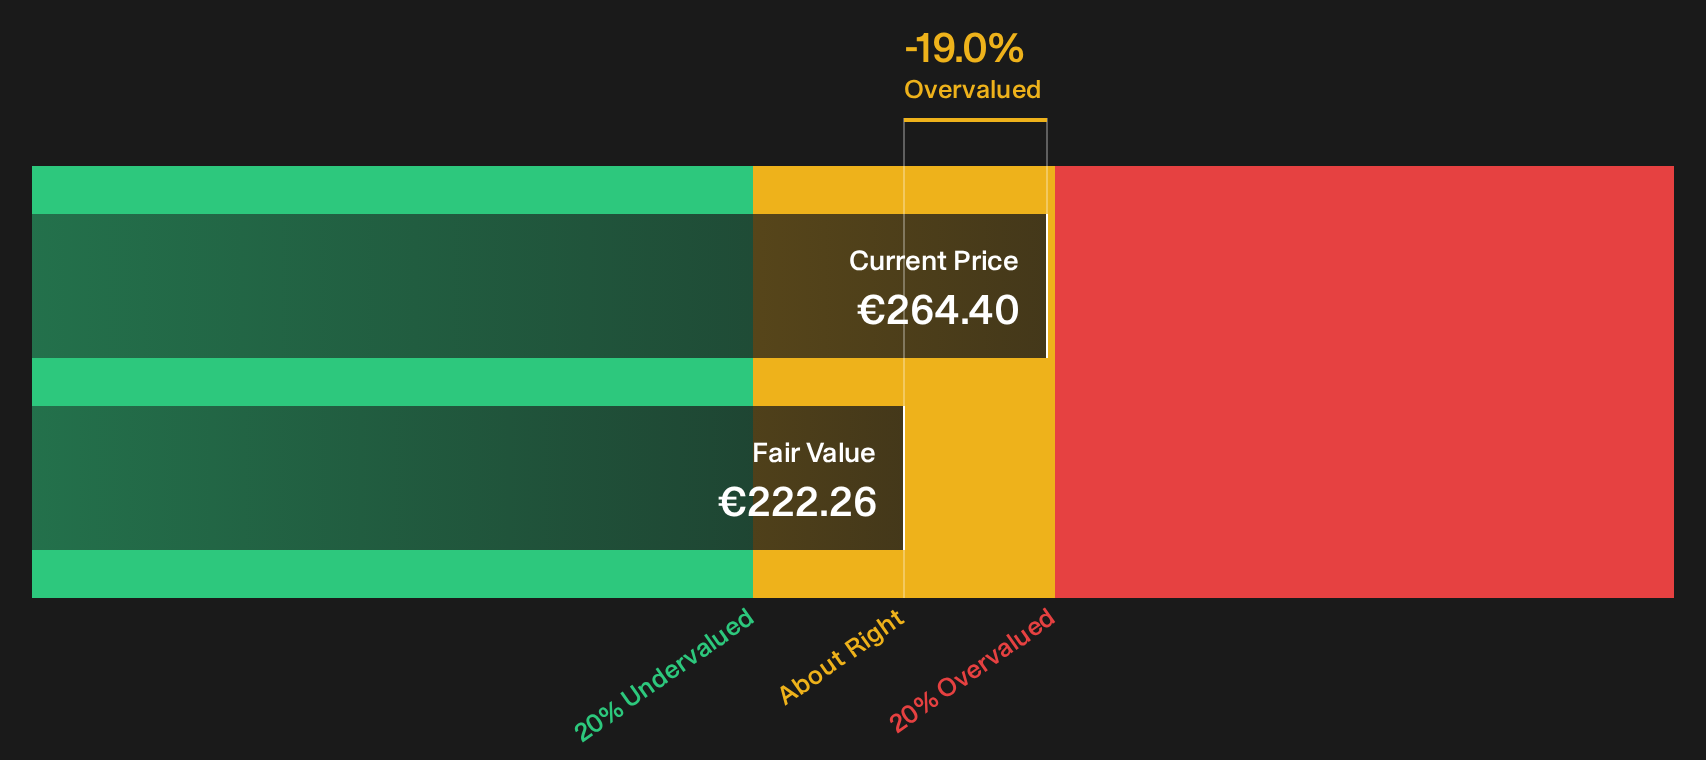
The SWS DCF model points to a future cash flow value of €222.26 per share, below the current €264.40 price, which suggests Schneider Electric screens as overvalued on that basis. Yet the current P/E of 31.4x sits only slightly above the peer average of 28.8x and below the fair ratio of 33.4x, so the market may already be pricing in some, but not extreme, valuation risk. Which signal do you give more weight to when the cash flow math and the earnings multiple are pulling in different directions?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Schneider Electric’s value and risk profile. If you want your own take, move fast and weigh both sides by checking the 3 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Schneider Electric?
If Schneider Electric has sharpened your appetite for opportunities, do not stop here. Put a wider watchlist to work with a few focused screeners.
- Target quality at a discount by scanning companies that pass tight fundamental checks through the 195 high quality undervalued stocks.
- Secure your income stream by zeroing in on consistently high yielders with the 216 dividend fortresses.
- Dial down potential volatility by filtering for financially resilient businesses using the 222 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com