
Sandisk (SNDK) Slides On China DRAM Progress, Is The Pullback Making It Cheap?
Sandisk (SNDK) has been under pressure after China based ChangXin Memory Technologies reported progress on DRAM designs, raising fresh questions about competition, pricing power, and how investors value AI exposed memory suppliers.
Recent headlines on AI spending and Chinese competition have knocked Sandisk’s share price down 5.33% on the day and 17.08% over the past week. However, the year-to-date share price return of 409.86% and a 1-year total shareholder return that is very large signal momentum built over a longer run that is now being tested rather than erased.
Scan how other AI focused memory and storage players are reacting to similar headlines by reviewing the 92 AI infrastructure stocks alongside Sandisk’s latest move.
Sandisk now trades at a steep discount to analyst targets after a sharp pullback, yet some models flag the shares as rich. Is this caution mispriced fear or a reasonable check on earlier enthusiasm?
Most Popular Narrative: 35% Undervalued
Sandisk closed at $1,403.34 while the most widely followed narrative assigns a fair value of $2,173. This gap reflects a view that the market price does not fully reflect projected AI related earnings power under that framework, even after the latest pullback.
Rapid AI and cloud workload expansion is driving data center NAND exabyte growth at a pace well above overall supply. This positions Sandisk's enterprise SSD portfolio and deepening hyperscaler engagements to support sustained revenue acceleration and structurally higher pricing power, benefiting earnings.
See why 153 investors see Sandisk as 35% undervalued.
Result: Fair Value of $2,173 (UNDERVALUED)
Still, the story can crack if NAND supply swings back into oversupply, or if AI and data center demand falls short of the current expectations.
Find out about the key risks to this Sandisk narrative.
Another View On Sandisk’s Value
While the most followed Sandisk narrative leans on analyst targets and long term AI earnings potential, the SWS DCF model points in a different direction. At $1,403.34 the shares sit above an estimated future cash flow value of $1,213.88, which frames Sandisk as overvalued on that measure and raises the question of which set of assumptions feels more realistic.
Look into how the SWS DCF model arrives at its fair value.
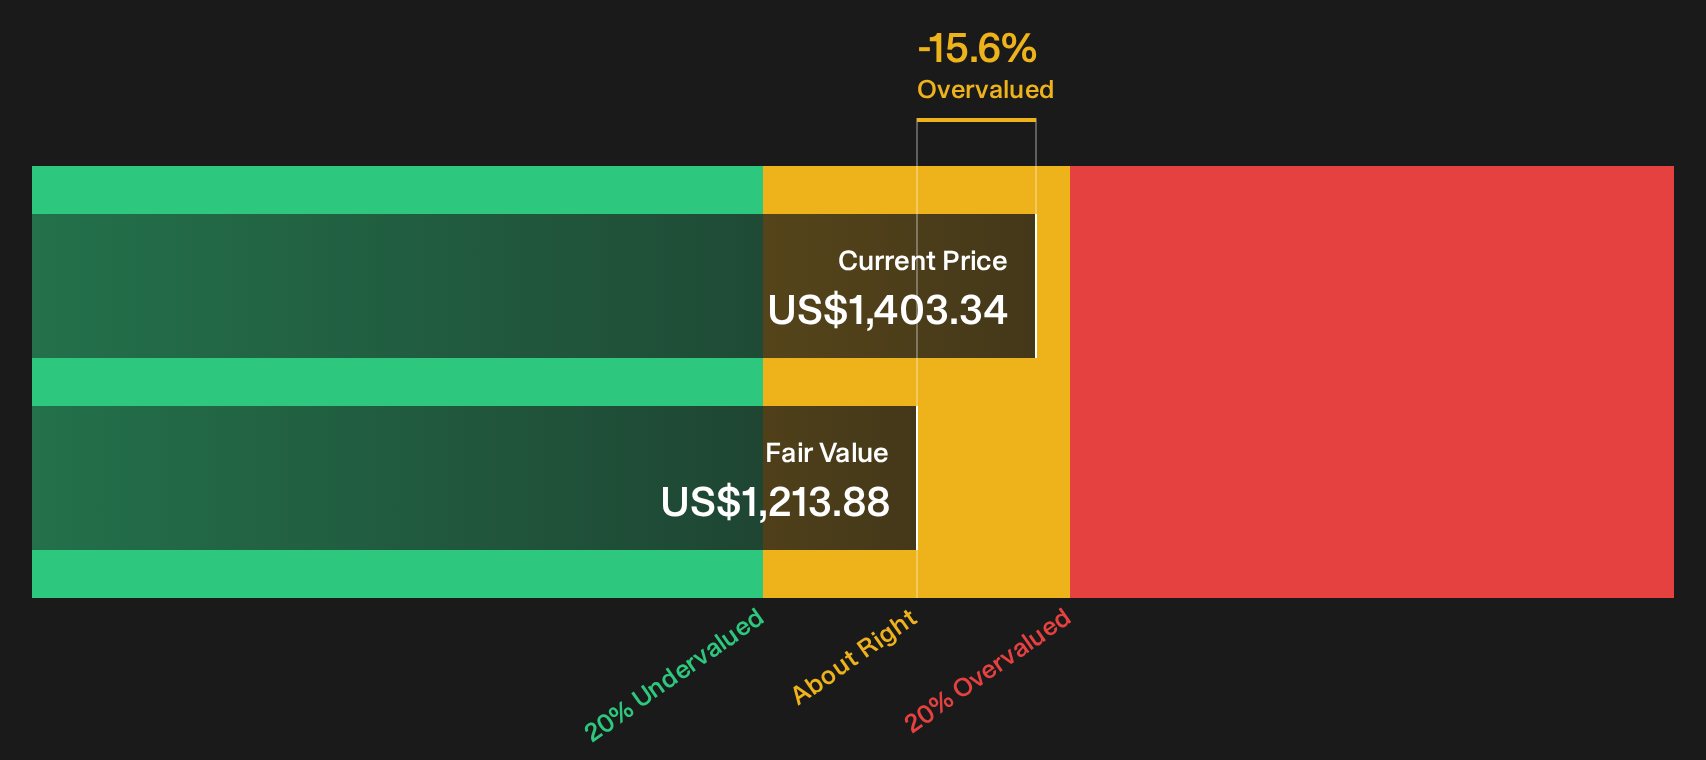
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sandisk for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Sandisk now looks split, with sharp recent share price swings compared with a strong run over the past year. Act while the data is fresh and weigh both sides by checking the 4 key rewards and 1 important warning sign.
Looking for more Sandisk investment ideas?
Do not stop your work with Sandisk alone. Broaden your watchlist with a few focused screeners so you are not relying on a single AI memory story.
- Target resilience first and filter for companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality and review the 20 high quality undiscovered gems that combine solid financials with lower investor attention.
- Prioritize sleep-at-night holdings and scan the 32 resilient stocks with low risk scores so you do not overlook steadier compounders while AI headlines dominate.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com