
Should Cigarette Volume Slump Require Action From BAT (LSE:BATS) Investors?
- British American Tobacco confirmed further progress on its 2026 share buyback, cancelling repurchased shares and reducing the ordinary share count outstanding.
- Fresh data from Spain and France shows cigarette volumes under pressure, with British American Tobacco seeing a 14.5% volume drop in Spain alone.
- We will now look at how British American Tobacco's investment narrative holds up in the context of this sharp European cigarette volume pressure.
Scan beyond British American Tobacco and pressure in European cigarette volumes to see which other income-focused businesses still clear a high quality bar with our 3 dividend fortresses
British American Tobacco Investment Narrative Recap
To own British American Tobacco, you need to be comfortable with a business that still leans heavily on combustibles while trying to build scale in vapour, heated and oral nicotine. The sharp volume pressure in Spain and softer shipments in France keep the near term focus on how effectively pricing, mix and reduced risk products can offset falling cigarette sticks.
The biggest short term swing factor is execution in new categories alongside disciplined costs, because that is where the incremental profit pool needs to come from. The key risk is that European volume weakness spreads or tightens further through regulation and illicit trade, which would test both margins and the pace of that transition.
The recent update on British American Tobacco’s 2026 share buyback sits in the background of all this. Cancelling shares and shrinking the ordinary share count can support per share metrics, but it does not change the operational reality of softer European cigarette demand or the work required in reduced risk products.
For you as an investor, that capital return is most useful when paired with consistent cash generation and disciplined debt management, given the group’s high leverage and mixed record on dividend stability. The real catalyst still sits with how reliably earnings from Vuse, glo and Velo can absorb ongoing declines in traditional cigarettes while funding these buybacks.
British American Tobacco's current consensus narrative points to revenues of £28.6b and earnings of £8.7b by 2029, up from current earnings of £6.3b. This implies revenue growth of 3.6% a year and an earnings increase of about £2.4b from today, with analysts using the 2029 forecast year as the reference point for these projections.
Uncover why British American Tobacco's fair value indicates a 21% potential upside to its current price that could narrow quickly.
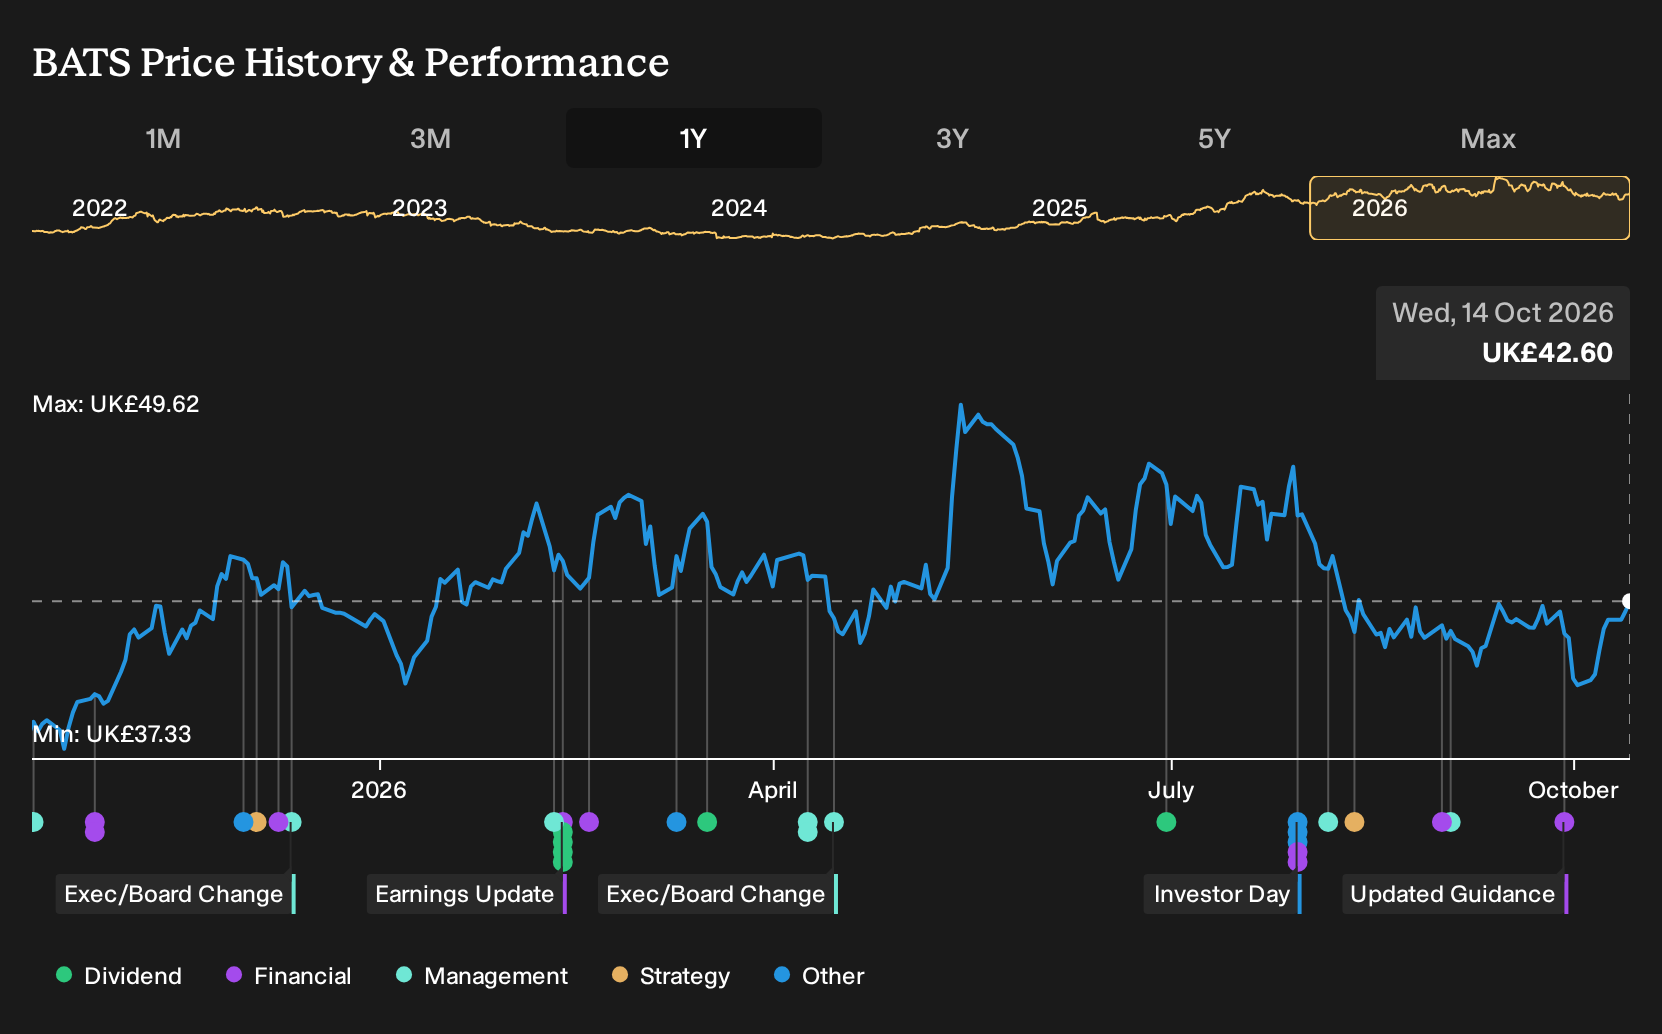
Exploring Other Perspectives
One bullish twist on British American Tobacco focuses on the buybacks themselves. The most optimistic analysts were working off revenue of about £30.0b and earnings near £9.3b by 2029 before this Spain and France volume shock, assuming strong smokeless progress and richer P/E multiples. You can treat this as one end of a wide opinion range that may shift as fresh data lands.
Explore 6 other British American Tobacco fair value estimates, including one that suggests as much as 101% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your British American Tobacco research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for British American Tobacco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate British American Tobacco's overall financial health at a glance.
Looking for more British American Tobacco investment ideas?
If British American Tobacco is already on your radar, it can help to set it alongside other companies with different risk, income and balance sheet profiles, then see what really fits your objectives.
- For investors who want potential mispricings on their radar, filter the market using our 8 high quality undervalued stocks and see which companies still look out of favour based on fundamentals.
- If income resilience matters most to you, focus on businesses that aim to pair higher yields with sturdier cash flows through the 3 dividend fortresses and stress test your watchlist against them.
- When capital preservation is the priority, narrow your universe to companies with stronger financial footing through the 4 resilient stocks with low risk scores and compare those profiles with British American Tobacco.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com