
AeroVironment (AVAV) Signs New Global Drone Deals Following Questions Over Whether Shares Are Fully Valued
AeroVironment (AVAV) has signed a series of new memorandums of understanding with partners in Taiwan, Spain and Australia, along with a connectivity deal for its Mayhem 10 system, giving investors fresh detail on its international unmanned systems footprint.
The recent string of MOUs comes at a difficult time for AeroVironment’s shareholders, with the stock down 21.38% over the past 30 days and 52.93% year to date. However, the 5-year total shareholder return of 30.35% still indicates a much stronger longer-run outcome than the last 12 months.
Spot opportunities around AeroVironment by scanning a hand picked group of 91 robotics and automation stocks that are also pushing into unmanned systems and defense-grade automation.AeroVironment’s shares have given up a lot of ground even as new partnerships broaden its unmanned systems reach. Is most of the rerating already in the rearview mirror, or is the current valuation still leaving meaningful upside on the table?
Most Popular Narrative: 16% Overvalued
AeroVironment last closed at $120.60, while the most followed narrative on the stock, according to LunaRodas, pegs fair value at $103.94. This frames the recent share pullback against a story that still sees the current price as ahead of itself.
The latest call reports a $500 million sole-source IDIQ for JIATF-401 Domestic Shield, with an initial $80 million contract in support of Golden Dome. The prior quarter positioned Titan as an established growth franchise already at scale, while the current award extends that into a new use case category (domestic, interagency) that had been signaled as an expansion path.
See why 9 investors see AeroVironment as 16% overvalued.
Result: Fair Value of $103.94 (OVERVALUED)
Still, the AeroVironment story carries pressure points, including unresolved internal control remediation and the lack of updates on previously highlighted platforms such as AV_Halo and BADGER/WASP.
Find out about the key risks to this AeroVironment narrative.
Another View on AeroVironment’s Valuation
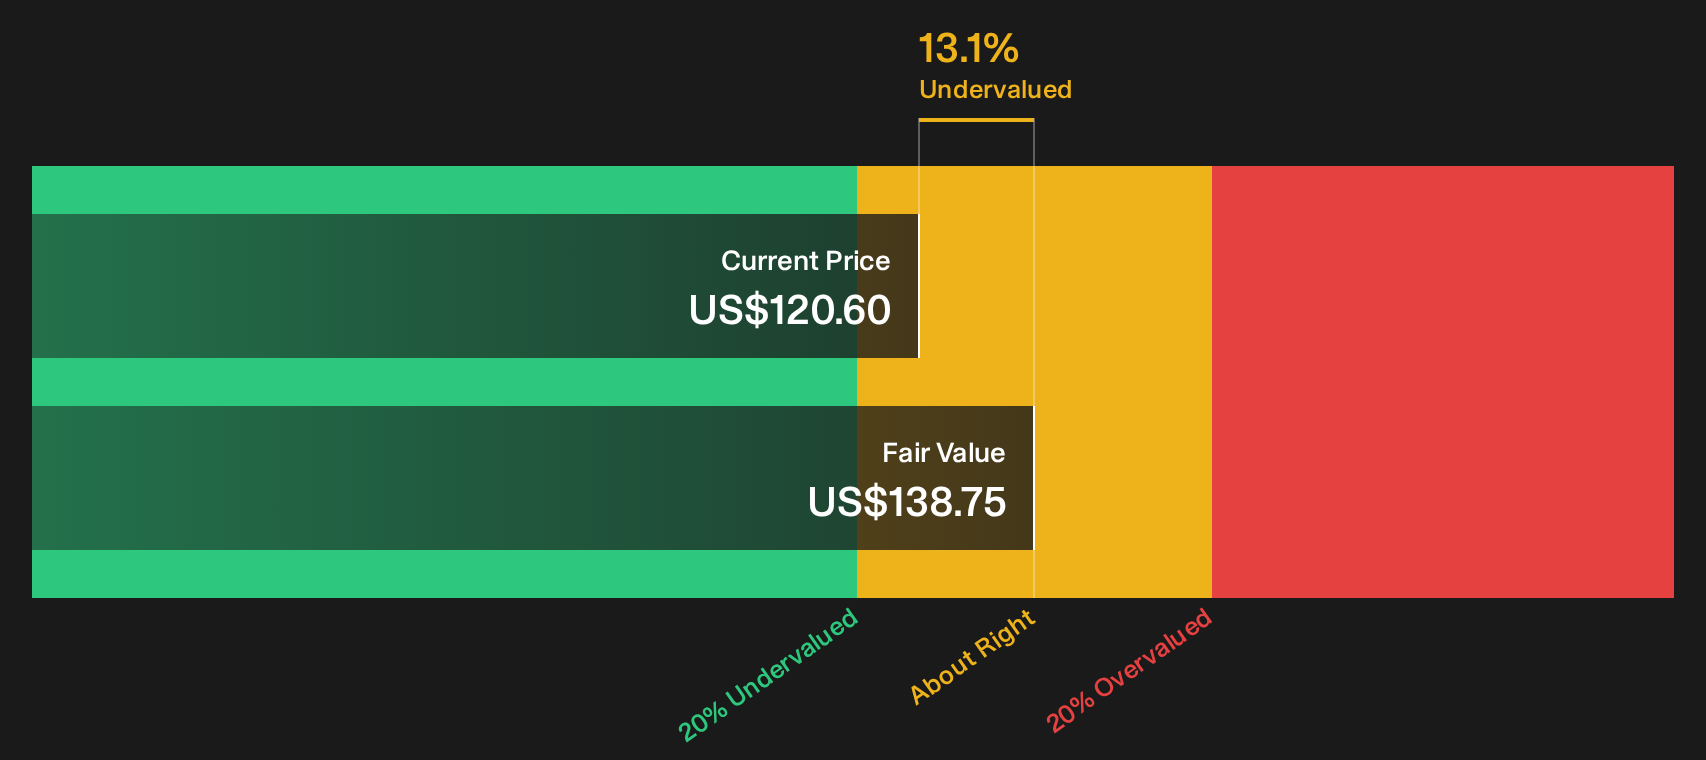
The first narrative pegs AeroVironment as 16% overvalued at $120.60 versus a fair value of $103.94. A different lens tells a very different story. Our DCF model points to a future cash flow value of $138.75, which implies the shares trade at roughly a 13% discount instead.
These are two different frameworks evaluating the same stock. For you as a shareholder, the real question is which set of assumptions feels closer to how AeroVironment will actually convert its backlog and projects into long term cash generation.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the mixed signals around AeroVironment leave you on the fence, use that tension as a prompt to move fast and test the numbers yourself. Then, weigh those projections against the 2 key rewards.
Ready for more investment ideas beyond AeroVironment?
Do not stop at AeroVironment. Use this window to line up a few fresh ideas so the next move in your portfolio is deliberate, not rushed.
- Target quality at a discount by reviewing a 32 high quality undervalued stocks that combines solid fundamentals with prices that trail underlying business strength.
- Protect your downside by filtering for 32 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems before they land on every analyst’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com