
Coinbase (COIN) Stock Looks Fully Priced On Fresh Stablecoin Payments News
Coinbase Global, whose stock trades under the ticker COIN, has seen sharp swings in recent years, and that volatility puts a simple question on the table for investors who track Coinbase Global closely. Does the current share price ask too much of the company’s sales performance, or does it simply mirror what the top line can plausibly support?
- Over the past 3 years the stock has gained 133.9%, which puts a lot of weight on whether today’s valuation can be explained by the revenue it is generating.
- The expanded partnership with Citi to embed stablecoin rails into a payment network handling about US$6 trillion a day can influence how investors think about Coinbase Global’s future transaction volumes and fee based sales potential.
- The analysts covering Coinbase Global have run their own numbers. See what analysts think Coinbase Global's shares could be worth.
The issue now is whether the sales that Coinbase Global produces today, and what investors reasonably expect from them, are enough to justify the current market value placed on the stock.
If you want to test the same sales versus valuation question you are asking of Coinbase Global across a wider set of crypto related plays, spend a few minutes with 18 cryptocurrency and blockchain stocks
Does Coinbase Global Look Pricey on Sales?
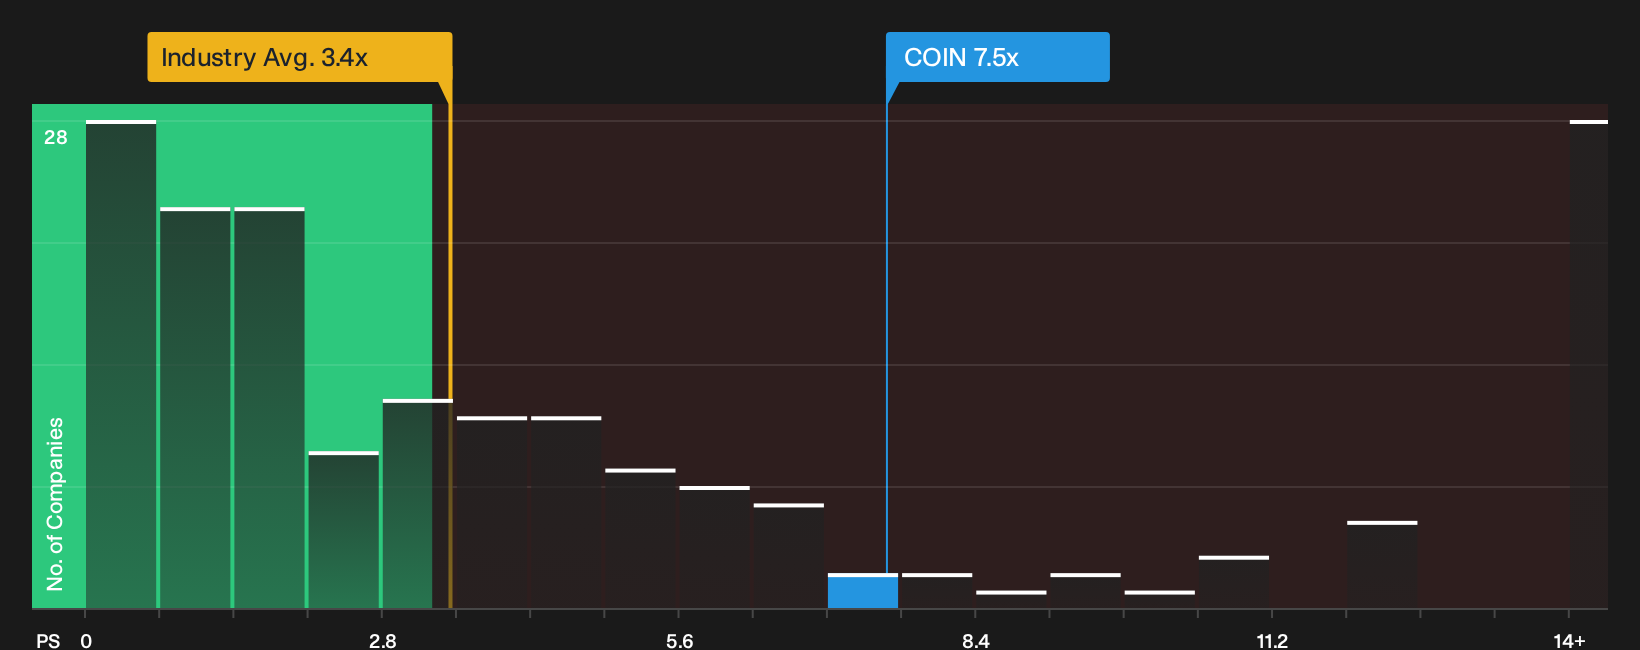
P/S is a useful yardstick for Coinbase Global because investors tend to focus on the revenue it can generate from trading, custody and payment flows rather than near term earnings swings. On that yardstick, Coinbase trades at about 7.5x P/S, which is more than double the broader capital markets industry average of roughly 3.4x and still below the crypto focused peer cohort around 9.5x.
That premium to the wider industry looks consistent with a business tied to crypto volumes and newer payment rails. However, Citi’s stablecoin integration highlights how much optimism is already reflected in the price investors are willing to pay for each dollar of sales. The fair value model that blends Coinbase Global’s growth, margins, size and risk points to a lower P/S as a better anchor, so today’s multiple appears overvalued on this metric. Explore the numbers behind Coinbase Global's P/S valuation.
The Coinbase Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Coinbase Global valuation riddle leaves off. They explain which combinations of growth, profitability and earnings power would need to occur for the stock to be worth materially more or materially less than today’s price, and turn a single P/S or model output into a set of concrete future checkpoints you can follow on Simply Wall St’s Community page to see whether that story is still on track.
Community views on Coinbase Global split around how durable its newer products and partnerships really are versus the weight of trading cycles.
Bull case: 17% undervalued
"The company's leadership in building trusted, compliant infrastructure has resulted in partnerships with major financial institutions, positioning Coinbase as the preferred onramp for institutions entering the digital asset space…"
Discover why this Narrative puts Coinbase Global at 17% undervalued.
Bear case: 68% overvalued
"The current numbers and business mix imply the share price already reflects a rich outcome for Coinbase Global, with limited room for disappointment if diversification and cost discipline do not fully deliver…"
Explore why this Narrative puts Coinbase Global at 68% overvalued.
One more angle on Coinbase Global that could shift the story
There is another lens on Coinbase Global that many investors check after looking at the current multiples, and that is where professional forecasts think this business might be a few years from now. Explore where analysts expect Coinbase Global to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com